For a Monaco-based buyer, a Downtown Miami residence deserves a strategy that connects intended use, ownership structure, annual taxation, and eventual resale. FIRPTA awareness belongs at acquisition, not merely at the closing table years later.
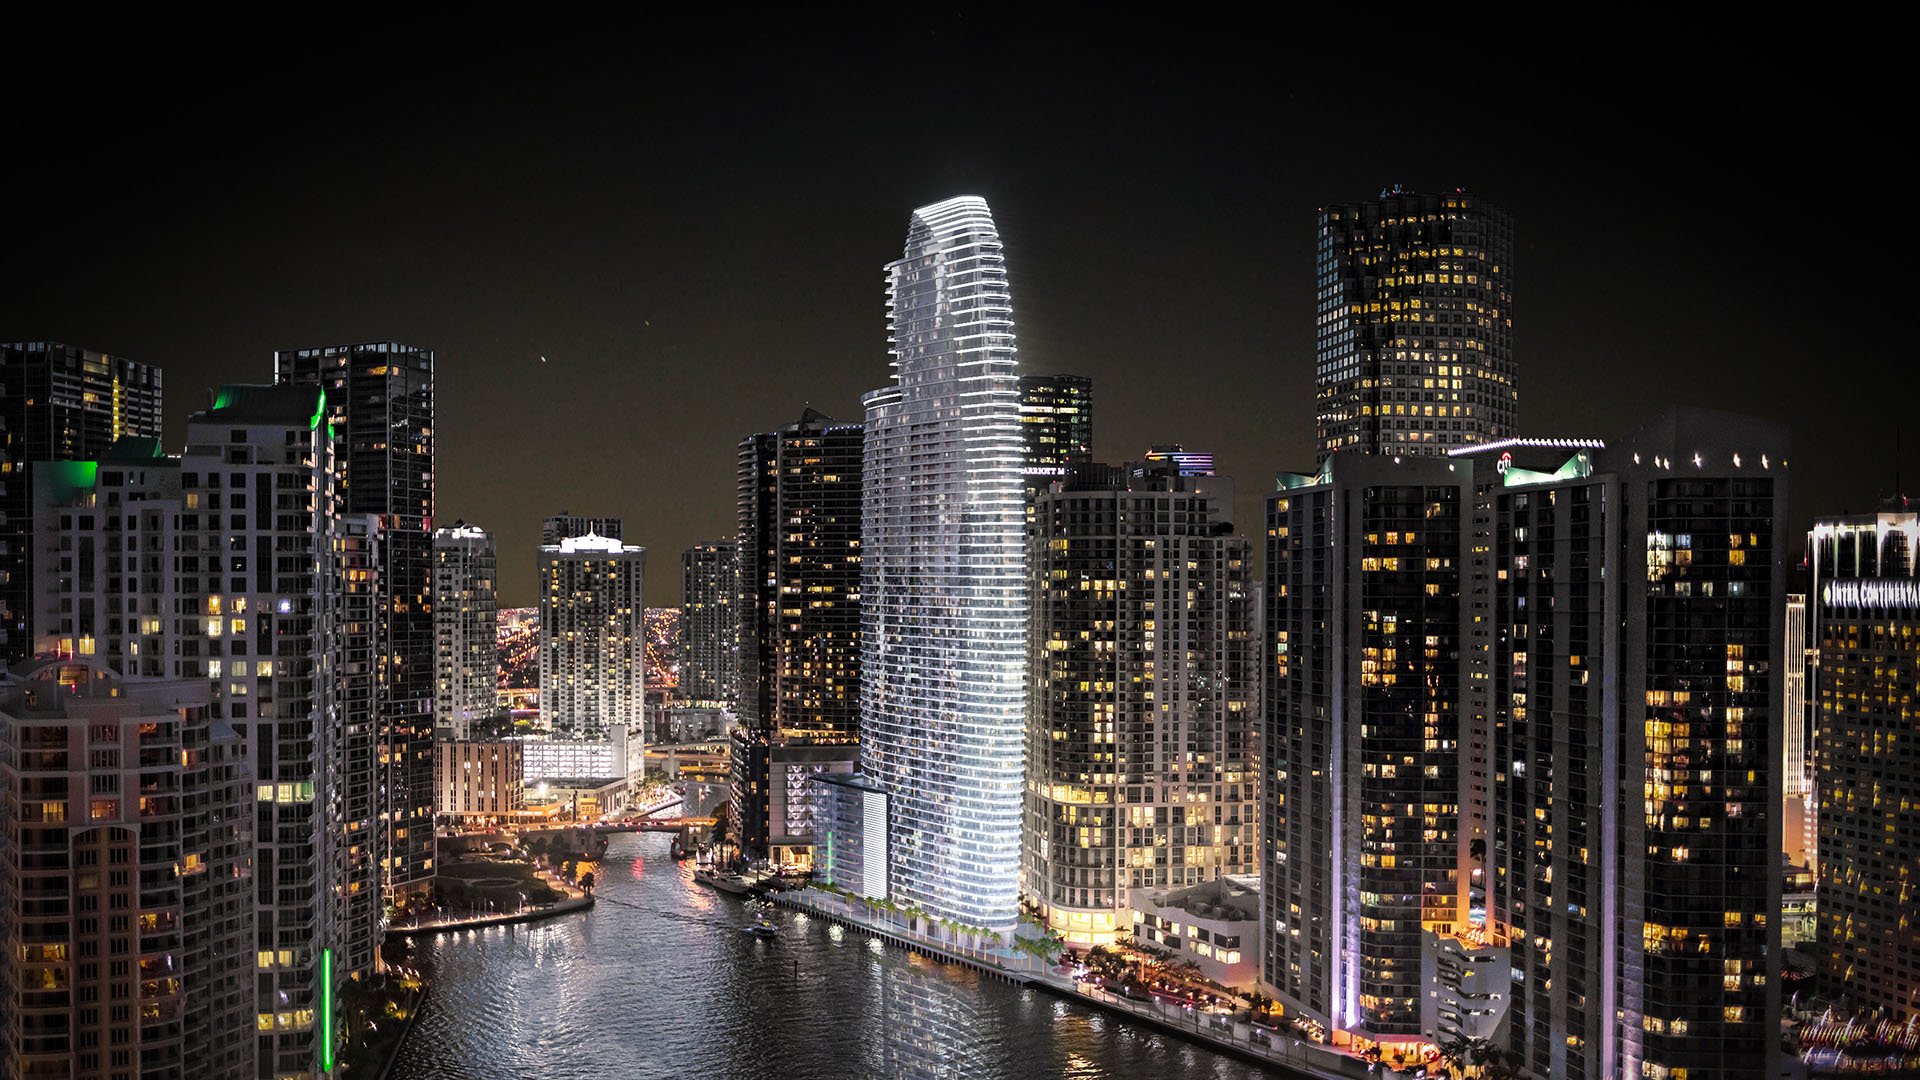
For a Monaco-based buyer considering Downtown Miami, the most consequential decisions may come before the residence is selected. Intended use, U.S. tax classification, ownership structure, and eventual exit should form a single acquisition brief. Even a beautifully chosen home can create avoidable uncertainty if those questions are deferred until resale.
Precision is the starting point: living in Monaco does not, by itself, establish foreign-person status under U.S. tax rules. Nor does it establish eligibility for a reduced treaty rate. U.S. international tax counsel should determine the buyer’s classification before modeling the purchase, annual ownership, or disposition.
A search that includes Aston Martin Residences Downtown Miami can proceed alongside that work. The residence and ownership decisions are related, but neither substitutes for the other. The objective is to preserve personal choice while understanding the financial consequences of each ownership scenario.
FIRPTA generally requires 15% withholding when a foreign person disposes of a U.S. real-property interest. The critical distinction: withholding applies to the amount realized, not merely to profit. A sale at a loss does not automatically remove the obligation.
Amount realized includes cash paid, the fair market value of other property transferred, and liabilities assumed by the purchaser or to which the property remains subject. Counsel should therefore model the contemplated transaction rather than calculate withholding as a percentage of the seller’s expected gain.
Withholding is generally a payment toward the seller’s U.S. tax liability, not necessarily the final tax cost. Excess withholding may be recovered through the applicable U.S. tax-return process. Even so, a temporary reduction in available sale proceeds matters when those funds are intended for another acquisition or a broader liquidity plan.
The general rate has exceptions and special rules, including provisions tied to the purchaser’s intended residential use and certain corporate transactions. These require transaction-specific review-not an assumption that a luxury residence receives different treatment.
The purchaser generally bears responsibility for FIRPTA withholding, while closing agents and settlement officers may also have obligations. A future seller’s preparation should help the closing team establish the correct treatment without last-minute uncertainty.
A federal withholding certificate can reduce or eliminate withholding when applicable requirements are satisfied, including when statutory withholding exceeds the seller’s maximum tax liability. It is a potential planning mechanism, not an automatic entitlement. Counsel should assess eligibility and procedural requirements as part of the disposition plan.
For a buyer evaluating Waldorf Astoria Residences Downtown Miami, the same discipline belongs in the acquisition file: preserve purchase documentation, improvement invoices, entity records, depreciation schedules where relevant, and prior U.S. filings. These records support the eventual tax calculation and the assessment of whether reduced withholding is appropriate.
An entity name is not a tax conclusion. For FIRPTA purposes, the owner of a disregarded entity, rather than the entity itself, is generally treated as the transferor. An LLC label therefore does not establish an exemption from withholding.
Entity ownership can also leave exposure at another level. Qualifying interests in domestic U.S. real-property holding corporations are themselves U.S. real-property interests. A purchaser acquiring a U.S. real-property interest from a foreign partnership generally must withhold 15% of the amount realized.
These distinctions make a universal recommendation inappropriate. Counsel should compare prospective structures against the buyer’s intended use, annual tax treatment, and anticipated exit. Estate-tax exposure, succession, financing, and liability protection deserve separate legal review, not a single promise of tax efficiency.
A nonresident alien’s gain or loss on disposing of a U.S. real-property interest is generally treated as effectively connected with a U.S. trade or business. That underlying tax treatment must be considered alongside withholding; resolving one question does not resolve the entire ownership plan.
If the residence will generate rental income, the annual analysis changes. U.S. rental income received by a nonresident alien is generally taxed at 30% of gross income, or a lower applicable treaty rate, when it is not effectively connected with a U.S. trade or business. Under that treatment, associated expenses generally cannot be deducted against the gross-income tax.
An eligible nonresident owner may make a section 871(d) election to treat income from U.S. real property held for income production as effectively connected income. This permits eligible deductions and taxation on net income. The election generally applies to all qualifying U.S. real-property income, not just one selected residence.
The election requires a statement attached to the applicable U.S. return and generally continues in later years unless properly revoked. Taxpayer-identification and withholding documentation must also be coordinated with the applicable withholding agent.
When considering Casa Bella by B&B Italia Downtown Miami, obtain the governing documents before projecting rental income. A tax election does not establish a building’s leasing permissions. Personal, rental, and mixed-use scenarios should be evaluated separately with counsel.
Florida homestead relief is tied to a permanent residence. A seasonal or occasional Miami home should not be budgeted as qualifying merely because its owner spends meaningful time there.
Miami-Dade homestead eligibility requires a separate review of permanent-residence status and the relevant January 1 requirements. That property-tax inquiry is separate from the federal classification that determines FIRPTA treatment.
Homestead exemption, the Save Our Homes assessment limitation, and portability are distinct benefits. Their eligibility and transfer rules require separate review. For a Monaco-based household, the prudent ownership budget should reflect confirmed eligibility, not an assumed saving.
Before settling the ownership arrangement, ask U.S. international tax counsel to connect three scenarios: acquisition, annual use, and eventual disposition. The comparison should identify the relevant taxpayer, expected filing and documentation obligations, rental treatment if applicable, and potential resale withholding.
Whether the shortlist includes One Thousand Museum Downtown Miami or another residence, keep building diligence and tax diligence distinct. Confirm governing-document restrictions separately from the legal analysis of ownership. Revisit the model if intended use changes, and maintain supporting records throughout ownership.
The result is not a universally preferred entity or a promise of tax-free ownership. It is a considered residence strategy that evaluates the home, the holding arrangement, and the future exit together. This is a planning framework, not individualized tax or legal advice.
For a discreet conversation about your Downtown Miami residence search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Monaco residence alone does not establish U.S. tax classification, which should be determined by U.S. international tax counsel.
The general rate is 15% of the amount realized when a foreign person sells a U.S. real-property interest. Exceptions and special rules may apply.
No. It is generally calculated on the amount realized, including cash, other property transferred, and relevant liabilities, so a loss does not automatically eliminate withholding.
The purchaser generally bears responsibility. Closing agents and settlement officers may also have obligations under the rules.
No. It is generally a payment toward U.S. tax liability, and excess withholding may be recovered through the applicable tax-return process.
A federal withholding certificate can reduce or eliminate withholding when applicable requirements are met. Counsel should evaluate eligibility and procedural requirements before relying on this option.
Not automatically. For a disregarded entity, the owner is generally treated as the transferor, so the LLC label alone does not establish an exemption.
When it is not effectively connected with a U.S. trade or business, it is generally taxed at 30% of gross income or a lower applicable treaty rate. Associated expenses generally cannot be deducted against that gross-income tax.
For an eligible nonresident owner, it treats qualifying U.S. real-property income as effectively connected income, permitting eligible deductions and net-income taxation. It generally applies to all qualifying U.S. real-property income.
Not automatically, because homestead relief is tied to a permanent residence. Miami-Dade eligibility requires a separate review of permanent-residence status and the relevant January 1 requirements.