A practical framework for Toronto buyers considering Downtown Miami, connecting ownership structure, estate-plan liquidity, title review, homestead eligibility, and documented residence operating costs.
For a Toronto household considering Downtown Miami, choosing a residence is also an exercise in financial continuity. The purchase should suit the family’s intended use, align with its estate arrangements, and allow the home to keep operating when an owner is absent or unable to act. A compelling interior is only part of the decision.
Start by distinguishing a permanent residence from a seasonal retreat or investment property. Then ask cross-border counsel to evaluate the proposed ownership structure before the deed is prepared. The objective is not to choose a trust, entity, or personal ownership arrangement by convention, but to make the title, estate documents, and funding plan work together.
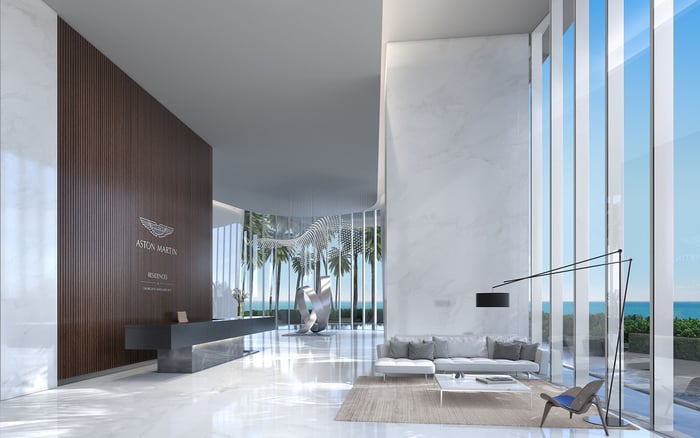
When considering Aston Martin Residences Downtown Miami, apply that framework to the specific residence and transaction. A project name should never substitute for a review of the actual ownership documents, settlement estimate, and ongoing obligations.
Build two U.S.-dollar budgets: one for acquisition, another for continued ownership. The acquisition budget should include the purchase price and itemized closing costs. The operating budget should cover property taxes, association dues, insurance, utilities, maintenance, and a reserve for special assessments.
Then test the operating budget against death or incapacity. Ask counsel and financial advisers which funds would be available, who would have authority to make payments, and which arrangements should be completed in advance. An intended beneficiary and a person authorized to manage expenses serve distinct planning roles.
Rather than adopting an arbitrary reserve figure, size the liquidity provision to documented costs and a family-specific planning period. Ask how it would accommodate exchange-rate changes, unexpected assessments, and expenses due while an estate is being administered. The goal is to keep the residence operating without depending on an immediate sale or an improvised transfer of funds.
Request an itemized settlement estimate and the title commitment early enough for counsel to review both before closing. Ask the closing team to explain the proposed insured ownership, exceptions, required endorsements, and any unresolved liens. Treat title review as a substantive discussion, not merely another signature appointment.
Read the condominium declaration alongside the purchase documents. Confirm how parking and storage rights are described and whether their treatment is consistent across the agreement, recorded documents, and proposed coverage. Have counsel identify anything requiring clarification or correction before funds are released.
For a residence under consideration at One Thousand Museum Downtown Miami, the questions remain transaction-specific: what precisely is being acquired, which rights accompany it, and what does the proposed policy address? Do not assume that every use right, contractual promise, or future ownership change is covered. Request an explanation tied to the actual policy terms.
Ask cross-border counsel to reconcile the intended Miami ownership with wills, trusts, and account beneficiary forms. Prepare a single planning inventory identifying the intended recipients, the accounts expected to fund the residence, and the people expected to handle administration. Resolve inconsistencies before closing rather than leaving the family to interpret them later.
The review should also address incapacity: who would communicate with the association, authorize maintenance, and arrange payments? Ask advisers to document the appropriate authority and access arrangements. Do not assume that a family relationship alone answers those questions.
Purchasing a condominium does not establish Florida homestead eligibility. The property generally must be the owner’s permanent residence or the permanent residence of a dependent. Do not budget a seasonal home or investment condominium as though that exemption were assured.
The first $25,000 of the homestead exemption applies to all property-tax levies, including school-district taxes. The additional exemption generally applies to assessed value above $50,000 and excludes school-district taxes. Confirm the applicable tax-year amount before incorporating it into a budget.
Save Our Homes limits annual assessment increases on qualifying homesteaded property, but buyers should not assume the seller’s treatment carries over. Applications are generally due by March 1 for the relevant tax year, and Miami-Dade offers an online application process.
Portability transfers a qualifying Florida homestead assessment difference, not a tax bill. The maximum transferable difference is $500,000, subject to the applicable three-assessment-year window. A Toronto residence does not itself create a Florida benefit transferable to Miami.
A later transfer into a trust or entity should not be an administrative afterthought. Florida has no blanket documentary-stamp-tax exemption for transfers made for estate-planning purposes. Ask counsel to analyze the proposed transaction before signing a new deed.
Miami-Dade documentary stamp tax on deeds is $0.60 for each $100, or portion thereof, of taxable consideration, with an additional $0.45-per-$100 surtax in applicable transactions. Have the closing team determine applicability rather than automatically combining those rates. Tax on recorded documents is paid to the county clerk or recording official when the document is recorded.
If considering Casa Bella by B&B Italia Downtown Miami, resolve the intended ownership before completing the purchase wherever practical. If the plan later changes, revisit documentary taxes, title coverage, and beneficiary coordination together.
Evaluate each residence using its own financial documents. Request association dues, the current budget, reserve information, assessment notices, and insurance details. Obtain a residence-specific insurance quotation and clarify which expenses fall outside association charges. Amenities and presentation are no substitute for that review.
For Waldorf Astoria Residences Downtown Miami, apply the same discipline: distinguish documented current charges from projections, and ask what could change before ownership begins. Do not treat a preliminary estimate as a guaranteed carrying cost.
Before closing, assemble a concise ownership file containing the settlement estimate, title review, tax assumptions, operating budget, and counsel-approved continuity arrangements. The best choice is a residence the household can enjoy and administer with equal confidence.
Explore Downtown Miami residences with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Eligibility generally requires the property to be the owner’s permanent residence or the permanent residence of a dependent.
Not without confirming eligibility. A seasonal or investment condominium should not be assumed to qualify for the permanent-residence exemption.
It applies to all property-tax levies, including school-district taxes. Confirm the applicable additional exemption separately before budgeting.
Applications are generally due by March 1 for the relevant tax year. Miami-Dade provides an online application process.
No. Portability concerns an existing Florida homestead assessment benefit, not a benefit arising from a Toronto residence.
The maximum is $500,000. Miami-Dade rules also require establishing the new homestead within the applicable three-assessment-year window.
Request the title commitment and review the proposed insured ownership, exceptions, liens, and required endorsements with counsel. Review the condominium declaration and parking and storage rights alongside those documents.
No. Florida provides no blanket exemption for estate-planning transfers, so proposed trust or entity transfers require transaction-specific analysis.
Include acquisition costs, property taxes, association dues, insurance, utilities, maintenance, and a special-assessment reserve. Ask advisers to evaluate payment access and authority during death or incapacity.
Have cross-border counsel reconcile the intended ownership structure, wills, trusts, and account beneficiary forms. Also address who would manage and fund the residence during death or incapacity.