For buyers considering this private waterfront address, rental underwriting begins with permitted lease terms, not hotel-style occupancy. Asking rents, operating expenses and personal use must be separated before a headline projection becomes a useful ownership analysis.
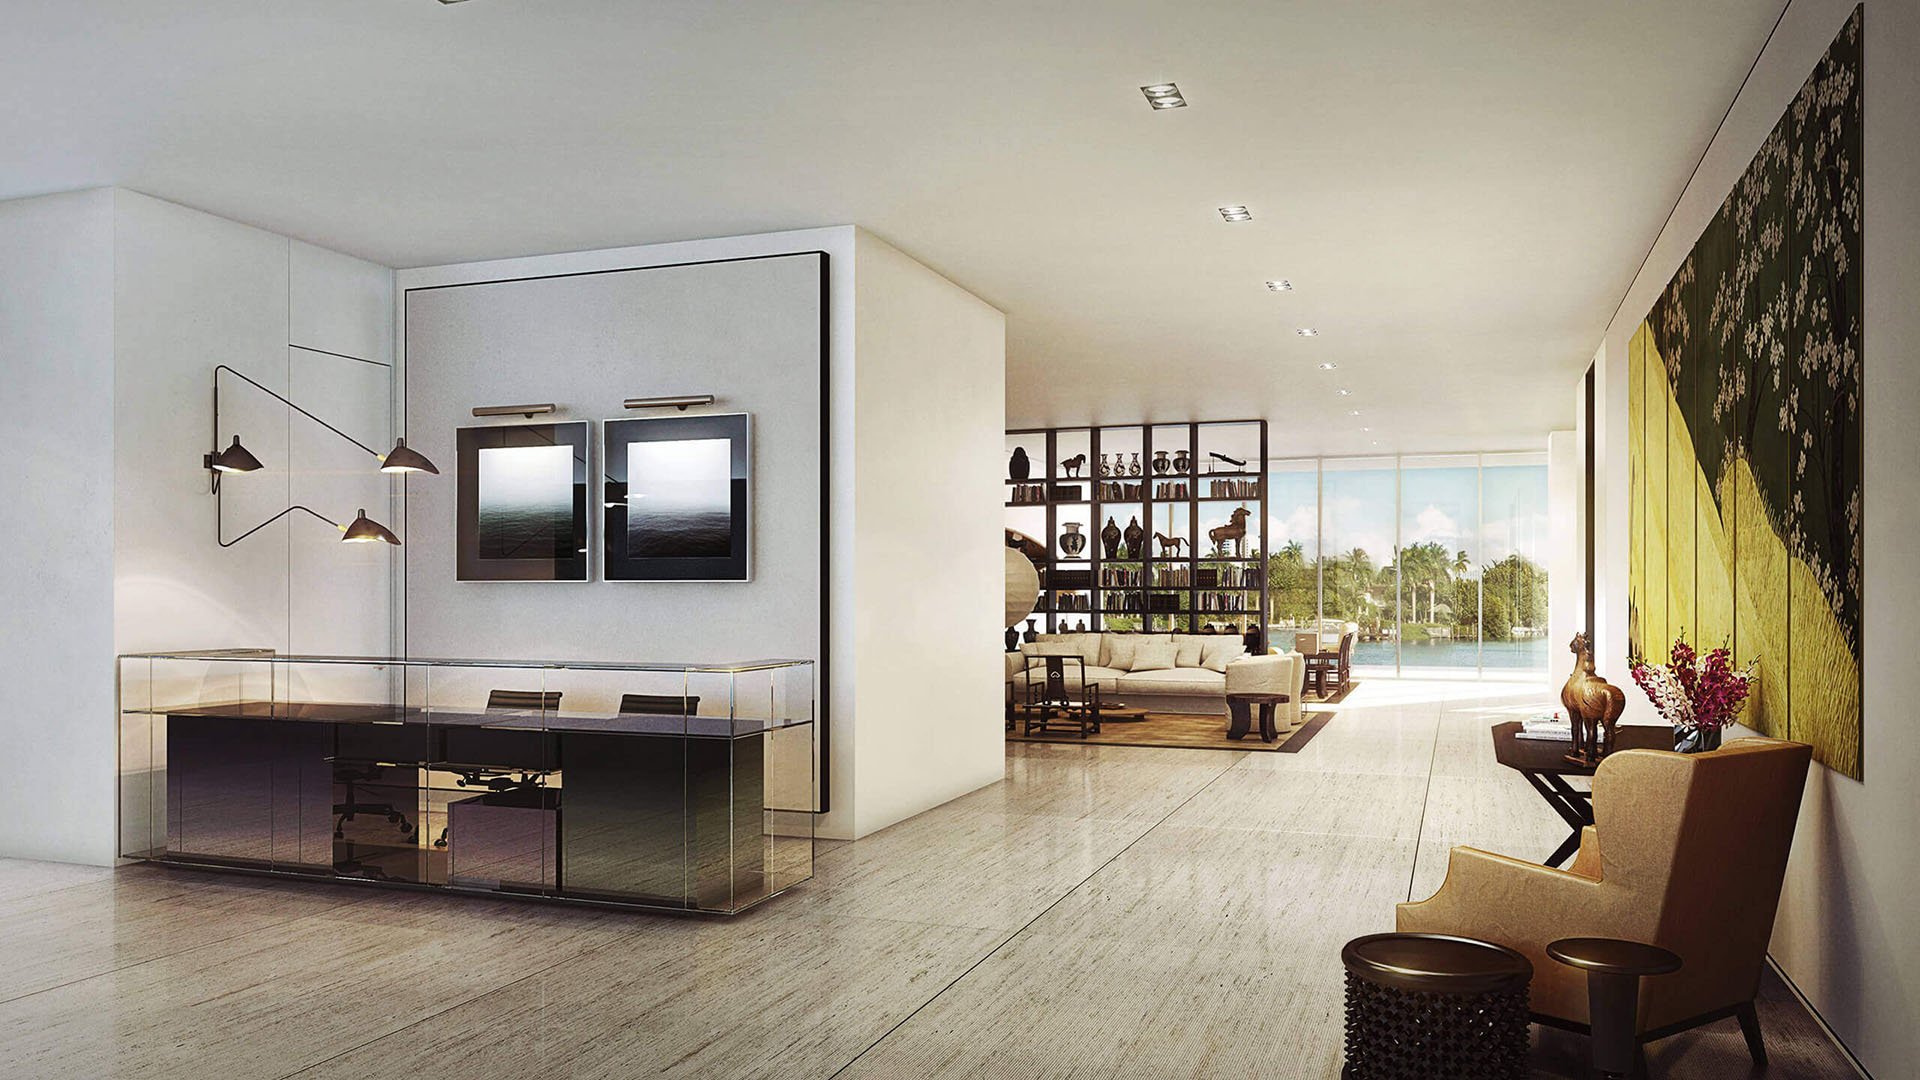
At The Ritz-Carlton Residences® Miami Beach, the purchase proposition begins with waterfront living, Piero Lissoni’s design and a private residential setting. Located at 4701 N Meridian Avenue, Miami Beach, FL 33140, the community comprises 111 condominium residences and 15 stand-alone villas. A private marina and bespoke services add to its appeal.
Those qualities should not be confused with a hotel investment structure. This is a private residential community with no hotel on the premises and no short-term rentals allowed. Buyers should not presume a formal hotel rental pool, an operator revenue split or a guaranteed rental return.
The useful question is not simply what a residence might earn, but what an income projection assumes about legal availability, tenant demand, expenses and the owner’s calendar. A gross revenue figure cannot answer all four.
The term “rental program” deserves scrutiny before any spreadsheet is accepted. Ask whether it means tenant placement, ongoing property management or a contractual operating arrangement. These are distinct services with different responsibilities and potential costs. Brand affiliation alone establishes none of them.
Keep the property’s identity equally precise. The Ritz-Carlton Residences® South Beach is a separate address, not an interchangeable reference for the Meridian Avenue community. Rental permissions and financial assumptions must apply to the specific residence being purchased, not merely to a shared name.
If an income illustration is presented, request the underlying agreement and a clear explanation of who finds tenants, collects rent, handles repairs and pays each expense. Without those distinctions, “managed” says little about the owner’s eventual cash flow.
The leasing framework to verify is a six-month minimum and no more than two leases per year. Treat that as a starting point, not a substitute for current association documents and written confirmation of the terms applicable to the unit.
Miami Beach’s municipal language also matters. Rentals shorter than six months and one day are prohibited in single-family homes and multifamily buildings in certain areas. A shorthand reference to “six months” is not equivalent to that threshold. Confirm both the applicable city requirements and the association’s rules before committing to a lease calendar.
These restrictions do not make full-year occupancy impossible; they limit flexibility. A compliant longer tenancy can support sustained occupancy, while a gap between tenants remains a vacancy assumption rather than an automatic consequence of the rules.
That framework does not support filling gaps with nightly or weekly bookings. Nor should an owner assume that seasonal personal use can always fit around permissible lease terms. Illegal short-term rentals can expose owners to fines and tenants to eviction.
A September 2026 listing snapshot for Unit 325 showed an unfurnished two-bedroom, 2.5-bath residence of 2,382 square feet asking $30,000 monthly. A separate 2025 snapshot advertised five residences at $32,500 to $55,000 monthly. These are dated asking-price observations, not proof of executed leases or present availability.
The distinction matters. Neither snapshot establishes concessions, the time required to secure a tenant, actual occupancy or rent collected. Differences in dates and residences also prevent a clean comparison of rental performance.
Multiplying the $30,000 asking figure by twelve produces $360,000 in annualized gross scheduled rent. That is arithmetic, not an income forecast. It assumes the asking rent is achieved and paid throughout the year, with no vacancy or concessions, before any ownership expense.
Request executed lease evidence for genuinely comparable residences where available. Then assess the subject unit’s condition, furnishing status and permitted availability rather than carrying the highest advertised figure into the purchase model.
A useful underwriting presentation should distinguish four stages rather than compress them into one attractive yield:
Gross scheduled rent: rent modeled across the assumed leasing calendar, before collection losses or expenses.
Collected rent: receipts after accounting for vacancy, concessions and unpaid amounts.
Net operating income: rental income less property operating expenses, before financing costs.
Cash flow after debt service: the result after loan payments, with capital spending and assessments also shown explicitly.
For each figure, identify the period covered and the assumptions used. A full-year income estimate should not sit beside a partial-year expense allowance. An owner-use period should not also appear as tenant availability.
Any quoted yield needs a defined denominator. Ask whether it uses purchase price alone or includes acquisition costs and the capital required to prepare the residence for leasing. Broad branded-residence yield estimates are no substitute for this building’s unit-level economics.
The expense review should cover association dues, assessments, insurance, property taxes, repairs, tenant-placement commissions, management fees and legal costs. Financing belongs in the cash-flow analysis, not folded into operating performance. Confirm which items apply, who pays them and when they fall due.
Service-rich ownership makes this exercise particularly important. Amenities and staffing drive operating costs even when the residence generates no rent. The value of service to an owner is distinct from its effect on investment returns.
Do not presume a separate brand fee or a standard management percentage. Request the actual association schedule and any proposed management contract. Distinguish recurring expenses from capital work and special assessments so that neither is omitted or counted twice.
For buyers also considering The Perigon Miami Beach, use the same document-led comparison rather than assuming equivalent rental rules or cost structures. Compare ownership on documented terms, not projected revenue in isolation.
Personal enjoyment is a legitimate part of the return, but it should remain separate from rental income. Begin with the dates the owner wants to occupy the residence. Then determine whether the remaining calendar can accommodate compliant leases, tenant transitions and any necessary preparation.
Test a case in which leasing takes longer or achieves less than expected while ownership obligations continue. The purpose is not to predict a disappointing outcome, but to establish whether the purchase remains comfortable without relying on perfect execution.
At this address, architecture, privacy and service can justify a compelling lifestyle decision. Rental income may complement that decision, but it should be evaluated through verified permissions, achievable rent and a complete expense schedule-not treated as a promise embedded in the brand.
For a considered approach to South Florida ownership and residence selection, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe property is at 4701 N Meridian Avenue, Miami Beach, FL 33140. It is distinct from other Ritz-Carlton residential properties in South Florida.
It is described as a private residential community with no hotel on the premises. Buyers should not presume a formal hotel rental pool, operator revenue split or guaranteed return.
The reported framework is a six-month minimum lease and a maximum of two leases annually. Obtain current association documents and written confirmation before relying on those terms.
No. Miami Beach uses a six-month-and-one-day threshold for certain rental prohibitions, so buyers should confirm the requirements applicable to the specific unit.
No, they limit leasing flexibility rather than make full-year occupancy impossible. Actual vacancy remains an underwriting assumption.
The reported leasing restrictions do not support nightly or weekly gap-filling rentals. Illegal short-term rentals can result in fines against owners and tenant eviction.
It establishes a September 2026 asking-price observation for Unit 325, not an achieved lease rate. Annualizing it does not demonstrate occupancy, collections or net income.
Review association dues, assessments, insurance, property taxes, repairs, placement commissions, management fees and legal costs. Show financing separately when calculating cash flow after debt service.
Net operating income deducts property operating expenses from rental income before financing costs. Cash flow after debt service also accounts for loan payments, with capital spending and assessments made explicit.
Remove owner-use dates from the rental calendar and check whether the remaining availability supports compliant leases. Personal enjoyment should be evaluated separately from financial rental returns.