For Los Angeles buyers making Edgewater their permanent home, the purchase calendar matters as much as the residence. January 1 eligibility, the post-purchase assessment reset and any qualifying Florida portability benefit should be considered before closing.
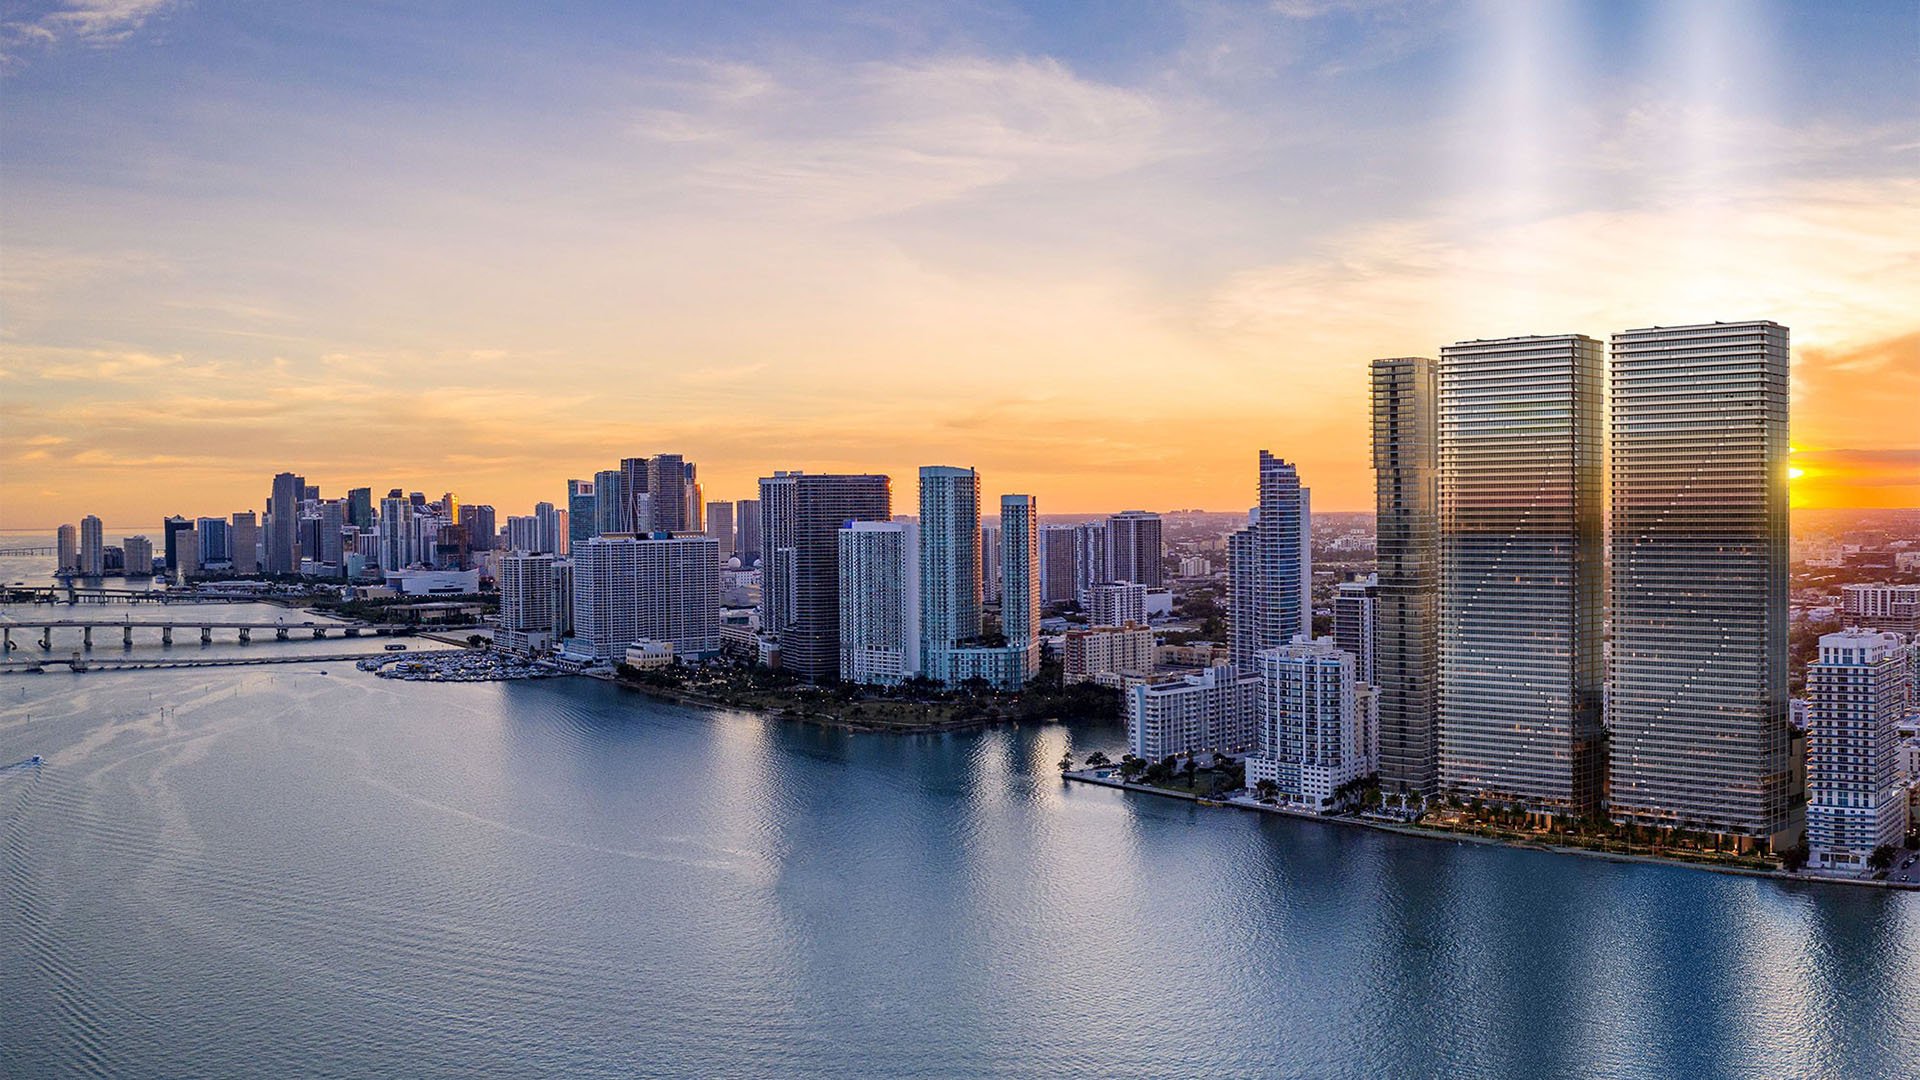
For a buyer leaving Los Angeles, an Edgewater residence should offer more than a different view and a new daily rhythm. If the purchase is intended to anchor Florida homestead eligibility, it must become a permanent residence. Ownership alone is insufficient, however substantial the investment or carefully chosen the address.
That distinction belongs at the beginning of the search. When considering Aria Reserve Miami, the question is not whether a project name confers a tax advantage. It is whether the specific residence, closing schedule and intended use support the buyer’s actual relocation.
Three matters require separate attention: establishing permanent residence, applying for homestead exemption and determining whether any prior Florida assessment benefit is portable. They converge at a critical date: the first January 1 after closing. Treating them as automatic consequences of a purchase risks misunderstanding both the timeline and the cost of ownership.
Florida homestead eligibility generally requires ownership and permanent residence as of January 1 of the tax year. The regular application deadline is March 1 of that same year. The dates serve distinct purposes: January 1 tests eligibility; March 1 governs the ordinary filing schedule.
A buyer closing after January 1 generally cannot claim their own homestead exemption for that closing year. The earliest qualifying year is generally the following year, provided ownership and permanent residence are established by its January 1. Filing before March 1 does not replace the January 1 requirement.
For someone evaluating EDITION Edgewater, the acquisition calendar is therefore part of the selection process. Confirm when the specific home can support permanent residence; a projected closing date is not a complete relocation plan. Even a purchase before year-end requires the residence itself to qualify on January 1.
Applications and supporting documentation belong with the property appraiser where the home is located-in Miami-Dade for Edgewater. Online applications are available for both homestead and portability. If the regular deadline has passed, seek guidance on available procedures rather than assuming automatic acceptance or permanent loss of benefits.
Permanent residence is a factual determination, initially made by the property appraiser. No single evidentiary factor is conclusive. A declaration of domicile can contribute to the record, but it cannot substitute for genuinely making the property a permanent home.
Relevant evidence can include Florida voter registration, a Florida driver’s license, vehicle registration, dependent children’s school registration and utility bills. Treat these as a coherent record of the move, not isolated documents collected to secure a result.
The practical residential test matters just as much. Can the home support the household’s ordinary life rather than occasional visits? When considering Villa Miami, assess the specific residence against that intended use and your relocation timetable. Neither the building’s identity nor the purchase price establishes the owner’s eligibility.
For a household retaining ties to Los Angeles, the distinction is important: Florida homestead eligibility does not independently settle California income-tax residency. That question requires separate advice. A successful Florida property-tax application is not a comprehensive determination of the interstate move.
The first January 1 after a typical purchase brings another consequential event: reassessment at just value. The seller’s exemptions and accumulated Save Our Homes benefit do not automatically transfer to the buyer. An attractive existing tax bill is historical context, not a reliable forecast of the buyer’s future liability.
Homestead exemption and Save Our Homes also serve different purposes. The first $25,000 of homestead exemption applies to all taxing authorities. An additional exemption applies to qualifying assessed value above $50,000 and excludes school taxes. Assessed value and taxable value are not interchangeable, and the exemption structure does not affect every levy identically.
Save Our Homes generally limits annual increases in assessed value to the lower of 3% or the applicable CPI change. It does not impose a blanket ceiling on the total tax bill. Its annual assessment limitation generally begins in the year after the property first receives the buyer’s homestead exemption.
Budget in that sequence: consider the post-purchase assessment reset, determine the exemptions and any portable benefit for which you qualify, then establish when the annual limitation begins. Do not simply carry the seller’s bill into your ownership model.
For buyers arriving directly from Los Angeles, portability is an easily misunderstood term. It transfers some or all of an eligible homeowner’s accumulated Save Our Homes assessment difference from a prior Florida homestead to a new Florida homestead. California property-tax treatment does not transfer.
The transferable benefit is capped at $500,000. That figure represents an assessment benefit-not a cash payment, tax-bill credit or guaranteed reduction in taxes. The amount available depends on eligibility and the applicable calculation. The ceiling is not an assumed entitlement.
A buyer with a qualifying prior Florida homestead must also verify the relevant timeline. The new homestead exemption must be established within three years of January 1 of the year the old homestead was abandoned. The three-year period is not measured from the sale date.
To request portability, file Form DR-501T with the new homestead application, Form DR-501, ordinarily by March 1 of the year for which the new exemption is sought. Review the former homestead’s history before relying on a benefit in the acquisition budget.
Whether assessing The Cove Residences Edgewater or another residence, organize due diligence around four questions: when ownership begins, when permanent residence can genuinely be established, what the next January 1 means for assessment and whether a prior Florida homestead creates portability eligibility.
Before closing, ask your advisers to distinguish the seller’s tax position from your expected position. Align the move with the eligibility date, assemble the supporting residency record and calendar the regular filing deadline. Where portability may apply, verify the abandonment timeline and required forms rather than relying on the sale date.
The strongest choice is more than a residence that suits the desired lifestyle. Its timing and actual use must support the intended permanent home, with ownership costs evaluated on the buyer’s facts rather than the seller’s history.
For a considered approach to selecting your Edgewater residence, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Florida homestead eligibility generally requires ownership and permanent residence as of January 1, followed by a timely application.
Generally not for that closing year. The earliest qualifying year is generally the following year, provided ownership and permanent residence are established by January 1.
January 1 is the ownership and permanent-residence eligibility date. March 1 is the regular application deadline for the year in which the exemption is sought.
Evidence can include a declaration of domicile, Florida voter registration, a Florida driver’s license, vehicle registration, dependent children’s school registration and utility bills. No single factor is conclusive.
Applications go to the Miami-Dade property appraiser. Online applications are available for both homestead exemption and the Homestead Assessment Difference, also called portability.
Not reliably. Following a typical purchase, the property is reassessed at just value on the next January 1, and the seller’s exemptions and Save Our Homes benefit do not automatically transfer.
No. It generally limits annual increases in assessed value to the lower of 3% or the applicable CPI change, with the limitation generally beginning the year after the buyer first receives homestead exemption.
No. Florida portability requires a qualifying prior Florida homestead assessment benefit; the transferable amount is capped at $500,000 and is not a cash payment or tax-bill credit.
The new homestead exemption must be established within three years of January 1 of the year the old homestead was abandoned, not three years after its sale. File DR-501T with DR-501, ordinarily by March 1 of the year for which the new exemption is sought.
No. Florida property-tax eligibility does not independently determine California income-tax residency, which requires separate advice.