For a future foreign seller at La Baia North, FIRPTA belongs in the ownership plan from the beginning. Understanding gross-price withholding, residence-use exceptions and certificate planning helps distinguish eventual tax liability from cash available at resale.
A considered purchase at La Baia North Bay Harbor Islands involves more than selecting a residence and preparing for closing. For an owner who will be classified as a foreign person for U.S. tax purposes at resale, it also requires understanding how much of the sale proceeds may be withheld before the balance becomes available.
FIRPTA, the Foreign Investment in Real Property Tax Act, is best understood here as an exit-liquidity consideration. Withholding is not the final tax. That distinction matters when proceeds from one home are intended to fund another purchase or meet other commitments.
The planning question is not simply whether a resale will produce a gain. It is whether the owner has accounted for the difference between the transaction’s gross price, cash available at closing and the tax ultimately determined through the applicable return process.
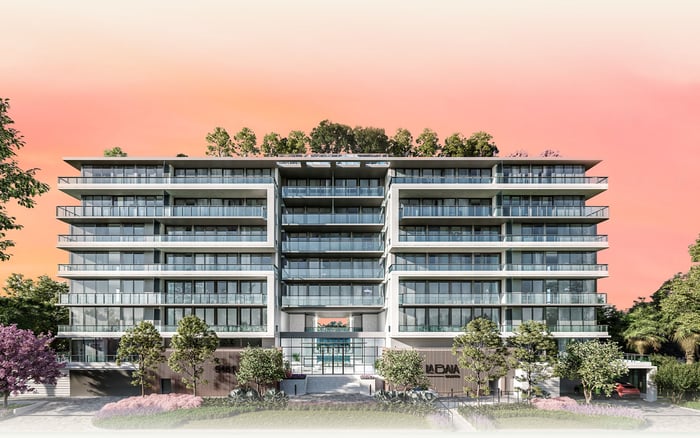
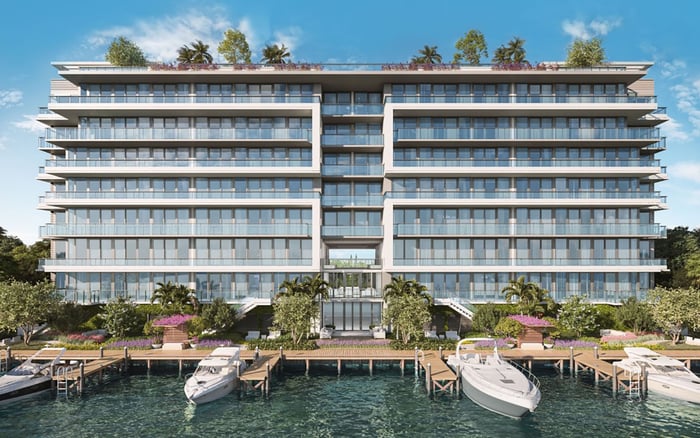
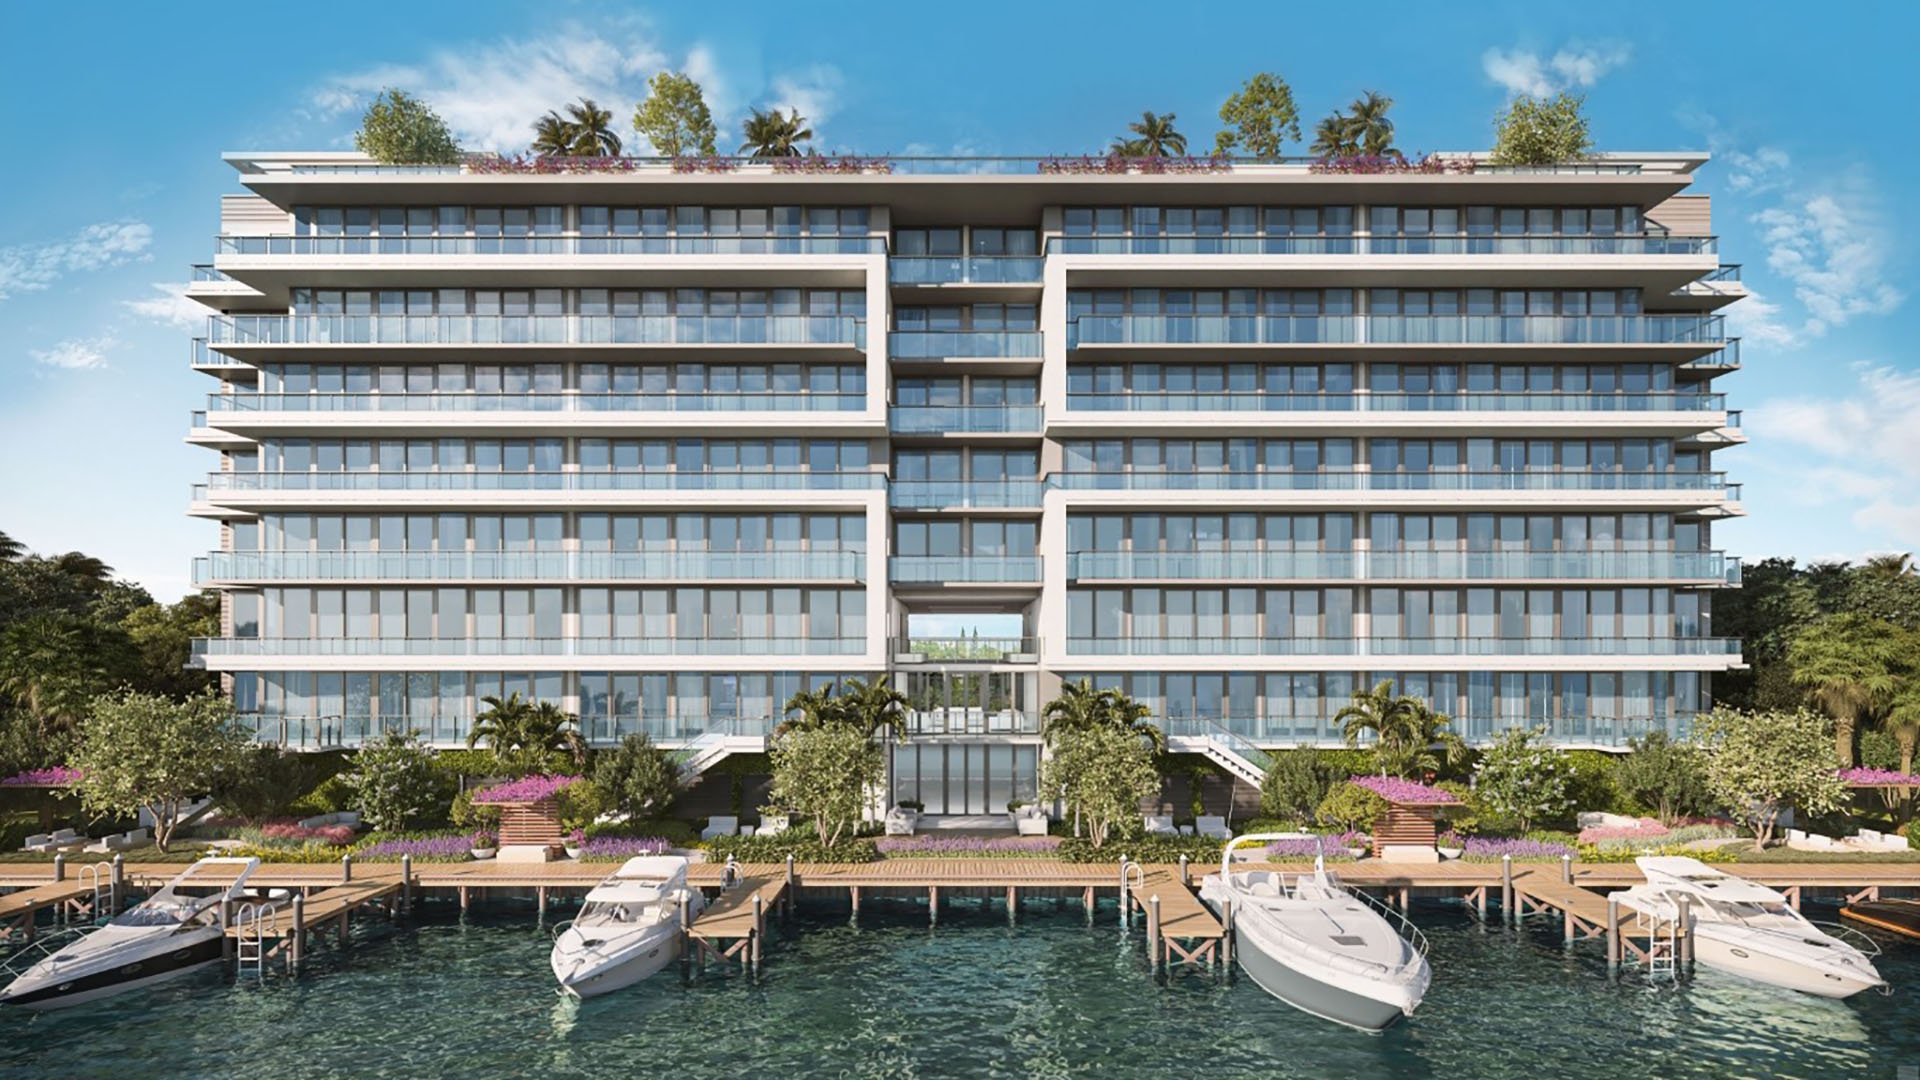
La Baia North is an eight-story, 57-residence waterfront condominium at 9481 East Bay Harbor Drive, Bay Harbor Islands, FL 33154. Developed by Continuum Company, it is the second of the developer’s two La Baia waterfront condominium projects in Bay Harbor Islands.
Historical pricing advertised on April 16, 2025, started at $1.4 million. That figure provides launch-stage context, not a current quote or a forecast of resale value. The project had topped off by April 25, 2026, but that construction milestone does not establish occupancy or completed closings.
These distinctions keep the ownership discussion precise. A construction milestone concerns the building’s progress; FIRPTA concerns a qualifying transfer from a foreign seller. A purchaser’s foreign status does not, by itself, make the initial acquisition subject to withholding. What matters is the seller’s status in the transaction under review-including today’s purchaser when that owner eventually resells.
Foreign-person status is a U.S. tax classification. It should not be inferred solely from a passport, citizenship or an overseas mailing address. Before a future resale, qualified advisers should establish the seller’s status and determine the withholding treatment that follows.
When FIRPTA applies, the buyer generally must withhold 15% of the gross sale price or amount realized, unless an exception or authorized reduction applies. The calculation is not limited to the seller’s profit. A modest gain, or even an expected loss, does not itself replace that gross-price calculation.
This is not an automatic requirement for the buyer to provide an additional 15% in cash above the purchase price. It is the buyer’s withholding obligation, with the withheld amount reducing the foreign seller’s immediately available proceeds.
For a purchaser also considering Bay Harbor Towers, the same distinction belongs in the financial comparison: preferences between residences do not replace transaction-specific analysis of tax status and proceeds.
The withholding thresholds deserve careful attention, particularly when planning a luxury resale. A qualifying residence purchase with an amount realized of $300,000 or less can be exempt from FIRPTA withholding. Above $300,000 and through $1 million, a qualifying residence purchase can receive a reduced 10% rate.
For a foreign-owner resale above $1 million, the standard 15% rate generally applies even if the buyer intends to live in the residence, unless another applicable exception or IRS-authorized reduction applies. La Baia North’s historical starting price makes this threshold worth understanding, but it does not establish the price or treatment of any future sale.
Residence-based relief depends on qualifying use by the buyer or family. Calling a property a second home neither proves eligibility nor automatically rules it out. Nor does eligibility turn solely on the buyer’s citizenship. The actual use requirements and transaction amount need review; a lifestyle description is no substitute.
Investment or rental purchases that fail the residence-use test do not qualify for the residence-based zero or 10% withholding provisions. An owner preparing to sell should not assume that every prospective buyer will support reduced withholding simply because the property is residential.
The amount withheld is not a measure of investment performance. The foreign seller determines actual U.S. income-tax liability through the applicable tax-return process and may recover excess withholding. Cash withheld at closing and final tax liability can differ materially, even when the sale itself is straightforward.
For an owner considering a subsequent purchase at Rivage Bal Harbour, prudent planning separates immediately available proceeds from any potential later recovery. An anticipated refund is not cash already available for the next closing.
Good records are part of disciplined ownership. Preserve purchase-price documentation, improvement records and selling-expense records so advisers can substantiate basis and actual taxable gain when reconciling withholding. An orderly file can provide a firmer foundation for the eventual tax analysis than a reconstruction undertaken while a sale is pending.
If required withholding would exceed the applicable tax liability, a foreign seller may apply for an IRS withholding certificate using Form 8288-B to request a reduction. An expected low tax bill is not, on its own, permission to withhold less. Certificate planning is a separate step that deserves attention before closing arrangements are finalized.
The buyer generally must remit withholding to the IRS by the 20th day after closing, with Form 8288 used in the reporting process. Certificate-related timing and exceptions require specific professional review; this general deadline is not a complete closing protocol. Establish early who will prepare the forms, coordinate any certificate application and handle remittance.
Before the initial purchase closes, discuss the future disposition with qualified legal and tax advisers. Ownership structure, including any proposed entity or trust, requires individualized analysis-not a generic recommendation presented as a FIRPTA solution.
During ownership, maintain the supporting records. Before resale, revisit seller tax status, expected withholding treatment and responsibility for the paperwork. Build the proceeds discussion around cash likely to be available at closing, treating any authorized reduction or later recovery separately.
This is general planning context, not individualized tax advice or a complete account of FIRPTA exceptions. For La Baia North, the objective is straightforward: understand the potential exit obligation early enough to keep it from becoming a late negotiation over funds or timing.
For a considered approach to your next South Florida residence, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationLa Baia North is an eight-story, 57-residence waterfront condominium developed by Continuum Company at 9481 East Bay Harbor Drive in Bay Harbor Islands.
No. Topping off is a construction milestone and does not confirm occupancy or completed closings.
No. FIRPTA withholding generally depends on the seller’s foreign-person status, not simply the purchaser’s status.
No. It is a U.S. tax classification that should be established rather than inferred from citizenship or an overseas address.
No. It generally applies to the gross sale price or amount realized, not merely the seller’s gain.
For a foreign-owner resale above $1 million, the standard 15% rate generally applies even with buyer residence use, unless another exception or authorized reduction applies.
No. Eligibility depends on qualifying use by the buyer or family and the applicable amount threshold; the second-home label alone does not decide it.
No. Actual U.S. income-tax liability is determined through the applicable tax-return process, and the seller may recover excess withholding.
A seller may apply for an IRS withholding certificate using Form 8288-B when required withholding would exceed the applicable tax liability. An expected small gain or loss does not itself authorize a reduction.
The buyer generally must remit it by the 20th day after closing, with Form 8288 used in reporting. Certificate-related timing and exceptions require professional review.