A cash purchase at Five Park through an LLC or trust calls for careful coordination of ownership, financing and closing responsibilities. Any claimed FinCEN pause requires transaction-specific confirmation, while document preparation remains prudent.
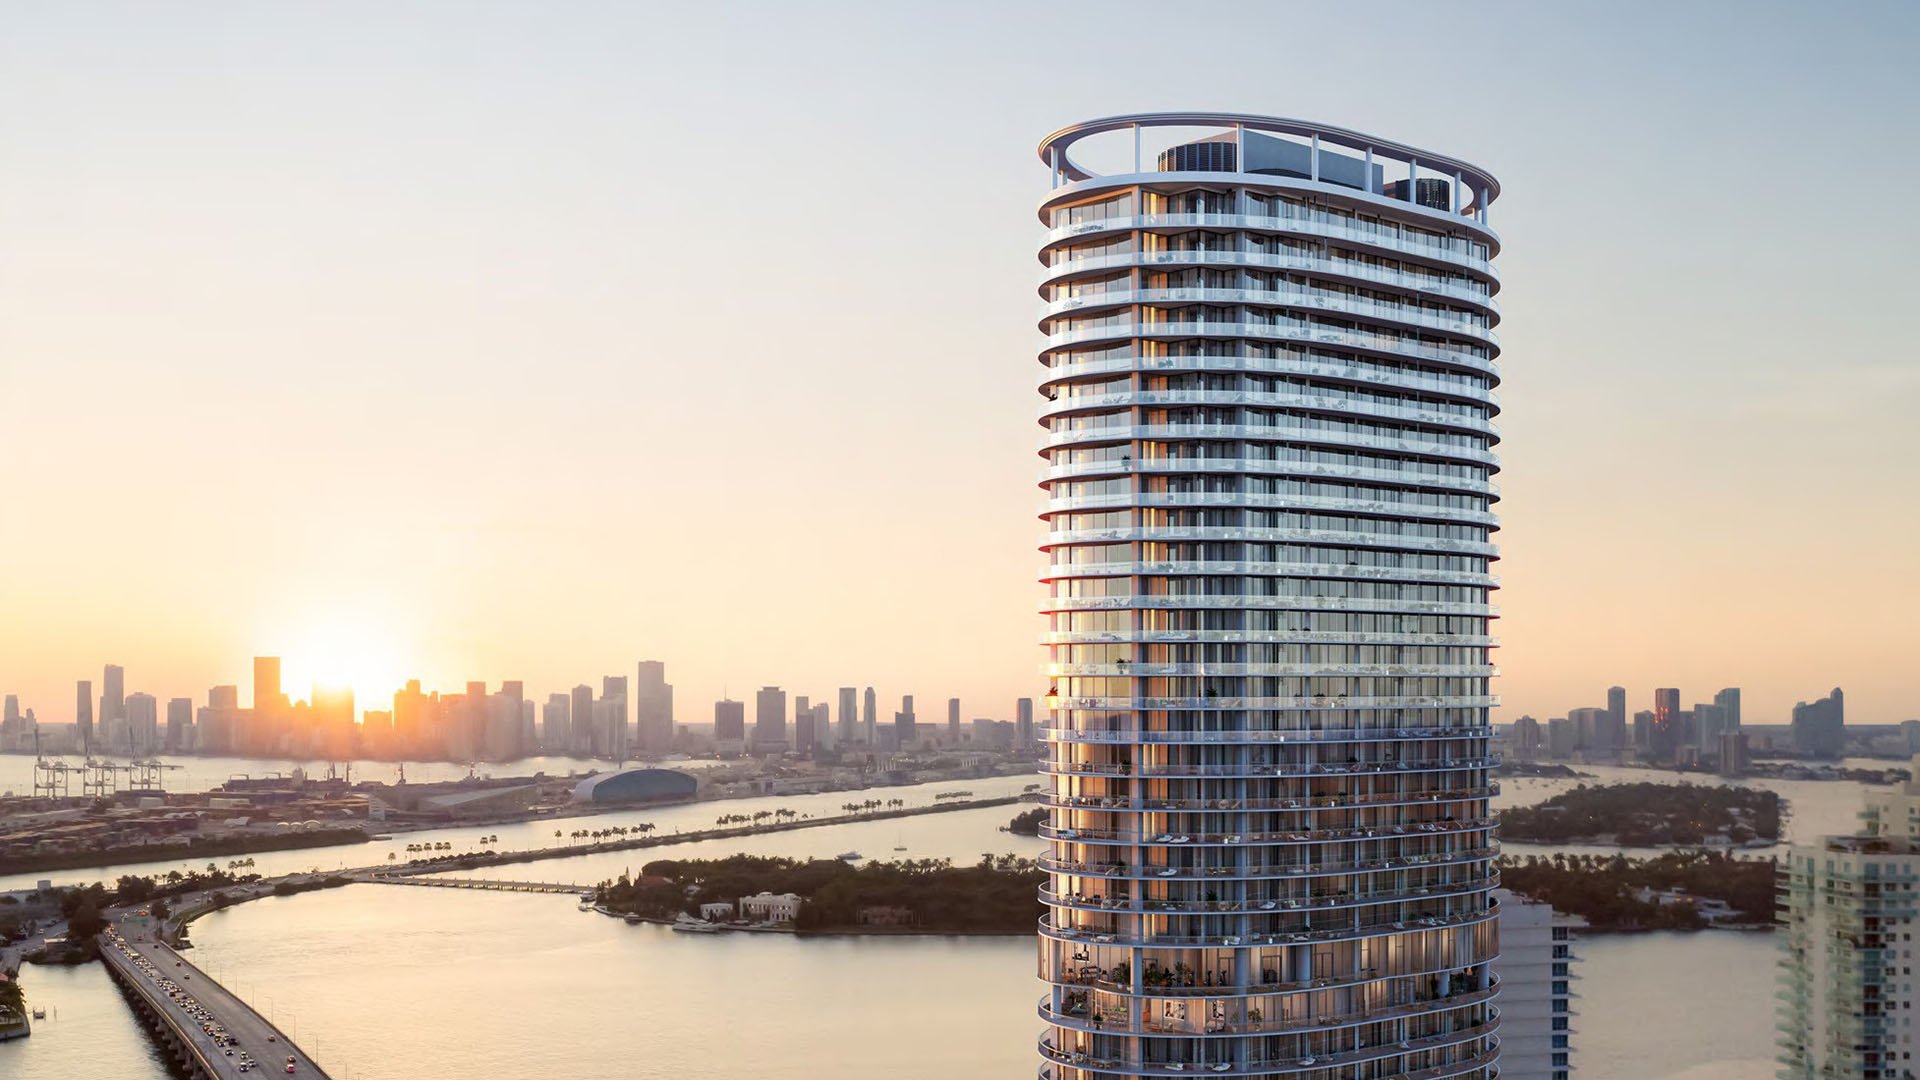
For a buyer at Five Park Miami Beach, the closing structure deserves the same attention as the residence itself. The property at 500 Alton Road was developed by Terra and GFO Investments, with completion reported in November 2024. When an LLC or trust will hold title, the closing conversation extends beyond the name on the deed to the individuals behind that structure.
The word “paused” is not, by itself, a closing instruction. Whether FinCEN reporting is currently required, suspended or subject to relief must be confirmed for the transaction before anyone relies on that characterization. A buyer should not assume that a pause has a particular duration, applies universally or eliminates liability.
The practical distinction is between understanding the reporting framework and establishing an obligation to file today. Preparing ownership documents is prudent planning-not a conclusion that a Real Estate Report must currently be submitted.
FinCEN’s Residential Real Estate Reporting Rule establishes a nationwide framework for certain non-financed residential transfers to legal entities or trusts, unless an exemption applies. Condominium units fall within its residential-property definition. A Five Park acquisition can therefore fit the framework, depending on its financing, purchaser and applicable exemptions.
Before closing, ask counsel to confirm the current legal position, the scope of any applicable suspension and the treatment of your anticipated closing date. If relief is available, its terms matter more than the shorthand used to describe it.
Keep three regimes separate: nationwide Real Estate Reports, Geographic Targeting Orders and Corporate Transparency Act beneficial-ownership filings. They are not interchangeable. A conclusion about one does not resolve the obligations under another, and older guidance about LLC filings should not determine a present closing decision.
Within this framework, “non-financed” is broader than paying entirely from existing cash. To fall outside that definition, financing must be secured by the transferred property and provided by a financial institution subject to specified anti-money-laundering and suspicious-activity-reporting obligations.
Borrowed money alone does not resolve the question. Counsel should examine both the security for the financing and the lender’s qualifying status, rather than rely on an informal description of the transaction as financed.
This distinction is equally useful when comparing a Five Park purchase with a potential acquisition at Apogee South Beach. The analysis follows the transfer and its structure, not the prestige of the address. A Miami Beach condominium is not outside the framework simply because the purchase is privately arranged or involves a sophisticated ownership vehicle.
Entity ownership is part of Five Park’s transaction history. In February 2025, TCH 500 Alton LLC sold Unit 4801 to Trubreeze LLC. That transaction illustrates an entity holding title; it does not establish that the acquisition was non-financed or reportable under this framework.
For a covered entity transfer, beneficial owners include individuals who directly or indirectly exercise substantial control or own or control at least 25% of the entity’s ownership interests at closing. Ownership percentages alone are insufficient: substantial control is a separate basis for inclusion.
Ask advisers to map both ownership and control before the closing package is finalized. An LLC designation is not itself an exemption. Certain qualifying publicly traded companies and regulated financial institutions are exempt, but eligibility requires analysis of the actual purchaser.
A trust should not be analyzed as though it were simply an LLC with different terminology. The framework’s trust provisions encompass trustees and specified beneficiaries, grantors or settlors. Certain entity-held roles also require a further look through to individuals.
Preparation should begin with a clear account of the trust’s relevant parties, powers and ownership relationships. Counsel should identify which people qualify under the rule, rather than assume that every named beneficiary must be included or that naming the trustee completes the analysis.
Qualifying trusts formed under either U.S. or foreign law can be covered. Foreign formation alone does not create an exemption. For an internationally organized household, the question is how the trust fits the framework-not merely where its documents were executed.
Where reporting applies, an entity or trust does not remove the requirement to disclose qualifying beneficial owners to FinCEN. Required beneficial-owner information includes legal name, date of birth, current residential street address, citizenship and a unique identifying number.
The Real Estate Report also identifies the purchasing entity or trust, seller, property, signing individuals and payment information. Ownership structure and payment arrangements should therefore be reviewed together, not treated as unrelated closing details.
For a buyer also considering Faena House Miami Beach, the same principle holds: the titleholding name is only one part of the analysis. Do not equate an entity name with guaranteed public-record anonymity. Nor should you assume that banks automatically receive access to Real Estate Reports. Ask counsel to distinguish required disclosures from the separate question of who may access particular records.
Under the framework, filing responsibility falls on a designated reporting person involved in the closing, potentially a settlement agent, title professional or attorney. It does not automatically fall on the buyer. Early buyer coordination can nevertheless help the closing team assemble the information needed if reporting is required.
A practical preparation sequence is to:
Confirm the exact purchaser and proposed titleholding structure.
Identify relevant owners, controlling individuals and trust parties.
Review financing, security and any proposed exemption with counsel.
Establish who would serve as reporting person and how sensitive information should be delivered.
Reconfirm the applicable legal status before closing and any resulting filing deadline.
When filing is required, the framework sets the deadline as the later of 30 calendar days after closing or the last day of the following month. Treat that as a conditional rule, not a declaration that your transaction currently carries a filing obligation.
Cash transfers directly to individuals fall outside this entity-and-trust reporting framework, although other applicable compliance requirements may remain. That distinction should inform advice, not become the sole reason to change the intended purchaser.
For a Five Park buyer, the disciplined approach is to align the ownership structure, financing and closing documentation, then confirm the legal position applicable to the transfer. Evaluate any claimed pause on its actual terms. Readiness and a current filing duty remain separate questions, and this overview is not a substitute for transaction-specific legal advice.
For a discreet perspective on South Florida residences and the decisions surrounding ownership, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationYes. Condominium units are included, so a non-financed purchase through a legal entity or trust can fit the framework unless an exemption applies.
Not without confirmation. Closing counsel should establish the current legal status, the scope of any applicable suspension and its effect on the specific transfer.
No. Financing must be secured by the transferred property and provided by a financial institution subject to specified anti-money-laundering and suspicious-activity-reporting obligations to fall outside the non-financed definition.
The framework includes individuals who directly or indirectly exercise substantial control or own or control at least 25% of the entity's ownership interests at closing.
The trust provisions encompass trustees and specified beneficiaries, grantors or settlors. Certain entity-held roles require additional look-through analysis.
No. The framework covers qualifying trusts formed under U.S. or foreign law, so foreign formation alone does not exempt a purchase.
Required information includes legal name, date of birth, current residential street address, citizenship and a unique identifying number.
Responsibility falls on a designated reporting person involved in the closing, potentially a settlement agent, title professional or attorney. The buyer is not automatically the filer.
The framework specifies the later of 30 calendar days after closing or the last day of the following month. Counsel should confirm whether a filing obligation applies to the transaction.
Cash transfers directly to individuals are outside this entity-and-trust reporting framework. Other applicable compliance requirements may still remain.