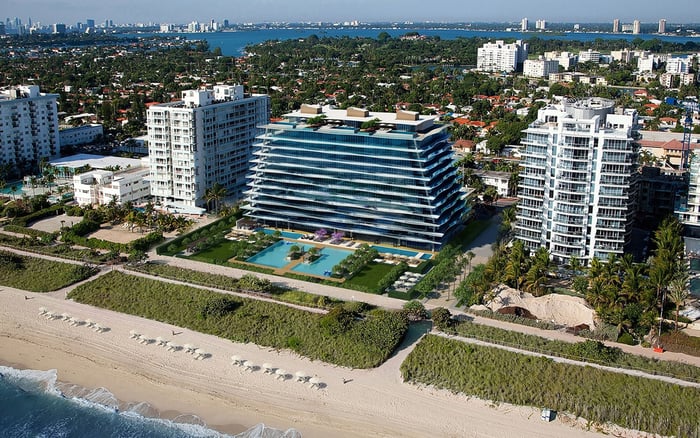
A discreet operating framework for a Singapore-Surfside household, separating family-office approvals from legal signing authority, scoped retention obligations, and practical vendor controls.
A life between Singapore and Surfside should feel effortless to the family, even when its administration is complex. The residence is only one part of the arrangement. Ownership, banking, signing authority, document custody, and household services must function when the principal is elsewhere.
For a family considering The Surf Club Four Seasons Surfside, operational questions deserve attention alongside the residential decision: who can approve the acquisition, who can bind the purchaser, and who can release funds? These are separate permissions. A family-office employee may have budget authority without legal authority to execute closing documents.
The recommendations below are operating choices, not universal statutory requirements. Their purpose is to make a cross-border household dependable while keeping internal governance distinct from obligations imposed on regulated institutions.
Singapore’s 2023 proposed single-family-office framework contemplated Singapore incorporation, a business relationship with at least one regulated financial institution, and a continuously designated Singapore-resident employee contact. These were proposal terms, not established universal requirements. They should not be read as a blanket description of every family office’s obligations.
The banking framework is separate. Banks must conduct anti-money-laundering and counter-terrorism-financing checks on single-family offices and their managed investment vehicles. Financial institutions must identify customers and beneficial owners, conduct regular account reviews, and monitor and report suspicious transactions. Those duties belong to the relevant institutions; they do not automatically impose identical duties on every family office.
As an operating recommendation, maintain a current ownership chart, identification file, and record of authorized representatives. A property acquisition should prompt an internal check that information supplied to the bank remains accurate. Where a family office participates in a relevant Singapore scheme, additions or replacements of related persons or entities require notification when they change material application information.
A useful approval record distinguishes the residence decision from subsequent spending. It can identify the purchasing party, approved acquisition budget, funding route, authorized signers, and the person responsible for each deadline. Counsel should confirm whether the chosen ownership structure requires separate entity resolutions or other authority documents.
When evaluating Arte Surfside, for example, the family can establish this approval structure without making assumptions about the project’s contracts or procedures. Approval to pursue a residence should not silently extend to every subsequent furnishing, maintenance, or advisory engagement.
Consider separate internal approval categories for acquisition commitments, recurring household expenses, and exceptional work. Assign a primary approver and a backup, with written limits suited to the family’s preferences rather than an invented industry threshold. Record exceptions, including who approved them and why.
Most importantly, separate approval, execution, and payment release wherever practical. These controls are recommendations, not legal mandates. They keep staff from having to guess whether a conversational instruction authorizes a binding commitment when the principal is absent.
Florida law defines a power of attorney as a written instrument granting an agent authority to act in the principal’s place, regardless of whether the document carries that title. A seller can authorize another person to sign real-estate closing documents through a power of attorney specifying the powers granted.
For a real-estate power of attorney, plan for two subscribing witnesses and proper notarization. This is not a complete cross-border signing checklist. Counsel should confirm the instrument’s execution and acceptance requirements with the title company and, where applicable, the lender, particularly when the signatory is outside the United States.
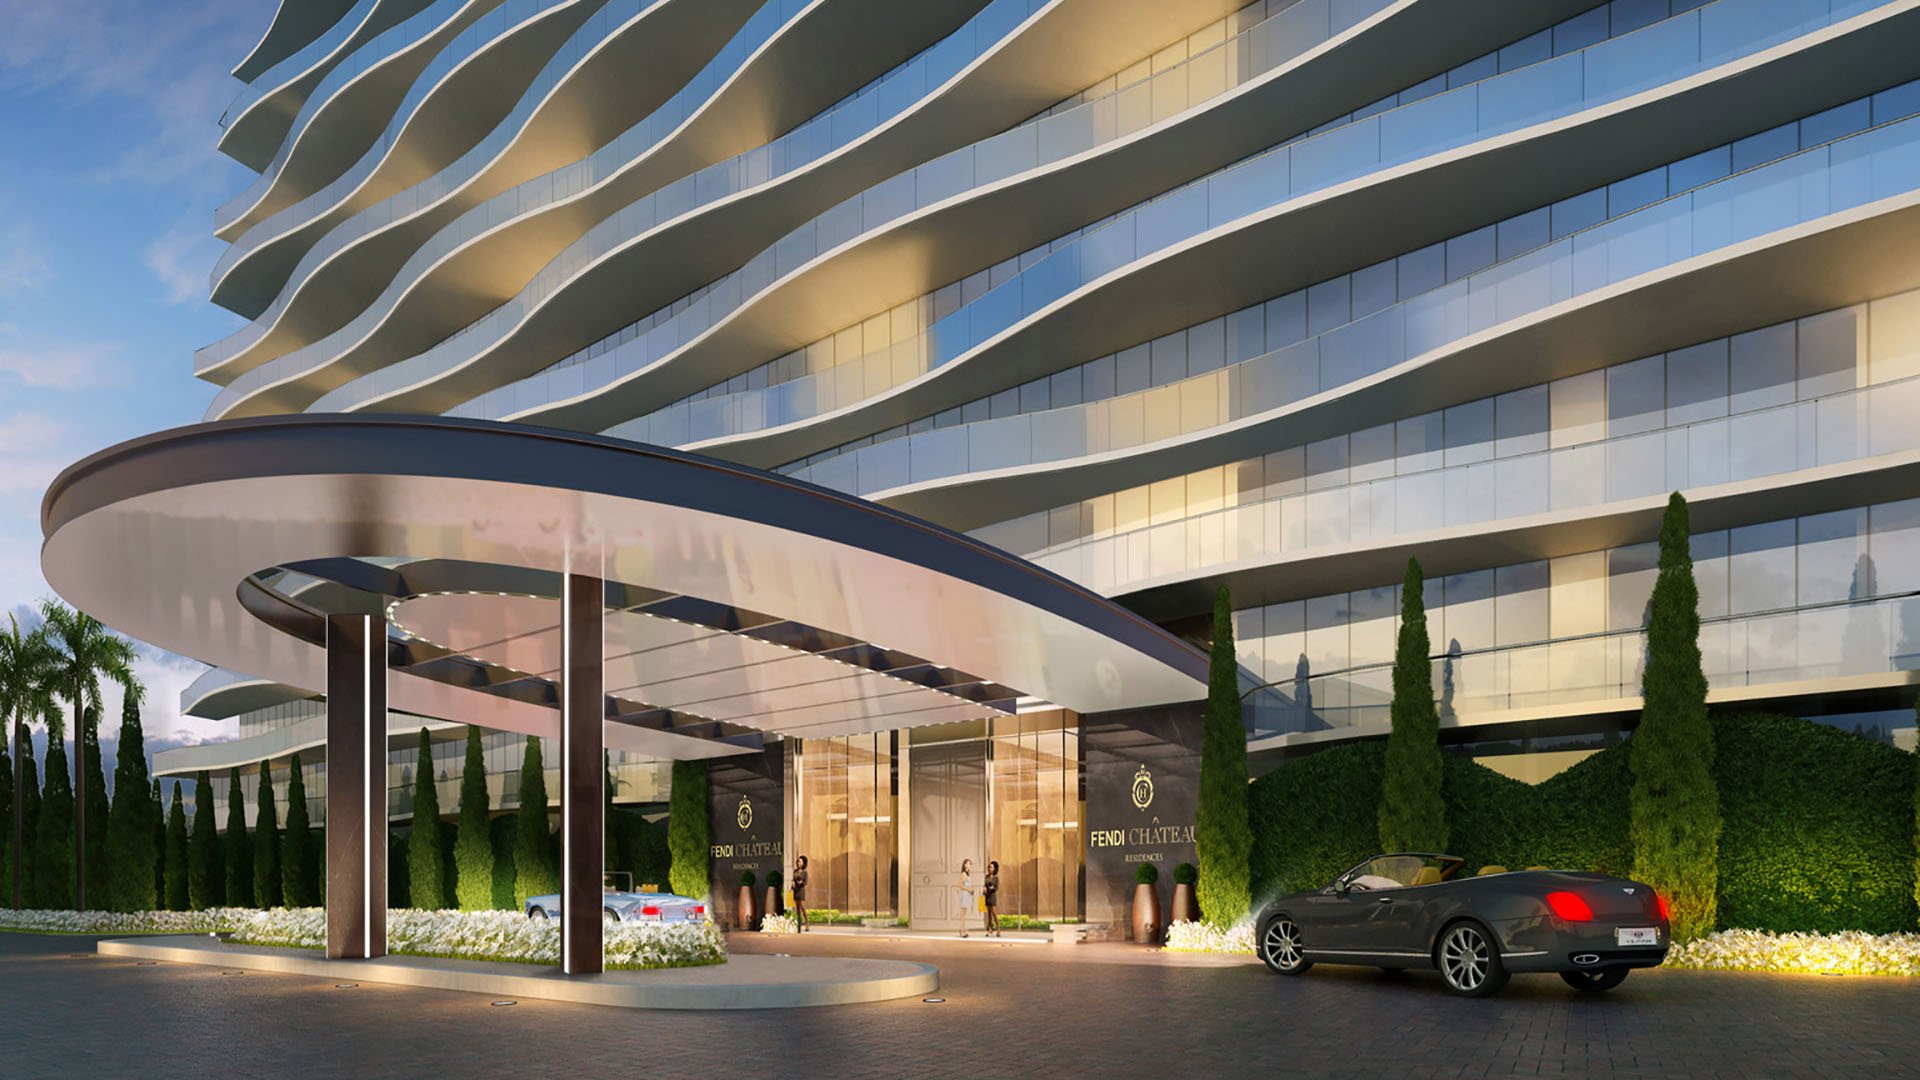
For an acquisition involving Fendi Château Residences Surfside, the prudent approach is to settle the signing route before relying on a travel calendar. Ask counsel which documents the principal must sign, which an authorized agent may sign, and whether the proposed authority will be accepted for the transaction.
Internal family-office approval is no substitute for that review. Keep the approved authority documents accessible to the closing team, and designate a contact who can resolve questions promptly. An agent’s practical availability matters only after the legal scope of the appointment is clear.
In specified regulated Singapore contexts, customer-due-diligence and transaction records generally must be retained for at least five years after the relevant relationship ends or the transaction is completed. The triggering event matters: the period is not necessarily measured from the date a file was created.
That baseline is not a complete retention schedule for a Surfside residence. Property, tax, corporate, insurance, and litigation files require their own review. Ask the appropriate advisers to define retention periods, preservation holds, and any need to keep originals by document category. Do not apply a five-year deletion rule to the entire household archive.
Relevant Singapore recordkeeping provisions permit originals or copies, including electronic or microfilm records, provided they remain admissible as evidence in Singapore courts. That permission is not a promise that any scan will satisfy every closing, tax, or evidentiary requirement.
As a practical control, use a permissioned repository with a clear index, version history, and named custodian. Separate executed documents from drafts. Where an adviser holds underlying records, agree on retrieval access and retention responsibilities in writing rather than assuming outsourced custody guarantees availability.
For a household planning its operations around Ocean House Surfside, vendor governance can be designed independently of any project-specific services. The family office should decide who may instruct vendors, approve changes, authorize access, and confirm satisfactory completion.
A recommended vendor file includes the contracting party, scope, pricing basis, payment milestones, insurance documentation where relevant, and an escalation contact. Provide only the information and access needed for the assignment. Household-service access should not imply access to ownership records or banking credentials.
For payments, consider requiring someone other than the requester to verify new or changed bank details through a previously established contact channel. Match invoices to approved work and retain the approval trail. These are operating safeguards, not statutory procedures established by the regulatory rules discussed above.
Define an emergency route as well. A local representative may need limited discretion for urgent work, but the permitted scope, notification expectations, and follow-up review should be agreed in advance. Convenience is strongest when its boundaries are clear.
The final operating document should be a concise handover: current signers, approval limits, adviser contacts, record locations, outstanding commitments, and escalation responsibilities. Revisit it after material ownership or personnel changes and before an extended absence.
A two-city life becomes more comfortable when authority is explicit and information remains retrievable. The family can focus on the residence while the office maintains a disciplined distinction between what is legally required and what is operationally wise.
Explore South Florida residences for your two-city life with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNot by itself. Internal spending approval and legal authority to bind a purchaser or seller are separate matters that should be confirmed before closing.
No. Singapore incorporation, a regulated financial-institution relationship, and a resident employee contact were terms of a proposed framework, not established universal requirements.
The relevant banks and regulated financial institutions carry those obligations. They should not be described as automatically imposing identical duties on every family office.
No. The institutional controls include regular account reviews, customer and beneficial-owner identification, and suspicious-transaction monitoring and reporting.
Within the relevant Singapore family-office schemes, notification is required when additions or replacements change material information supplied at application.
Yes, through a power of attorney specifying the powers granted. Counsel should confirm that the instrument is appropriate and acceptable for the transaction.
Execution guidance calls for two subscribing witnesses and proper notarization. Counsel should confirm execution and acceptance requirements with the title company and any lender, especially for an overseas signatory.
No. The five-year baseline applies in specified regulated Singapore contexts, while property, tax, corporate, insurance, and litigation records need separate retention review.
Relevant provisions permit electronic records and other copies if they remain admissible as evidence in Singapore courts. This does not establish that every scan satisfies every transaction requirement.
No. Separate approvals, restricted access, independent verification of changed banking details, and documented payment trails are recommended operating safeguards.