A practical documentation framework for estates retaining or transferring a South Florida residence, with attention to debt, beneficial ownership, personal and investment use, and coordinated adviser review.
For a family deciding whether an estate should retain or transfer a South Florida residence, the most valuable preparation is a file that clearly explains ownership, financing, and use. The objective is not simply to collect paperwork, but to give advisers a consistent account of what the estate holds, what would change, and which questions require separate legal or tax analysis.
Whether the residence is in Brickell, Miami Beach, Fort Lauderdale, or West Palm Beach, begin with a one-page decision brief. Identify the property, current title holder, proposed recipient, ownership percentage involved, existing debt, and intended use. Distinguish retaining the residence from transferring it. A lifetime planning transfer should not be treated as interchangeable with an estate distribution.
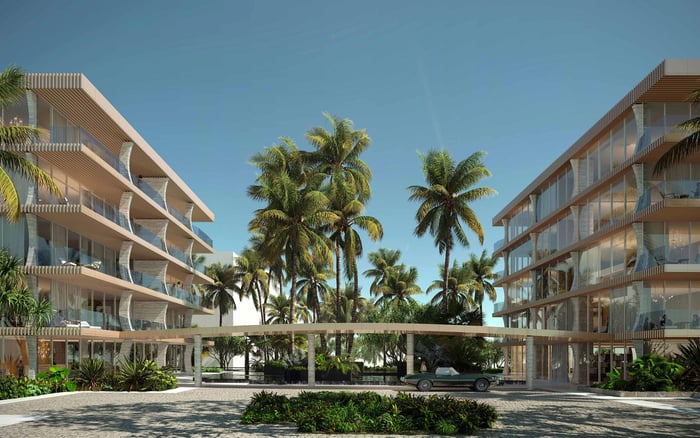
For a residence at Una Residences Brickell, as for any other South Florida property, the address identifies the asset. The deed, financing records, and governing documents explain the transaction.
Florida documentary stamp tax applies to documents transferring an interest in Florida real property. A document can be taxable even when signed or delivered outside Florida. The place of execution is therefore no substitute for reviewing the interest conveyed and the consideration involved.
Keep the existing deed, proposed deed, ownership schedule, and any agreement describing the exchange. State the percentage being transferred and the consideration attributable to that interest. Looking only at the property's total value can obscure the transaction under review.
Debt deserves its own tab. An outstanding mortgage, lien, or other encumbrance can constitute consideration, whether or not the recipient assumes the obligation. A transfer with no cash payment should not automatically be labeled tax-free. Retain a current mortgage balance or payoff statement, and ask advisers to document how the debt affects the proposed conveyance.
Keep property-tax bills and special-assessment records separate from borrowing documents. Current ad valorem property taxes and special assessments do not constitute consideration for documentary stamp tax on deeds. Their presence in the file should not lead to their being grouped with mortgage debt.
For Broward and Palm Beach properties, the documentary stamp tax rate on taxable real-property transfers is $0.70 per $100, or fraction thereof, of consideration. Miami-Dade County's rate is $0.60 per $100, or fraction thereof, with an additional county surtax potentially applying to property other than a single-family residence.
These distinctions make property classification and county location important review points. For a Miami Beach residence, including a holding at The Perigon Miami Beach, ask the closing team to explain the applicable treatment rather than carry over assumptions from another property.
For waterfront ownership planning, retain a written calculation showing the consideration used, the interest conveyed, and the treatment of any potentially applicable surtax. This makes the file easier to follow; it does not replace transaction-specific advice. Price, prestige, and family intent do not, by themselves, settle documentary stamp treatment.
A trust transfer requires more than a trust's name on a proposed deed. Preserve the relevant trust terms and a clear account of beneficial ownership before and after the conveyance. Ask counsel to identify whether beneficial interests remain unchanged or move to another person.
Do not assume that transferring a residence into a trust creates a blanket documentary stamp exemption. Document the retained beneficial interest precisely and obtain advice on the actual arrangement.
Homestead analysis belongs beside, not inside, the documentary stamp calculation. Section 732.4017 distinguishes qualifying lifetime transfers of homestead, including transfers in trust, from testamentary devises. A conclusion about transfer tax does not establish the homestead result, or vice versa.
Ask counsel for separate written conclusions on these issues. Keep each conclusion with the documents it addresses so a later reader can understand its scope and assumptions.
Interest tracing should begin with a factual reconstruction of borrowing and expenditure. Retain loan agreements, refinancing statements, disbursement records, account statements, and invoices showing where proceeds went. If funds moved through several accounts, prepare a dated sequence connecting each movement to its supporting record.
Distinguish acquisition spending, improvements, personal expenditures, and other uses where the records permit. Do not fill gaps with recollection presented as certainty. Mark unresolved entries for adviser review instead.
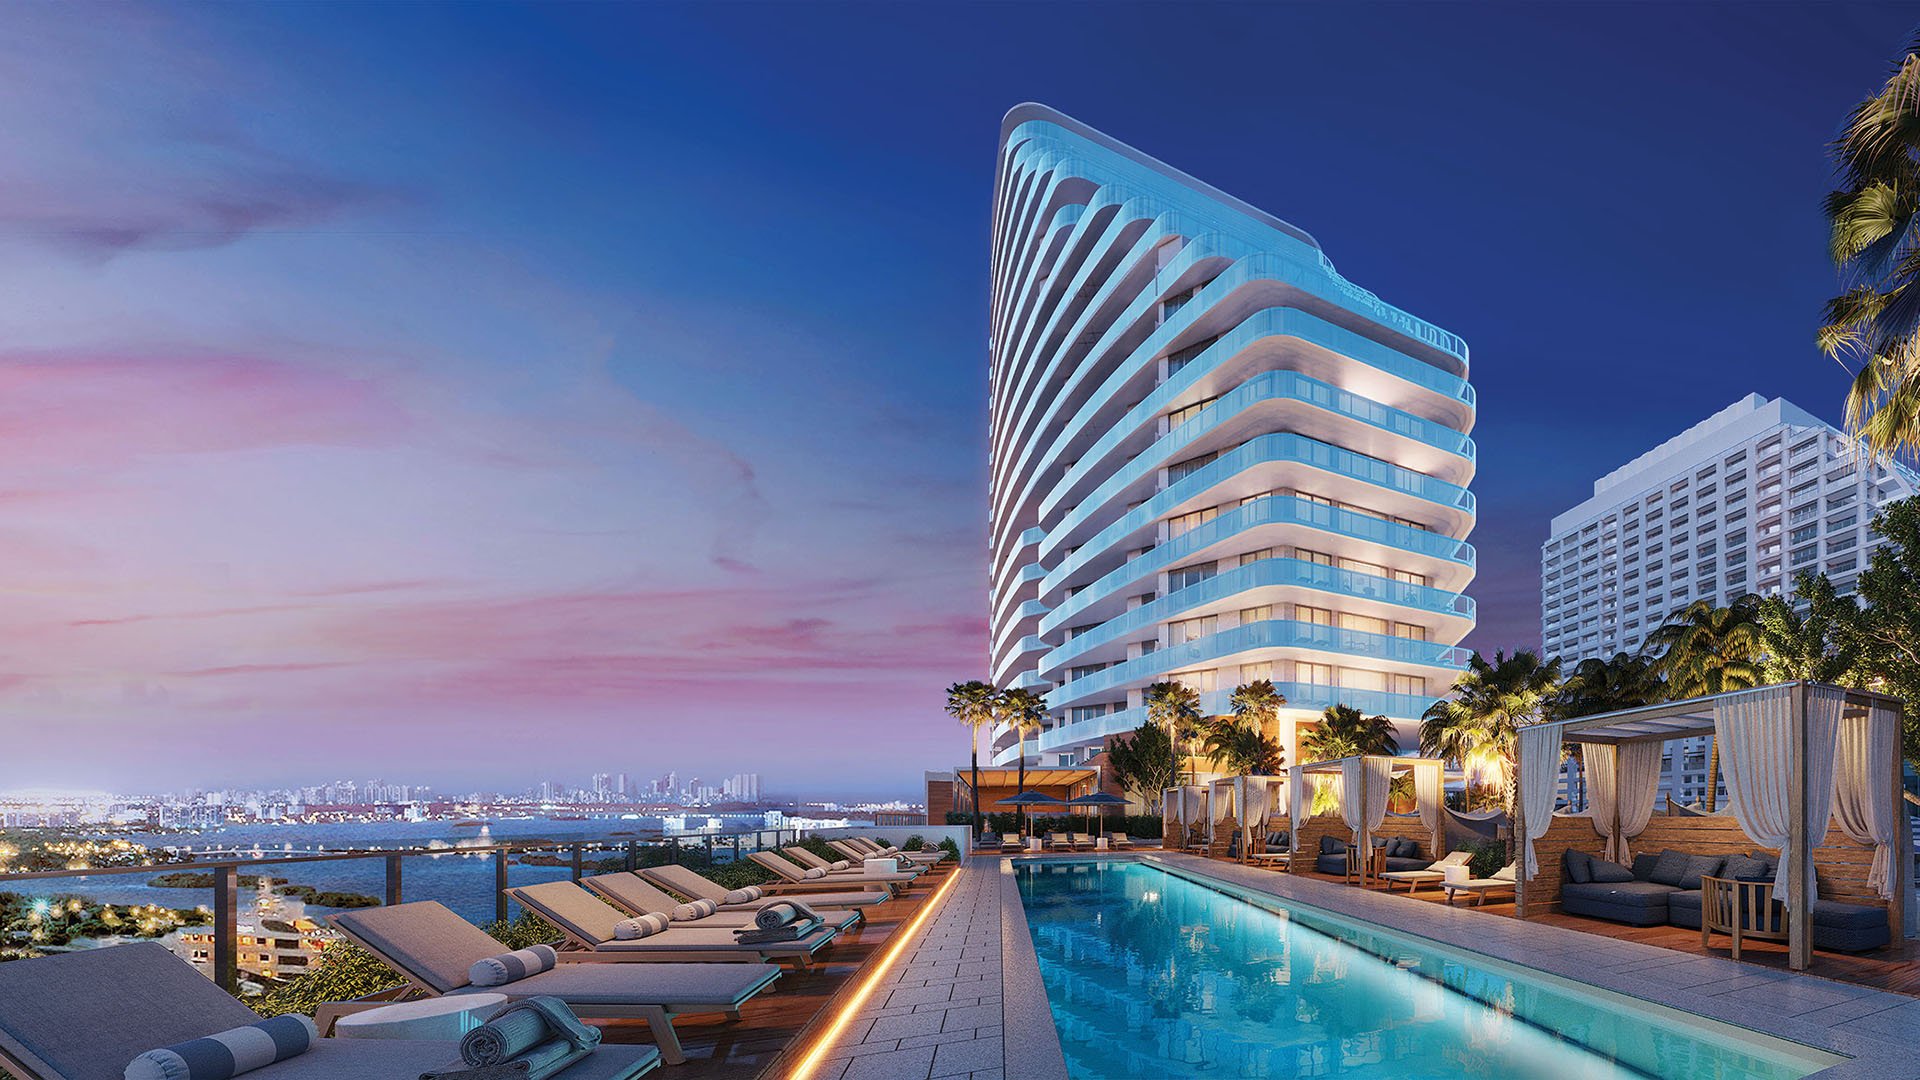
These records do not, by themselves, establish whether interest is deductible or how it should be allocated. That determination requires separate tax advice. For a family retaining a Fort Lauderdale residence, such as Four Seasons Hotel & Private Residences Fort Lauderdale, the disciplined approach is to preserve the borrowing history without presuming a tax outcome from the property's location or intended role.
When a residence has both personal and investment uses, give advisers a factual timeline rather than a single label. A useful working file can include occupancy calendars, rental agreements, receipts, expense invoices, and notes identifying changes in intended use. These are organizational recommendations, not a statement of a particular tax allocation formula.
For an estate retaining a West Palm Beach residence, including Alba West Palm Beach, distinguish documented activity from future plans. An intention to rent later is not a record of actual occupancy or rental activity.
Keep purchase and improvement documents available for separate review of basis, valuation, and depreciation questions. Do not infer an inherited-basis result, a required valuation date, an allowable deduction, or a retention period from this framework. Ask the tax adviser to identify the applicable treatment and recordkeeping requirements in writing.
Designate one person to maintain a shared index and circulate the same version of the transaction brief. Assign ownership, trust, and homestead questions to counsel; tax analysis to the tax adviser; and recording and payment mechanics to the closing team. Document unresolved questions before execution.
Any party to a taxable document may be liable for documentary stamp tax, regardless of who contractually agrees to pay it. Confirm the payment arrangement, but do not mistake it for a limit on potential liability.
For a recorded taxable document, documentary stamp tax is paid to the county clerk of court or recording official. Preserve the recorded instrument, payment evidence, final calculations, and adviser conclusions together. If the estate retains the residence instead, keep the decision brief and update the financing and use records as circumstances change.
Explore South Florida residences with MILLION as you coordinate the ownership plan with your advisers.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationYes. A document transferring an interest in Florida real property can be taxable regardless of where it is signed or delivered.
No. Outstanding mortgages, liens, or other encumbrances can constitute consideration, whether or not the recipient assumes the debt.
Retain a current mortgage balance or payoff statement so advisers can evaluate debt included in transfer-tax consideration.
The review should address the interest conveyed and the consideration attributable to it, rather than only the property's total value.
The rate on taxable real-property transfers is $0.70 per $100, or fraction thereof, of consideration.
The rate is $0.60 per $100, or fraction thereof, of consideration. An additional county surtax may apply to property other than a single-family residence.
Do not assume a blanket exemption for trust transfers. Preserve the deed, trust terms, and beneficial ownership records for review of the actual arrangement.
Coordinate the reviews, but keep their conclusions separate. A documentary stamp determination does not establish the homestead result.
No. They provide factual material for adviser review; deductibility, allocation, basis, and depreciation require separate tax analysis.
Keep the recorded instrument, documentary stamp payment evidence, final calculations, and adviser conclusions together. A contractual payment allocation does not necessarily eliminate another party's tax liability.