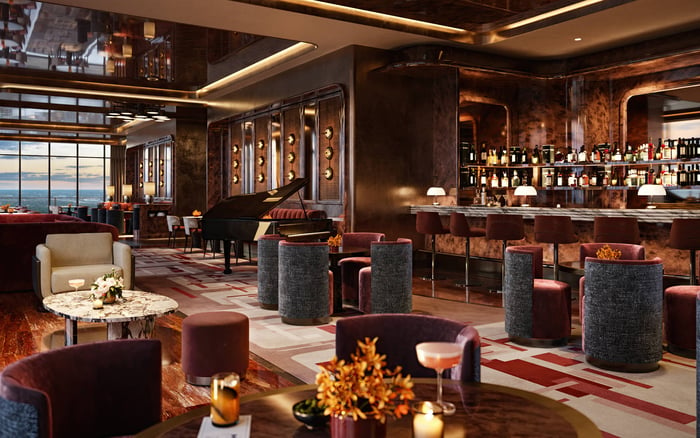
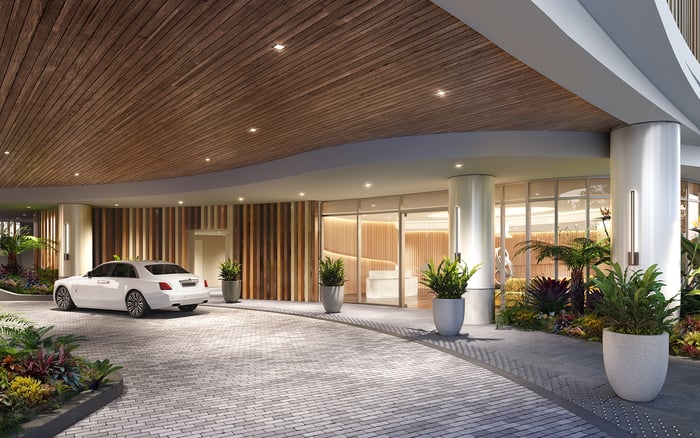
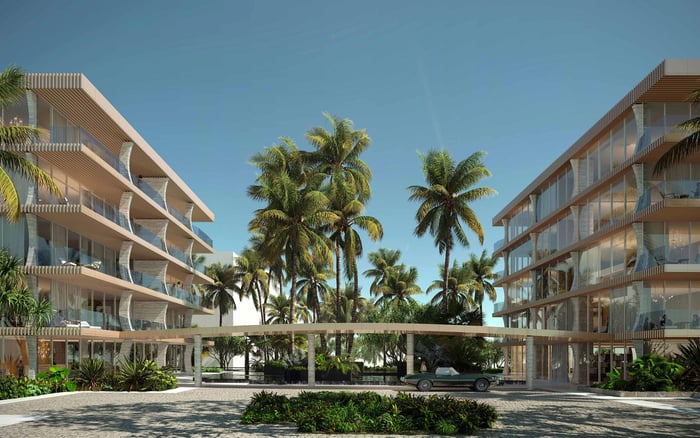
A discreet ownership-readiness framework for Alba buyers, separating advertised building services from private household responsibilities, with practical checks for payroll vendors, screening decisions, and credential renewals.
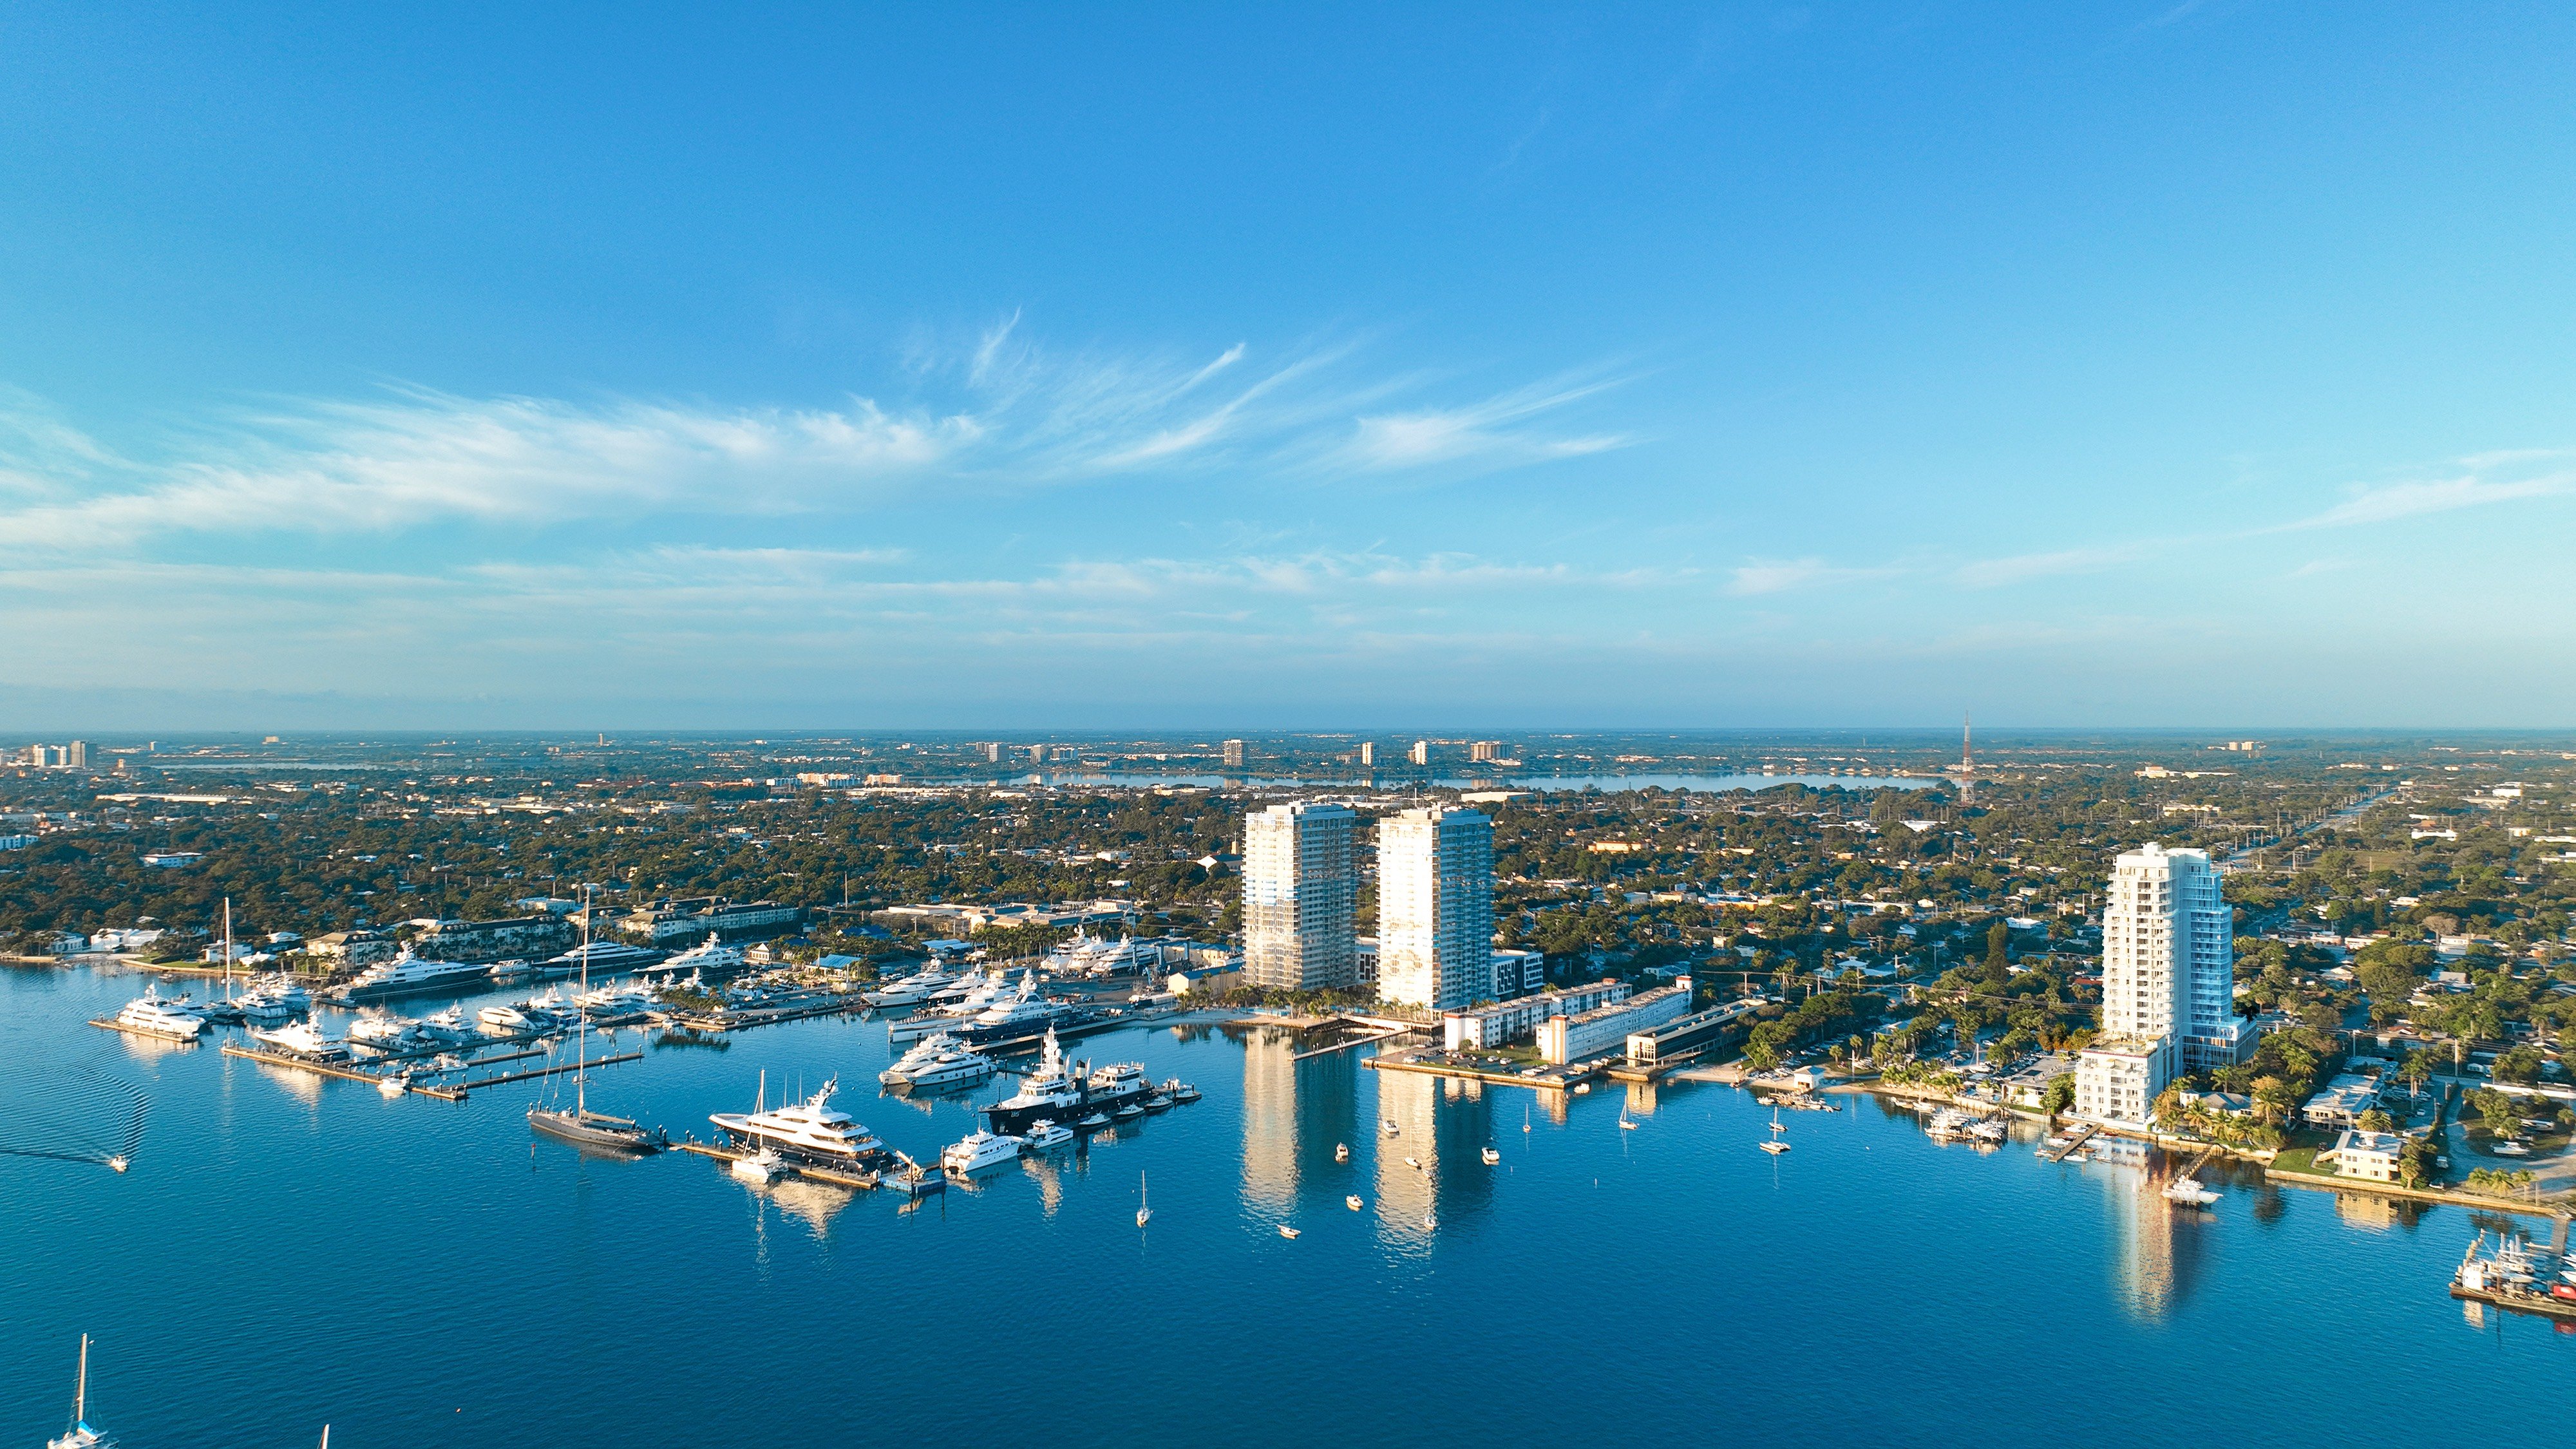
At Alba West Palm Beach, the advertised service offering includes on-site security and surveillance, valet services, a staffed lobby, on-site property management, and concierge services. For a buyer planning a carefully managed household, these features raise a practical question: where does building service end and private household responsibility begin?
Alba’s advertised amenities span more than 25,000 square feet and include two resort-style pools with cabanas, five private plunge pools, and a private dock. The indoor offering includes steam and sauna rooms, a Technogym fitness center, and temperature-controlled wine storage. These are advertised features-not assurances that every service is currently operational or that privately hired staff fall within building oversight.
An ownership-readiness audit should address three distinct matters: who employs each worker, who administers the household’s obligations, and who monitors the evidence needed for each assigned role. The recommendations below are owner-side controls, not statements of Alba policy.
Before selecting a payroll vendor, create a roster of the nanny, housekeeper, chauffeur, caregiver, and any other privately engaged personnel. Record who hires, directs, schedules, and pays each person. Keep building employees and outside service-provider personnel in separate categories while assessing the employment relationships.
For federal household-tax purposes, classification turns on the working arrangement. A resident who controls both what work is performed and how it is performed may have a household employee, regardless of the label used in an agreement. Building personnel and outside service-provider personnel should not automatically be treated as the resident’s employees.
Ask a qualified tax adviser to review uncertain arrangements before payroll setup. The resulting record should identify the proposed employer, the classification rationale, the payment process, and the person responsible for resolving questions. Neither a service invoice nor a worker’s preferred description should substitute for that assessment.
For buyers also considering Forté on Flagler West Palm Beach, the same distinction offers a useful due-diligence question-not grounds to assume that either property administers household employment.
A polished interface matters less than an explicit division of responsibilities. Ask each prospective provider to define, in writing, its role in tax calculations, filings, W-2 preparation, Schedule H support, and owner access to records. Distinguish a vendor that prepares information from one engaged to submit a filing.
The proposed service agreement should answer practical questions: Who approves wages and adjustments? Who reconciles payments? Who handles corrections? What remains available if the relationship ends? Request a sample reporting package and a clear explanation of how the owner or adviser retrieves historical records.
For a household coordinated by a family office or personal assistant, consider assigning one payroll approver and a separate reviewer. Document the handoff to the tax preparer rather than assuming everyone works from the same records or calendar.
Vendor selection is a scope-of-service exercise, not a recommendation of a particular firm. Confirm service coverage and engagement terms directly; do not infer an Alba endorsement or preferred-provider relationship.
For 2026, paying one household employee $3,000 or more in cash wages generally triggers Social Security and Medicare taxes, subject to applicable exceptions. The corresponding threshold was $2,800 in 2025. The audit should therefore test the vendor’s tax-year settings, not simply confirm that an account exists.
Do not treat the $3,000 figure as a universal exemption from household employment taxes. Schedule H reports those taxes when cash wages are subject to Social Security, Medicare, or federal unemployment tax, or when federal income tax is withheld. Household employers need an Employer Identification Number to file Schedule H.
Federal income-tax withholding is generally not mandatory for household employees. It may be arranged when the employee requests it and the employer agrees. Have the vendor document that choice and coordinate it with the household’s tax adviser.
The deadline for filing Schedule H with the employer’s 2026 federal income-tax return is April 15, 2027. An employer not required to file a federal income-tax return can file Schedule H separately. Add the applicable filing responsibilities and preparer handoff to the household calendar.
Start with the role, not a generic screening package. Describe the proposed duties, access, and responsibilities, then ask qualified counsel and a screening provider to help define an appropriate review. The objective is a documented hiring process-not an unsupported promise that a check eliminates risk.
Ask prospective screening vendors how identity is matched, what the proposed review covers, how results are explained, and who handles disputed information. Ask counsel to establish any applicable consent, notice, and decision procedures before acting on screening results. This is not a complete legal compliance checklist.
Keep payroll administration, screening review, and building access as separate workstreams. Ask management for current written access procedures and the information it requires. Do not assume that advertised security means management screens privately hired personnel or makes the household’s employment decisions.
When comparing Mr. C Residences West Palm Beach, bring the same questions to the ownership discussion without presuming identical staffing or access arrangements.
A proposed credential register should record the worker, assigned role, relevant credential, expiration date where applicable, verification date, evidence location, and responsible reviewer. Include only items relevant to the duties and confirmed requirements. Not every document expires, and not every role calls for the same evidence.
Consider 90-, 60-, and 30-day renewal reminders. Give each reminder a named recipient and a next action: request evidence, review the renewal, or escalate an unresolved item. These intervals are suggested household controls, not Alba requirements.
Agree in advance who evaluates missing evidence and whether an affected assignment should change while the issue is resolved. Coordinate any building-access question with management. Keep this register distinct from employment-eligibility procedures, which require separate professional guidance rather than automatic treatment as ordinary credential renewals.
Before the household begins operating, assemble a compact readiness file: the employment roster, payroll engagement, tax calendar, screening decision process, credential register, and management’s current access instructions. Assign each unresolved item an accountable person and a target resolution date.
The final review should test continuity. Can the owner retrieve payroll records without the usual assistant? Does a renewal reminder reach someone empowered to respond? Is there a clear contact for an access question? The goal is not more administration, but fewer ambiguous responsibilities behind an otherwise effortless residence.
For a considered approach to West Palm Beach ownership, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationAlba advertises on-site security and surveillance, valet services, a staffed lobby, on-site property management, and concierge services. These descriptions do not establish private household staffing responsibilities.
Do not assume that advertised security includes screening privately hired personnel. Ask management for current written procedures and define a separate household hiring process.
A worker may be a household employee when the resident controls both what work is performed and how it is performed. Classification depends on the arrangement, not simply the worker’s title.
No. Building personnel and outside service-provider personnel require a separate assessment of the employment relationship.
Request written responsibilities for tax calculations, filings, W-2 preparation, Schedule H support, corrections, and access to records. Clarify which tasks remain with the owner or tax adviser.
Paying one household employee $3,000 or more in cash wages generally triggers these taxes for 2026, subject to applicable exceptions. The corresponding 2025 threshold was $2,800.
It is generally not mandatory. Withholding may be arranged if the employee requests it and the employer agrees.
Household employers need an Employer Identification Number. The stated deadline for filing Schedule H with the 2026 federal income-tax return is April 15, 2027; employers not required to file an income-tax return can file it separately.
Define the role and ask qualified counsel and a screening provider to establish an appropriate review and applicable procedures. Treat screening as a documented hiring decision rather than a guarantee against risk.
No, these are suggested owner-side controls. A role-specific register should identify relevant credentials, applicable expiration dates, a reviewer, and an escalation process.