Moving a collection from Aspen to Edgewater calls for more than careful packing. A discreet plan should connect documented condition, conditioned storage, verified backup-power scope, and insurance that follows every transfer.
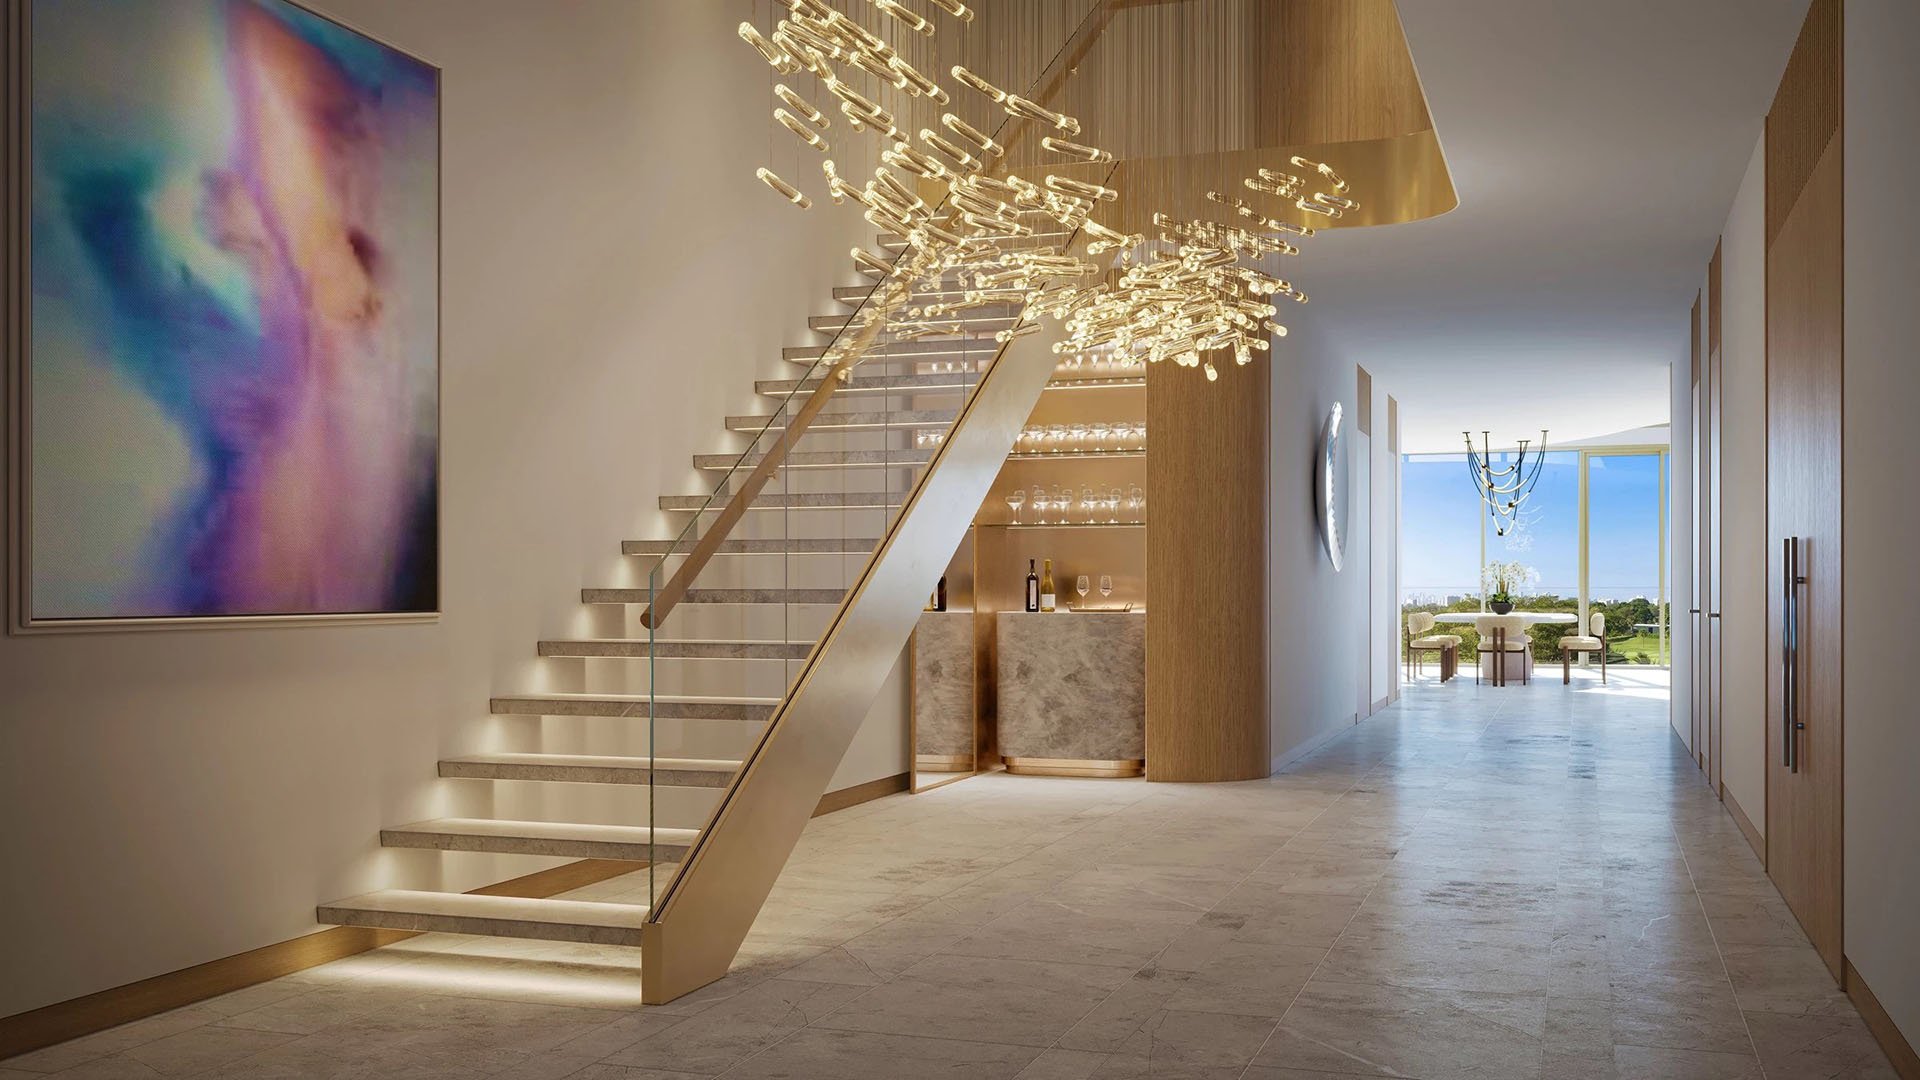
For an Aspen owner establishing an Edgewater residence, the most consequential moving decisions may concern what hangs on the walls and rests in the cellar. Art and wine warrant a separate plan, not an appendix to the household shipment. The objective is continuity: documented condition, appropriate environments, accountable handling, and insurance that follows every stage.
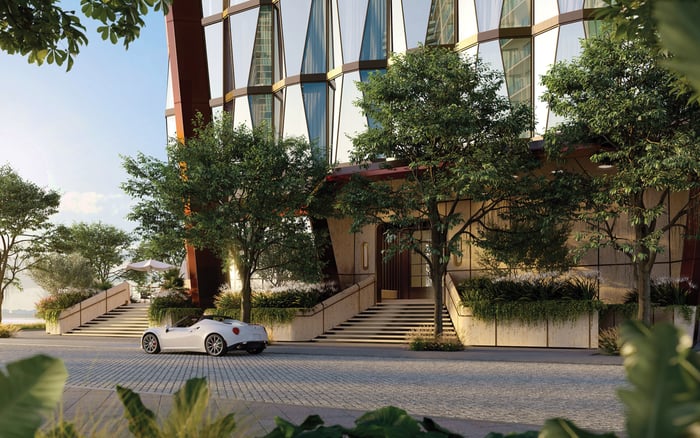
Begin by deciding what belongs in the residence, what should remain in Aspen, and what would benefit from professional storage. Let that division inform the property search. When considering Aria Reserve Miami, for example, bring a collection brief alongside the interior-design brief. Ask about delivery access, intended storage locations, and the systems serving the proposed installation. Confirm every collection-related capability in writing rather than inferring it from the address.
Commission a professional fine-art handler to photograph each work, record its condition, and specify packing requirements before departure. Preserve a chain of custody through transport, temporary storage, delivery, and installation. The collection file should identify both the object and the party responsible for it at every handoff.
For wine, create a bottle-level inventory with identifying details, quantities, values, and intended destinations. This is a planning recommendation, not a substitute for the insurer's documentation requirements. Keep digital copies of inventories, condition photographs, appraisals, and transport agreements accessible to the owner and designated representatives.
Obtain current appraisals before the move, then ask the insurer which valuation methods, appraisal dates, and reappraisal intervals it accepts. Have applicable consignment agreements and insurance certificates in place before transport. A mover's reference to declared value or full-value protection should prompt a review of written valuation and liability terms-not an assumption of comprehensive insurance.
A storage proposal should explain how the environment is managed. Request written temperature and humidity limits appropriate to the collection, environmental logs, monitoring arrangements, outage-recovery procedures, and backup-cooling provisions. Have the relevant specialists assess whether those conditions suit the works and bottles being stored. Avoid imposing a generic specification on every object.
Location within the facility matters as much as its description. Avoid storing artwork below street level, particularly where flooding, humidity, or restricted ventilation are concerns. Keep stored works at least 20 centimeters, approximately 8 inches, above the floor to reduce exposure to water, dust, and accidental impact. That clearance is a precaution, not flood protection.
Terms such as hurricane-safe, climate-controlled, and monitored should prompt questions, not settle them. Ask what each promise means contractually, who receives alerts, and what happens when equipment fails. Review liability exclusions and responsibility for collection damage during a prolonged interruption.
Apply the same discipline to a residence under consideration at EDITION Edgewater. Request confirmation of any proposed private storage arrangement and its operating conditions. Do not equate residential air-conditioning with a collection-specific storage commitment.
Storm and flood events can interrupt power, making loss of cooling a concern for collections even without direct water exposure. The question is not simply whether a building has a generator, but whether the equipment protecting your particular collection remains powered.
Ask management and the appropriate technical professionals to identify the backed-up circuits serving wine cooling, HVAC, dehumidification, security, and environmental monitoring. Request written clarification of operating limits, maintenance arrangements, outage procedures, and any distinction between common-area service and private-unit entitlement. Ask how alerts will reach a responsible person if normal communications are disrupted.
For a buyer evaluating Villa Miami, these are due-diligence questions, not statements about installed systems or promised service. Apply the same standard to any Edgewater shortlist.
Do not improvise a portable-generator solution for a condominium. Generators must operate outside inhabited structures in appropriately ventilated locations away from those structures, never inside a garage or near windows or doors. Follow manufacturer instructions and obtain building-specific professional guidance rather than assuming a balcony is suitable.
Do not assume a homeowners policy adequately addresses art, wine, or other collectibles. Ask an insurance adviser whether individual items or collections should be scheduled and how values will be established. Review breakage provisions and the treatment of pairs or collections, where damage to one component may raise a separate valuation question.
Map coverage to four distinct stages: the Aspen-to-Florida journey, temporary storage, delivery and installation, and later transfers between the residence and a storage facility. Ask the adviser to identify the applicable policy, limits, exclusions, and responsible insured party at each stage. Align effective dates with actual custody changes, including any delayed delivery.
Wine spoilage requires its own written answer. Ask specifically about damage associated with utility interruption and climate-control equipment breakdown. Neither a general reference to valuables coverage nor a mover's protection label establishes that these events are insured. The policy language governs.
Keep the insurance schedule synchronized with the physical inventory. Purchases, sales, and movements between homes should trigger a review of both records and coverage arrangements.
Before dispatch, arrange a coordinated review of crate dimensions, freight-elevator access, delivery appointments, handling permissions, and the route to installation. These are practical checks, not assumed building features. Confirm that the intended storage or display environment is ready before releasing the collection for delivery.
On arrival, compare condition with the departure record and document custody through installation. Designate who may accept delivery, approve placement, or raise a concern when the owner is elsewhere.
For storm planning, agree in advance on a decision process for any relocation to storage, subject to safe access and professional advice. Identify who has authority, which handler would be contacted, and how insurance would apply. Plan for disruption rather than immediate restoration, without treating any particular outage duration as predictable.
The final deliverable should be a concise operating file: inventory, condition records, accepted valuations, insurance documents, environmental requirements, confirmed backup-power scope, and contact responsibilities. Each document should answer a practical question when the owner is away.
A successful move is more than the safe arrival of crates. It is the ability to enjoy a collection in Edgewater with clear responsibilities for its continuing care. The residence, storage facility, handler, and insurance adviser should all be working from the same instructions before the first shipment leaves Aspen.
For a collection-conscious approach to your Edgewater property search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationHave a professional fine-art handler photograph each work, record its condition, and identify packing requirements. Document custody through transport, storage, delivery, and installation.
Obtain current appraisals and ask the insurer which valuation methods, appraisal dates, and reappraisal intervals it requires.
Request written temperature and humidity limits, environmental logs, monitoring arrangements, outage-recovery procedures, backup-cooling provisions, and liability exclusions.
Avoid below-street-level art storage, particularly where flooding, humidity, or restricted ventilation are concerns. Evaluate the actual location rather than relying on a facility's marketing description.
Keep stored artwork at least 20 centimeters, approximately 8 inches, above the floor to reduce exposure to water, dust, and accidental impact. This precaution does not establish flood protection.
Do not assume it does. Obtain written confirmation of the specific backed-up circuits and any private-unit entitlement.
Do not assume standard homeowners coverage is adequate. Ask about scheduled items, valuation, transit, storage, breakage, and the treatment of pairs or collections.
No coverage should be assumed. Ask the adviser to confirm policy treatment of utility interruption and climate-control equipment breakdown in writing.
Confirm coverage for the Aspen-to-Florida journey, temporary storage, delivery and installation, and subsequent transfers between the residence and storage.
Designate who receives environmental alerts, authorizes action, and contacts handlers or insurers. Establish any pre-storm relocation process in advance, subject to safe access and professional advice.