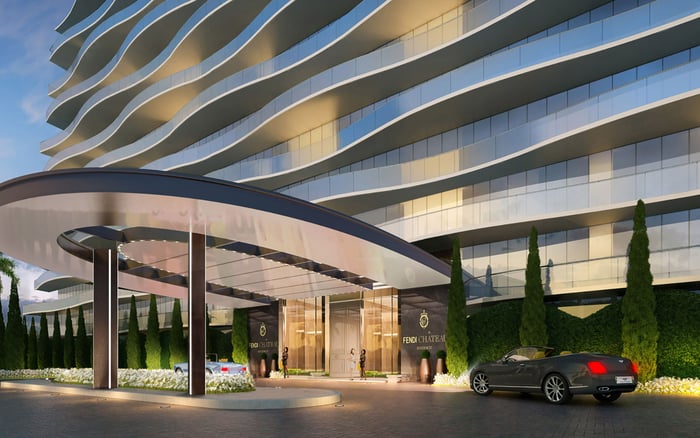
For Vancouver-based buyers, a Bal Harbour second home calls for more than a considered property selection. Coordinating cross-border tax advice, deed vesting, trust documents and coastal insurance can help preserve both family flexibility and succession clarity.
A second home in Bal Harbour should make life feel less complicated. For a Vancouver-based family, however, the most consequential decisions may concern neither the floor plan nor the view. They concern who owns the residence, who can manage it during incapacity, and what happens when ownership passes to the next generation.
Whether the search centers on Oceana Bal Harbour or another residence, the ownership plan deserves attention alongside the purchase. Being based in Vancouver does not establish citizenship, U.S. estate-tax domicile, marital status or future residency intentions. Those details should shape the advice before a deed is prepared.
The objective is coordination, not a universally preferred structure. Canadian and Florida counsel, cross-border tax advisers and an insurance professional should review the same proposed ownership arrangement rather than address separate pieces in isolation.
A Canadian resident who is neither a U.S. citizen nor a U.S. estate-tax resident can still face U.S. estate tax on Florida real estate and other U.S.-situated assets. Holding a residence for holidays does not, by itself, remove that exposure.
For a nonresident noncitizen, U.S.-situated assets exceeding US$60,000 generally trigger an estate-tax filing requirement. That figure is not a definitive tax-free allowance for a Canadian owner. An estate may need to file Form 706-NA even when Canada-U.S. treaty relief reduces or eliminates the tax payable.
Treaty relief may provide a prorated estate-tax credit, generally reflecting U.S.-situated assets as a proportion of worldwide assets. The analysis therefore extends beyond the Florida property's value. Ask advisers to consider the broader estate rather than assess the residence in isolation.
Canada generally treats a deceased Canadian resident as having disposed of capital property at fair market value, potentially producing capital-gains tax rather than a traditional estate tax. The planning question is therefore two-sided: how U.S. estate-tax exposure and Canadian deemed-disposition consequences interact for this family.
A revocable trust can support incapacity management and avoid probate for assets properly transferred into it. Those are meaningful administrative benefits, but they are not automatic estate-tax protection. Revocable-trust ownership does not automatically exclude the property from the settlor's taxable estate.
Florida law recognizes certain non-testamentary trusts created under another jurisdiction's law, subject to validity and formality requirements. That does not mean an existing Canadian trust is ready to receive a Florida residence without review.
Before selecting a structure, ask counsel to examine the trust's governing law, execution formalities, trustee powers and intended succession arrangements. The review should distinguish recognition of the trust from the separate question of its tax consequences.
For a buyer considering Rivage Bal Harbour, this is a useful point to pause before finalizing ownership instructions. A familiar family trust may be the starting point for advice, but familiarity alone is not a reason to place it on the deed.
Deed vesting concerns how legal ownership is recorded. The wording should implement the approved plan, not become a last-minute administrative choice. Ask Florida counsel to confirm the appropriate named owner, any trustee designation and the language required for the intended arrangement.
Then review the deed and succession documents together. A trust designed to manage the residence cannot deliver its intended probate-avoidance benefit merely by existing; the asset must be properly transferred into it.
A practical document review should address three questions:
Does the proposed deed match the ownership and tax plan approved by both advisory teams?
Would a separate Florida will be appropriate, and how would it coordinate with existing Canadian testamentary documents?
Will the relevant Florida parties accept the owner's Canadian power of attorney, or should additional documentation be considered?
These are questions for counsel, not reasons to assume that every buyer needs the same documents. Ask advisers to document who is expected to act during incapacity and after death, and to identify any inconsistencies before closing. Keep the resulting documents accessible to those expected to use them.
A second-home plan should not assume that homestead benefits arise automatically. If the Bal Harbour residence later becomes a permanent home, Florida homestead rules can affect taxation, creditor protection and succession rights involving a spouse or minor children.
That change deserves a fresh legal review, particularly where a trust already holds title. Transferring qualifying homestead property into a revocable trust may require special language in both the deed and trust agreement to preserve the homestead tax exemption.
Trust ownership can also raise uncertainty around homestead creditor protection. Tax treatment, creditor protection and inheritance restrictions are not interchangeable. Each needs attention in the context of the family's circumstances.
A shift from seasonal use to permanent residence should therefore prompt advisers to revisit the plan, not simply update a mailing address.
Coastal insurance deserves the same property-specific discipline as title planning. Bal Harbour offers address-specific Flood Insurance Rate Map determinations through its building department. County flood-zone maps and property-level inquiries offer another way to check the actual location rather than assume a neighborhood-wide designation.
Flood insurance is available to condominium unit owners as well as homeowners. An exemption from an insurer's flood-purchase requirement does not establish that flood coverage is unnecessary, nor does it resolve any separate lender requirement.
If the search extends to Surfside and Ocean House Surfside, repeat the address-specific review rather than carry conclusions over from a Bal Harbour property. A project's identity is no substitute for an insurance assessment.
Ask the insurance professional to explain proposed flood and wind coverage, applicable exclusions and any purchase requirements. Confirm how the intended ownership should be reflected in the policy documents. The adviser should review the actual deed arrangement and intended use, not an earlier assumption about either.
Before closing, bring the proposed deed, relevant trust provisions, succession documents and insurance proposal into one coordinated review. Request confirmation that the legal, tax and insurance advisers have considered the same ownership structure and family circumstances.
The most useful outcome is not the largest document file. It is clarity about ownership, authority, coverage and the decisions still requiring professional judgment. Revisit that understanding when residency intentions, family circumstances or the ownership arrangement changes.
This is a planning framework, not individualized legal, tax or insurance advice. A carefully selected residence deserves an equally considered plan for holding it and passing it on.
For a discreet approach to your Bal Harbour property search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationYes. A Canadian resident who is neither a U.S. citizen nor a U.S. estate-tax resident can still face U.S. estate tax on Florida real estate and other U.S.-situated assets.
No. For a nonresident noncitizen, U.S.-situated assets exceeding US$60,000 generally trigger an estate-tax filing requirement, not a definitive measure of tax payable.
Yes. Filing may still be required even when Canada–U.S. treaty relief reduces or eliminates the U.S. estate tax payable.
Treaty relief may provide a prorated estate-tax credit generally reflecting U.S.-situated assets as a proportion of worldwide assets. The Florida residence alone may not provide enough information for that analysis.
Canada generally treats a deceased Canadian resident as having disposed of capital property at fair market value. This can generate capital-gains tax consequences that need coordination with U.S. estate-tax planning.
No. A revocable trust can support incapacity management and avoid probate for properly transferred assets, but it does not automatically exclude the residence from the settlor's taxable estate.
Florida recognizes certain non-testamentary trusts created under another jurisdiction's law, subject to validity and formality requirements. Counsel should review the particular trust before it is used to hold the residence.
That requires individualized counsel review. Advisers should assess whether a separate Florida will is appropriate and how it would coordinate with existing Canadian documents.
No automatic qualification should be assumed. If the property later becomes a permanent residence, counsel should revisit homestead taxation, creditor protection and succession restrictions.
No. An insurer's exemption does not determine whether coverage is appropriate or whether a lender has a separate requirement; the actual address and proposed policy need review.