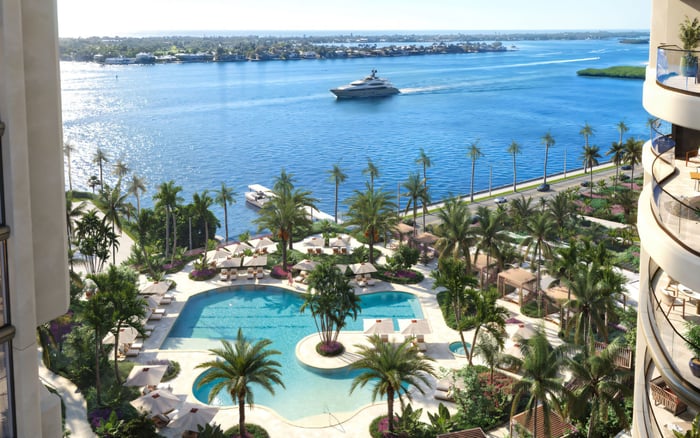
For Singapore-based families, a Palm Beach second home calls for more than a seasonal calendar. Clear family authority, property-specific guest permissions, discreet occupancy records and coordinated succession planning help protect both the experience and the ownership framework.
A Palm Beach second home should make family life less complicated. For a household whose permanent residence remains in Singapore, that ease begins with decisions rarely reflected in a floor plan: who can authorize a stay, which guests may arrive without an owner, where visit records belong and what happens when ownership passes to the next generation.
The essential distinction is between enjoying a residence and governing it. A family calendar cannot establish tax eligibility, an invitation cannot override property rules, and a succession document should not be assumed to preserve existing assessment treatment. Address these matters separately before purchase, then bring them together in a concise household operating plan.
If the search extends to West Palm Beach, a residence under consideration at Alba West Palm Beach warrants the same governance questions as any Palm Beach address. The objective is not simply an appealing setting, but a home whose documented conditions fit the family's intended use.
A Palm Beach property occupied seasonally while the family maintains its permanent residence in Singapore generally will not qualify for Florida's homestead exemption. Neither periodic occupation nor a completed purchase establishes eligibility on its own. Second homes should also be distinguished from homestead properties benefiting from Save Our Homes assessment protection: second homes do not receive that protection.
Florida's non-homestead residential assessment limitation generally caps annual assessed-value increases at 10%, excluding school-board assessments. This is not a 10% ceiling on the total tax bill. Budget discussions should distinguish assessed value from the eventual amount payable, rather than treating an assessment limitation as a spending guarantee.
For a household that later establishes qualifying permanent residency, homestead eligibility in Palm Beach County generally requires ownership and permanent residency as of January 1, with a standard application deadline of March 1. The first $25,000 of a qualifying exemption applies to all property taxes, including school taxes. The additional exemption has different assessment thresholds and excludes school taxes.
Foreign citizenship alone does not determine eligibility. The ability to establish permanent residence and the property's actual use matter; certain dependent-residence situations may also qualify. These nuances warrant individual advice, not an assumption that a foreign-owned seasonal residence receives homestead relief.
A useful family charter need not resemble an institutional manual. It should identify one person authorized to coordinate the residence, a substitute when that person is unavailable and the decisions reserved for owners. These are recommended governance arrangements, not statutory requirements.
Separate routine administration from consequential choices. The coordinator might manage the calendar and ordinary preparation, while owners retain approval over extended guest stays, exceptional expenditure and proposed changes in use. Establish a spending threshold internally rather than leaving staff to interpret what counts as an emergency.
For overlapping requests, agree on priority before the calendar fills. Decide whether owners, adult children or accompanied guests take precedence, how cancellations work and who bears the costs of a visit. A shared home feels more generous when expectations are explicit.
When evaluating Forté on Flagler West Palm Beach, for example, use the family's proposed charter as a due-diligence questionnaire. Ask whether the intended pattern of family and guest use fits the applicable documents; a project's name does not establish its permissions.
Guest privileges can be subject to property-specific written conditions, and certain uses may require management permission. Family authorization alone may therefore be insufficient to establish a guest's right to stay. A condition applying to one accommodation should never be treated as a Palm Beach-wide occupancy rule.
Before purchase, request the documents relevant to owner-absent guests, overnight stays and any separate guest accommodation. Ask which permissions are required and who can grant them. Distinguish access to the residence from any entitlement to use shared facilities, and seek clarification wherever the documents leave uncertainty.
For a prospective purchase at Mr. C Residences West Palm Beach, the practical test is the same: have the intended stay arrangements checked against the applicable written conditions before confirming invitations. This is a due-diligence recommendation, not a statement about that project's guest policy.
Internally, a simple approval sequence works well: the family approves the visit, the coordinator confirms any property-level requirements, and arrival instructions follow only after both steps are complete.
An internal visit register can help coordinate arrivals, departures and household preparation. Treat it as a recommended family-management tool, not an assumed general Palm Beach requirement for visitor identity checks or access-log retention.
A proportionate register might record the visiting family member or lead guest, planned and actual dates, the approving family representative and any relevant management confirmation. Keep it focused on its operational purpose. Avoid creating an unnecessary archive of identity documents simply because the home is managed across borders.
Decide who may view the register, who corrects it and how long the family needs to retain it. Review those choices with advisers where privacy or legal obligations arise. A household calendar should not be presented as proof of homestead eligibility.
For continuity, keep the visit register alongside a current contact sheet and an escalation plan. The aim is straightforward: someone should know whom to call when plans change, without sharing the family's wider affairs with everyone involved in the residence.
Succession planning should address both the ownership interest and the authority to keep the home functioning. Ask advisers to distinguish who will own the property, who can authorize expenditure during a transition and who will communicate with management. A family-appointed coordinator should not be assumed to have legal authority over ownership matters.
Owners should report ownership or use changes that may affect exemptions, including changes associated with sale, marriage, divorce or death. Ownership transfers may also affect assessment limitations or exemption status. An inheritance or other transfer should therefore trigger a review, not an assumption that existing tax treatment continues unchanged.
No single trust or company structure should be treated as the default answer for a Singapore-based household. Ask advisers to coordinate their assessment of the proposed arrangement before implementation, without assuming a particular estate-tax result or a mechanism for avoiding probate.
Before the first season, assemble the family charter, applicable property rules, visit-record protocol and adviser contact plan. Revisit them when ownership, family circumstances or actual use changes. The most valuable outcome is a residence that remains welcoming without depending on informal understandings.
Explore a considered approach to your South Florida second home with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationA home used seasonally while the family's permanent residence remains in Singapore generally will not qualify. Purchasing or periodically occupying the property alone does not establish eligibility.
No. The owner's ability to establish permanent residence and the home's actual use matter, and certain dependent-residence situations may also qualify.
No. It generally limits annual assessed-value increases for non-homestead residential property, excluding school-board assessments, rather than capping the total tax bill.
No. Second homes do not receive the Save Our Homes assessment protection available to qualifying homestead properties.
Eligibility generally requires ownership and permanent residency as of January 1. The standard application deadline is March 1 for the year the exemption is sought.
As a recommended internal arrangement, it should identify decision-makers, visit priorities, spending authority and a substitute coordinator. It should distinguish routine administration from decisions reserved for owners.
Not necessarily. Property-specific written conditions may apply, and certain uses may require management permission.
The register proposed here is a governance recommendation, not a statement of a general legal requirement. Confirm any obligations applicable to the particular property separately.
A proportionate register might include the lead visitor, planned and actual dates, family approval and relevant management confirmation. Limit access and retention to the register's practical purpose, with adviser review where needed.
It should not be assumed to continue, because ownership transfers may affect assessment limitations or exemptions. Ownership or use changes affecting exemptions should also be reported to the county.