For an Austin buyer acquiring a Coconut Grove second home, a disciplined closing plan connects liquidity, property insurability, title review, and financing deadlines without assuming that one approval resolves the others.
An Austin buyer’s move into Coconut Grove can be a lifestyle decision without becoming a rushed financial one. The residence may be intended for occasional stays rather than a change of primary address. Either way, the acquisition calls for a closing plan that separates four questions: what cash must remain available, whether coverage can be bound, what title review reveals, and which financing conditions remain unresolved.
Treat these questions as parallel workstreams, not consecutive approvals. A preferred residence at Arbor Coconut Grove should prompt the same transaction-specific questions as any other candidate: what documentation is available, who must review it, and when must each decision be made? A project name alone answers none of them.
The objective is not simply to reach closing. It is to arrive with the property, financing, insurance, and remaining liquidity aligned with the intended use.
Avoid assigning a universal percentage to closing costs. Request an itemized estimate from the closing professional and lender, where applicable. Ask them to identify anticipated charges, prepaid amounts, deposits already credited, and items that remain provisional. Have each party explain which figures may change before settlement.
Organize the cash plan into three distinct amounts: funds expected at closing, any post-closing liquidity the lender requires, and your own contingency cushion. Do not assume the same dollars can serve all three purposes. Ask the lender how available funds must be documented before moving money between accounts.
For a second home, consider a separate operating budget for ownership after closing. Request property-specific insurance pricing rather than carrying over an Austin budget or treating a preliminary indication as a binding commitment. If an inspection raises a repair question, request a written scope and estimate before deciding how much additional liquidity to preserve.
Keep furnishing and discretionary improvements outside the closing reserve. That distinction protects flexibility without suggesting there is one correct reserve amount for every Coconut Grove purchase.
Begin with an insurance professional’s review of the actual property and proposed use. Ask what information is needed, which inspections may apply, and what must happen before coverage can be bound. Early review is a planning measure, not a contractual right or a guarantee of coverage.
Ask the adviser to identify the coverage options relevant to the residence and explain any eligibility conditions, exclusions, deductibles, or unresolved requirements. Request written confirmation of what remains preliminary and what is needed to secure coverage for the intended effective date.
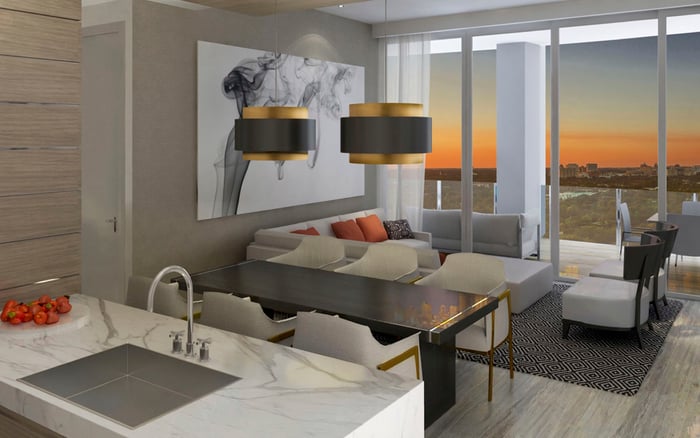
When considering Park Grove Coconut Grove, ask the insurance adviser and lender to identify the documents relevant to the particular purchase. Do not assume requirements for an older house apply unchanged to a condominium transaction. For a condominium, ask which building-level insurance documents should be reviewed alongside the proposed coverage for the residence.
Ask the insurance professional whether roof age, roof condition, or other inspection findings affect the available coverage. If additional documentation or repairs are requested, establish who will obtain them, what they will cost, and whether the timing fits the contract. Do not assume that an inspection report alone resolves underwriting questions.
Keep weather-related timing separate from property eligibility. Ask the adviser whether any current binding restrictions affect the proposed policy and how changes would be communicated before closing. Confirm what must occur for coverage to become effective rather than relying only on an earlier quote.
Ask counsel what the contract provides if insurance cannot be bound on schedule. Do not assume a storm automatically extends closing or creates a right to cancel. Keep the lender informed of any unresolved insurance condition that could affect funding.
Title review should be a defined assignment, not a general reassurance that paperwork is underway. Ask Florida real-estate counsel to explain the proposed ownership structure, review the title materials supplied, and identify matters requiring further investigation or action before closing.
Useful questions include whether an exception affects your intended use, whether a recorded restriction warrants closer review, and what documentation would resolve an identified concern. Ask counsel to explain the contract’s objection and response procedures rather than assuming a broad right to cancel or require a cure.
If your search includes Four Seasons Residences Coconut Grove, maintain the same discipline: request transaction-specific legal review rather than inferring title quality, delivery terms, or available protections from the residential name. No particular title issue is implied by that comparison.
Keep legal conclusions separate from insurance conclusions. Ask each professional to state what has been reviewed, what remains open, and who is responsible for the next step.
Before signing, ask the lender to confirm how it will evaluate the intended second-home use and what borrower, property, insurance, or other documentation it expects. Request a written list of outstanding conditions, and distinguish preliminary approval from the lender’s eventual authorization to fund.
Then ask counsel to map those conditions against the actual contract. Does the agreement contain financing protection? What must the buyer do to preserve it? What deadlines, notices, or limitations apply? If valuation is a concern, ask specifically how the contract addresses it rather than assuming financing language supplies a separate appraisal right.
For a candidate such as Opus Coconut Grove, the useful question is not whether financing should be straightforward. It is whether this lender has reviewed the documentation relevant to this purchase and identified everything still needed.
Maintain one calendar covering contractual deadlines, inspections, insurance decisions, title responses, lender submissions, and settlement preparations. Assign an owner to each outstanding item and request written confirmation when it is resolved. Before committing to travel from Austin, ask the closing team what still depends on another party’s action.
Preserve room for judgment. If coverage, title, or financing remains uncertain, discuss the available contractual options with counsel before a deadline passes. A considered second-home purchase is defined not by speed, but by knowing which commitments are final and which remain conditional.
For a discreet conversation about your Coconut Grove second-home search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationBuild the reserve from itemized estimates supplied by the closing professional and lender, rather than a universal percentage. Keep closing funds, any lender-required liquidity, and your own contingency cushion distinct.
Begin while purchase choices and contractual decisions remain open. Early review helps identify documentation and inspection needs but does not guarantee coverage or create a cancellation right.
Ask an insurance professional to assess the actual property and intended use. Request an explanation of eligibility conditions, exclusions, deductibles, and any unresolved requirements.
Ask the insurance adviser and lender which building-level documents and residence-specific coverage materials they need. Do not assume requirements for a house apply unchanged to a condominium.
Ask the insurance professional whether roof age or condition affects available coverage. If documentation or repairs are requested, confirm their cost, responsibility, and timing.
Do not treat a preliminary quote as confirmation that coverage is bound. Ask what remains outstanding and what must occur for coverage to become effective.
Ask the insurance adviser whether any current restrictions affect the proposed policy and how changes will be communicated. Confirm the steps needed to secure the intended effective date.
Do not assume it does. Ask counsel to explain the actual contract’s provisions and any steps needed before a deadline passes.
Ask counsel to review the supplied title materials, explain exceptions or restrictions, and identify unresolved concerns. Have counsel clarify the contract’s objection procedures and available responses.
Treat preliminary approval and authorization to fund as separate checkpoints. Request a written list of outstanding conditions and have counsel compare them with the contract’s financing protections and deadlines.