A disciplined framework for aligning an assignment purchase with the intended titleholder, homestead objectives, financing, insurance review, and realistic expectations of ownership privacy.
For a South Florida luxury buyer taking an assignment before completion, the ownership decision deserves as much attention as the residence itself. The central question is not simply whose name will appear on the deed, but whether that title arrangement supports the buyer’s intended occupancy, financing, privacy expectations, and long-term family planning.
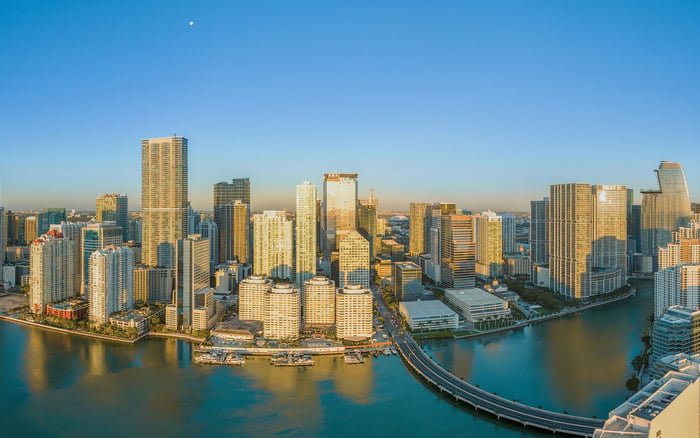
A residence under consideration in Brickell, including The Residences at 1428 Brickell, provides a useful setting for this discussion, without implying that any particular assignment is available or permitted. Ask counsel to review the proposed assignment and intended closing ownership together, rather than leaving title as a detail to settle afterward.
The objective is a coordinated file: one ownership plan understood by the buyer’s attorney, tax adviser, lender, and insurance adviser.
An LLC can appear on a Florida deed instead of its individual member. That provides a limited layer of ownership privacy, not a promise of anonymity. Entity ownership on the deed does not, by itself, resolve the buyer’s other objectives.
An LLC-owned Florida residence ordinarily does not qualify for homestead benefits merely because its sole member occupies it as a primary home. A buyer seeking both entity ownership and homestead treatment should identify that potential conflict before committing to the structure.
Homestead is not a single, interchangeable protection. Tax treatment, creditor protection, spousal rights, and inheritance raise distinct questions. A favorable conclusion on one does not settle the others.
The practical first document is a short statement of priorities. Specify whether the residence is intended as a principal home, which privacy outcome matters, and which family or liability concerns require separate advice. That statement gives advisers a common brief.
A properly structured revocable trust may preserve homestead eligibility when the beneficiary’s ownership and occupancy rights satisfy the applicable requirements. The operative words are “properly structured.” A trust label is no substitute for reviewing the governing language.
A land-trust beneficiary’s principal residence may also qualify for the homestead tax exemption when the beneficiary meets the applicable requirements. This is not automatic approval for every trust arrangement.
For a buyer considering Coconut Grove, perhaps while evaluating Four Seasons Residences Coconut Grove, the useful comparison is between ownership structures, not just residences. Ask counsel to read the trust and proposed deed together and establish the intended beneficial ownership and right to occupy.
Trust ownership generally does not provide the same liability separation as an LLC. Homestead compatibility and liability protection therefore require separate analysis, even when the buyer hopes to address both through one arrangement.
Entity borrowing may be priced or underwritten differently from an individual owner-occupied mortgage. The intended titleholder is therefore a financing decision as well as a legal one. Do not build the acquisition plan around an individual borrowing assumption while leaving entity ownership unresolved.
Depending on the lender and structure, the financing file may require organizational documents, ownership identification, purchase authorizations, and personal guarantees. Ask the lender which requirements apply to the proposed arrangement, and have counsel review their implications before documents are finalized.
For a pre-construction assignment, frame the financing conversation around the actual proposal: who would take the assignment, who would borrow, and who would receive title. Ask the lender and counsel to resolve any differences among those roles.
A written comparison can clarify the proposed owner, financing terms, required guarantees, and unresolved approvals. Its purpose is not to assume that one structure is preferable, but to make the trade-offs clear before selecting it.
If an entity remains the preferred purchaser, closing preparation includes selecting its legal name, filing formation documents, appointing a registered agent, and preparing the relevant governing agreement. Obtain an EIN where required, and identify the members, managers, or other parties authorized to act before closing documents are finalized.
Organize these materials around a few practical questions:
Is the proposed purchaser’s legal name settled?
Are formation and governing documents ready for review?
Who is authorized to sign for the purchaser?
What ownership identification and purchase authorizations does the lender request?
Are any personal guarantees contemplated?
A Miami Beach buyer evaluating The Perigon Miami Beach can use the same framework without assuming anything about that project’s assignment policy. Keep property-specific contract questions with counsel and document entity authority clearly.
Review assignment permissions, required consents, financial obligations, and timing against the actual transaction documents. Ask counsel to explain what the proposed assignment transfers, which obligations the buyer would undertake, and what remains unresolved. Do not infer permission from the existence of an entity or a financing proposal.
Insurance deserves an equally explicit conversation. Ask the insurance adviser to assess the proposed titleholder, intended occupancy, and any trust or entity interests. Request advice on how those interests should be reflected in the coverage under consideration and what information is needed before closing.
These are review instructions, not universal coverage requirements. Seek property-specific answers rather than assuming that an ownership structure approved for one purpose will work unchanged for insurance. Keep the adviser’s conclusions with the legal and lending file so that remaining questions stay visible.
Buying personally and transferring the residence into an LLC afterward should not be assumed tax-neutral. Moving a residence into an LLC can jeopardize homestead treatment and trigger reassessment. The convenience of postponing a title decision may conceal a consequential tax question.
For a West Palm Beach search that includes Alba West Palm Beach, resolve the same ownership questions before settling on a closing structure. If a later transfer is contemplated, obtain legal and tax advice on that specific plan rather than treating it as routine housekeeping.
The finished file should distinguish decisions from assumptions: intended owner, occupancy objective, homestead analysis, financing terms, signing authority, assignment review, and insurance advice. Assign each unresolved item to a named adviser responsible for answering it.
This is transaction-planning information, not a substitute for property-specific legal, tax, lending, or insurance advice. The strongest ownership plan is not necessarily the most elaborate; it is the one whose consequences the buyer understands before completion.
For a discreet perspective on South Florida residences and the decisions surrounding their acquisition, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationAn LLC can appear as the deed owner instead of its individual member. This provides a limited layer of ownership privacy, not a guarantee of anonymity.
Ordinarily, an LLC-owned Florida residence does not qualify for homestead benefits merely because its sole member occupies it as a primary home.
A properly structured revocable trust may preserve eligibility when the beneficiary’s ownership and occupancy rights meet the applicable requirements. Counsel should review the trust and deed together.
A land-trust beneficiary’s principal residence may qualify when the beneficiary meets the applicable requirements. That does not automatically qualify every trust arrangement.
No. Tax benefits, creditor protection, spousal rights, and inheritance involve distinct considerations, and eligibility for one does not settle the others.
Yes. Entity borrowing may be priced or underwritten differently from an individual owner-occupied mortgage, with requirements that depend on the lender and structure.
A lender may request organizational documents, ownership identification, purchase authorizations, and personal guarantees. The buyer should confirm the requirements for the proposed structure.
Preparations include formation documents, a registered agent, the governing agreement, an EIN where required, and identification of authorized signers.
No. Such a transfer can jeopardize homestead treatment and trigger reassessment, so the proposed transfer deserves specific legal and tax review.
Ask counsel to review the actual assignment documents and have an insurance adviser evaluate the proposed ownership and occupancy arrangement. Do not assume that legal or lending acceptance resolves insurance questions.