A practical buyer’s review of Tula Residences, separating advertised features from the documentation needed to assess flood claims, critical equipment elevations, insurance and post-storm service continuity.
For a waterfront condominium buyer, luxury includes confidence that essential systems are protected and everyday services can resume after a disruption. At Tula Residences North Bay Village, the practical review centers on three questions: what loss history is documented, where critical equipment sits, and how building operations would resume after a storm.
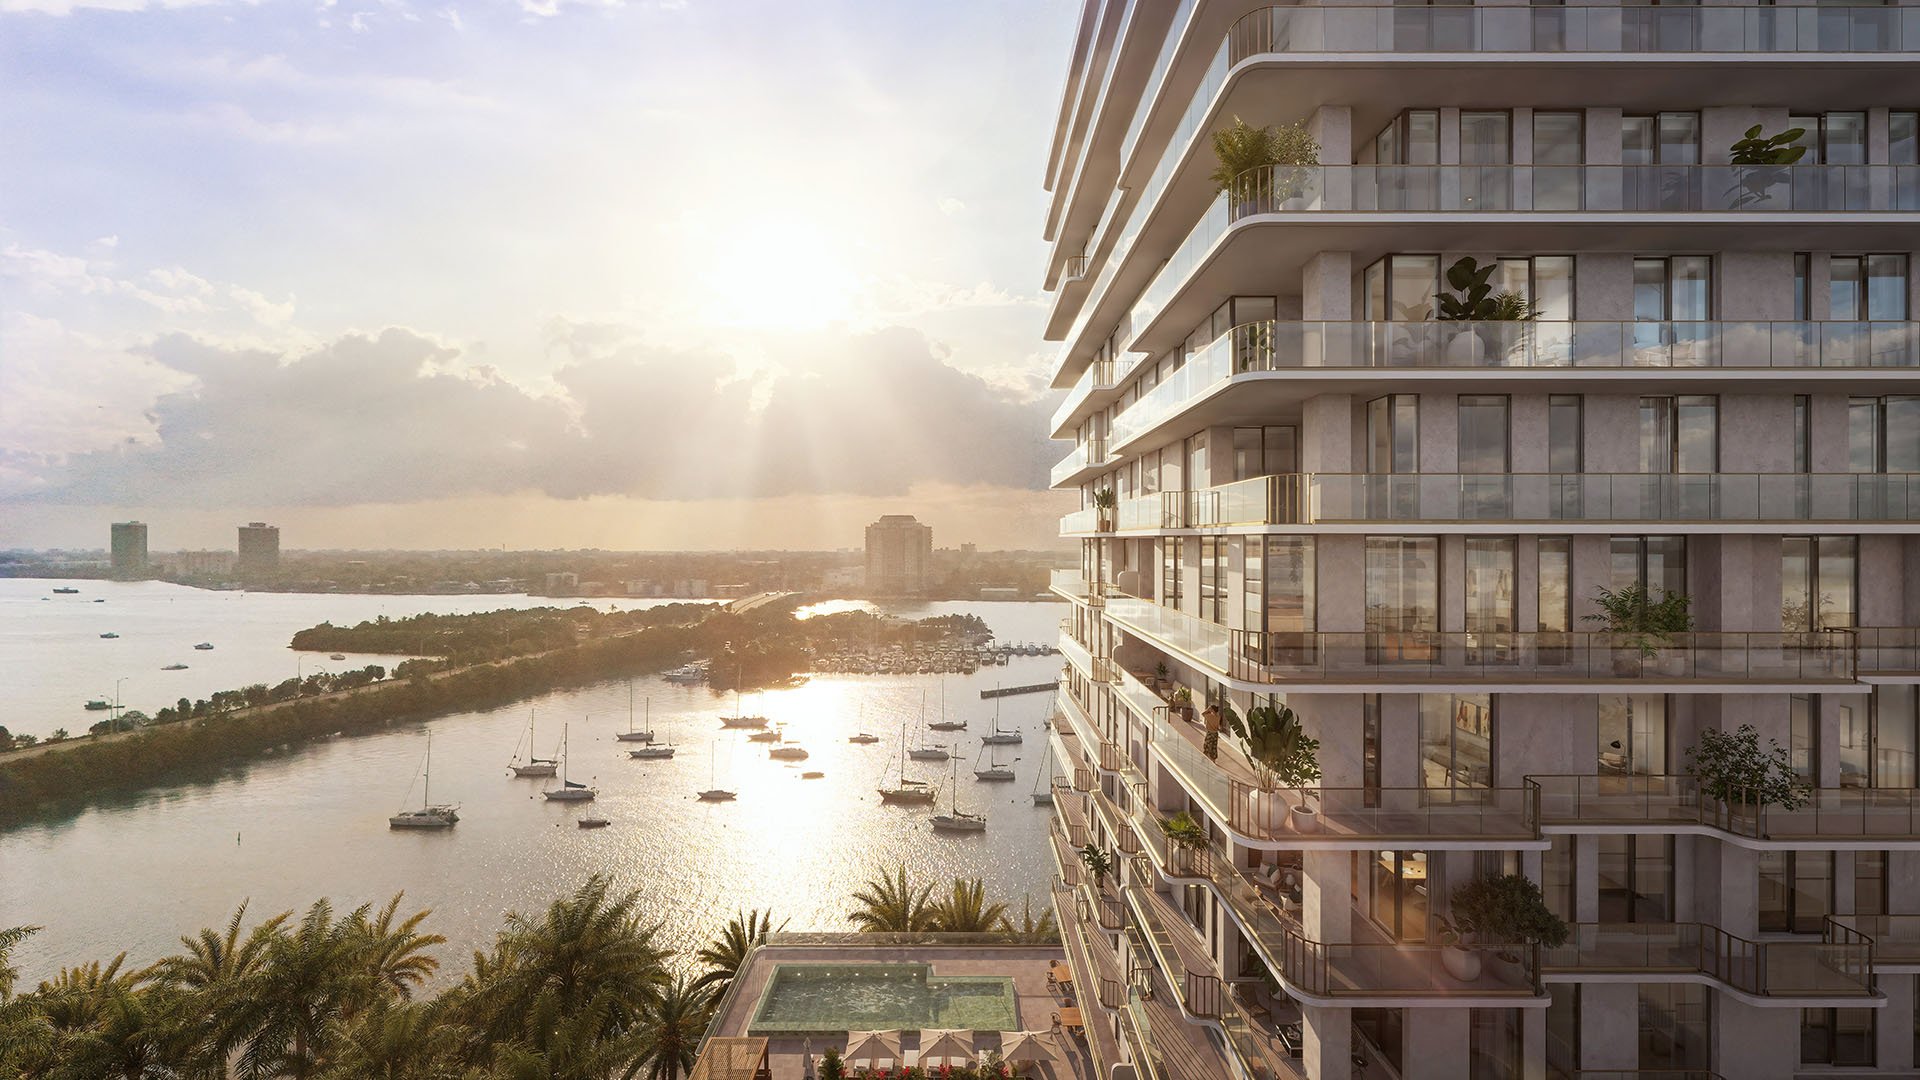
Tula is a waterfront condominium project at 7918 West Drive, North Bay Village, FL 33141. Its appeal should be weighed alongside those operational questions, not used to sidestep them. Tula-specific flood-claim records, equipment-protection elevations and a written business-continuity plan remain unverified. That does not establish defective systems, uninsured losses or inadequate management. It identifies the matters on which a buyer should seek written answers.
The distinction is straightforward: an advertised feature is not documented resilience.
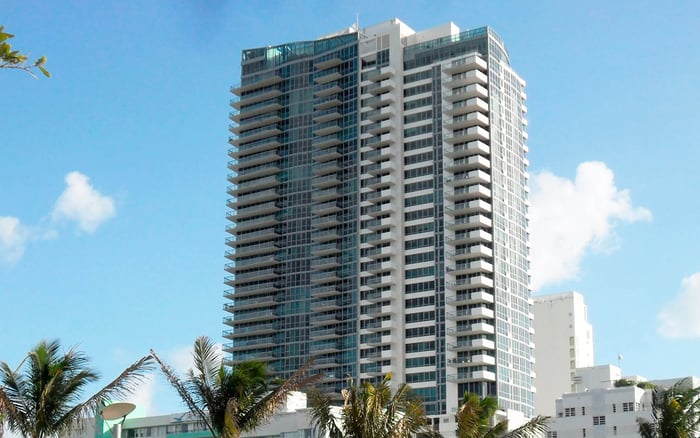
The project has been described as 21 stories with 54 residences, including six penthouses. Some unit descriptions instead indicate 22 stories. Reconcile that discrepancy against current developer documents.
Construction stalled in late 2023 and restarted following a takeover by Vivian Dimond’s firm in late 2024. Pacific & Orient was to remain a partner without continuing to handle construction or development. For a buyer, that history makes it important to establish which entity now handles construction, warranty and operational-handover questions.
Earlier completion forecasts differ between 2026 and 2027. Neither guarantees delivery or establishes current completion status. Request an updated schedule, the applicable contractual delivery provisions and a clear account of outstanding milestones before organizing a move or committing to carrying costs elsewhere.
Buyers also considering Continuum Club & Residences North Bay Village can apply the same document-first standard. Compare the evidence each project provides without assuming equivalent timelines or protections.
North Bay Village is identified as an area of moderate to high flooding risk. That broader context makes a property-specific flood-hazard review important, but it does not establish Tula’s precise flood zone, a previous loss or an insurance claim.
Ask the developer or authorized representative for available insurance loss histories covering the property and relevant construction periods. Request the dates covered, the insured entities and confirmation of whether the records include flood losses. Treat any gap as an open question, not evidence of a clean history.
Separately, seek available disclosures about water intrusion, remedial work and unresolved claims. These are recommended document requests, not statements that such events occurred at Tula. Have an insurance adviser reconcile the responses with policy schedules, deductibles, limits and exclusions.
Contact the Building Department to ask about past flooding in the area. Neighborhood flooding information and building-specific insurance history answer different questions; neither substitutes for the other. Checking the property’s flood-hazard zone and purchasing and maintaining flood insurance are also part of preparedness.
Tula’s advertised above-ground garage provides useful parking information, but it does not establish the elevation of individual spaces or critical building systems. The question is not simply whether a garage is above ground, but whether vulnerable equipment is appropriately protected relative to the applicable flood elevation.
Request available elevation certificates and mechanical and electrical drawings. Ask a qualified professional to identify the locations and protection details of electrical rooms, pumps, elevator controls and any generator equipment. Elevation or floodproofing is generally called for where electrical and mechanical equipment occupies relevant lower-level enclosures. That general principle does not verify Tula’s installed design or establish the requirements for every component.
The advertised details require equally careful interpretation. Unit 902 specifies two assigned, covered garage spaces. Unit 1001 advertises secured parking, fire sprinklers, a fire alarm and smoke detectors. Those descriptions do not demonstrate flood protection, and one unit’s parking allocation should not be generalized to every residence.
A secure package room and optional private storage at additional cost are also advertised. Their flood-protection elevations remain unverified. Before purchasing storage or assigning vehicles to particular spaces, request the relevant locations and access arrangements.
For a comparison with Shoma Bay North Bay Village, apply the same equipment-location questions. Review the drawings and specifications before drawing conclusions about either project’s relative resilience.
A continuity plan should explain more than emergency messaging. For an owner who may be away when a storm approaches, it should identify who acts, which services remain available and what conditions govern a return.
A Tula-specific written plan for backup power, staffing, emergency access, re-entry, elevator restart and service restoration remains unverified. Request the proposed procedures, distinguishing construction-stage arrangements from the operating plan intended for the completed condominium.
If backup generation is proposed, ask which loads it serves, its stated operating assumptions and how fuel replenishment would be handled. Do not assume backup power includes residence air-conditioning, outlets or normal elevator service. Seek specifications, not a general assurance that a generator is provided.
Request written answers covering staff responsibilities, owner notifications, contractor access, pump checks and authorization to restart elevators. Ask how absent owners would receive updates and arrange an authorized inspection of their residence once access is permitted.
Review hurricane readiness, evacuation centers, evacuation bus pickup locations and special-assistance registration relevant to residents dependent on medical equipment or electricity. These preparedness measures do not establish a condominium’s own continuity plan. During the Hurricane Milton response, active construction sites were subject to inspections and a work stoppage-a reminder to distinguish site procedures from eventual residential operations.
Organize the review into three files: loss history and insurance, equipment elevations and protection, and operational continuity. For each unresolved item, record the requested document, the responsible party and when the answer is needed for the purchase decision.
This discipline also supports comparisons beyond the village. A buyer weighing Tula against Five Park Miami Beach should ask consistent questions without treating location or presentation as proof of equivalent storm readiness.
The ownership judgment is conditional, not adverse: evaluate Tula’s residential proposition alongside documentary answers about flood exposure and service recovery. A qualified insurance adviser, engineer and purchase attorney can help translate those answers into an informed commitment.
For a discreet conversation about South Florida condominium ownership, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationTula Residences is a waterfront condominium project at 7918 West Drive, North Bay Village, FL 33141.
Tula-specific flood-claim records and insurance loss histories remain unverified. That does not establish either a claim-free history or a previous loss.
No. The municipality’s moderate to high flooding risk is distinct from a property-specific flood zone, flooding event or insurance claim.
No. The advertised garage description does not establish the elevations of parking spaces, electrical rooms, pumps or other critical equipment.
Request available elevation certificates, mechanical and electrical drawings, and generator and pump specifications. A qualified professional should assess equipment locations and applicable protection requirements.
The description for Unit 902 specifies two assigned, covered garage spaces. That allocation should not be assumed for every residence.
A secure package room and optional private storage at additional cost are advertised, but their flood-protection elevations remain unverified.
Earlier forecasts differ between 2026 and 2027, and neither should be treated as guaranteed. Buyers should obtain a current schedule and review contractual delivery provisions.
A written plan covering backup power, staffing, emergency access, re-entry and service restoration remains unverified. Municipal preparedness resources do not substitute for building-specific procedures.
Ask how notifications, authorized inspections, contractor access and re-entry would be handled. Also request clarity on available backup-power loads and the process for restarting elevators.