Hotel-standard service does not mean hotel-funded service. In a mixed-use Miami tower, residential owners generally pay the condominium’s allocated staffing costs through assessments, while shared-service agreements and individual purchases determine the rest.
A polished arrival and an attentive concierge can make residential life feel effortless. The financial structure behind that experience deserves equally close attention. In a mixed-use Miami tower, residential owners generally fund the condominium’s share of hotel-standard staffing through assessments. A hotel name at the entrance does not, by itself, mean the hotel pays for the people serving residents.
The decisive question is not simply who employs the staff. It is which entity bears the expense, how that expense is divided and how the residential portion reaches each owner’s monthly assessment. The declaration, operating budget and applicable shared-services agreements offer more clarity than a promise of seamless hospitality.
For a buyer, clarity is part of the luxury proposition: knowing which services are included, which are shared and which carry separate charges.
Florida condominium law treats the operation, maintenance, repair, replacement and protection of common elements and association property as common expenses. Expenses incurred in carrying out the association’s powers and duties also fall within that framework. Owners pay common expenses through assessments, with their respective shares governed by the applicable law and declaration.
That makes staffing more than a lifestyle line item. Security or building engineering that operates or protects condominium common areas can fall within common expenses. Security, communications, transportation and similar services may also qualify when reasonably related to the general benefit of unit owners.
Florida law identifies a condominium containing both commercial and residential units as mixed-use. That classification, however, does not supply a universal hotel-versus-residential staffing formula. The ownership structure and governing documents still matter. Buyers should not assume that every mixed-use tower divides expenses in the same way.
The clearest way to read a service budget is to distinguish three categories rather than treat every employee as part of one hospitality package.
Residential-only staffing.
Ask which personnel serve the condominium exclusively and where their costs appear in the residential budget. Examine a dedicated residential service as its own expense, distinct from the hotel’s operating obligations.
Shared building staffing.
Where personnel serve residential, hotel or commercial components, the critical issue is allocation. Request the agreement and formula establishing how that cost is divided. A general explanation that the building has shared services is no substitute for the allocation provisions themselves.
Individually purchased services.
Housekeeping, room service, spa treatments and dining can be billed separately to an individual unit. These purchases are distinct from the common costs of keeping shared operations available. Confirm both what an assessment includes and what a resident pays for only when ordering.
These distinctions guard against two opposite assumptions: that every service is included, or that declining optional services eliminates the shared operating expense.
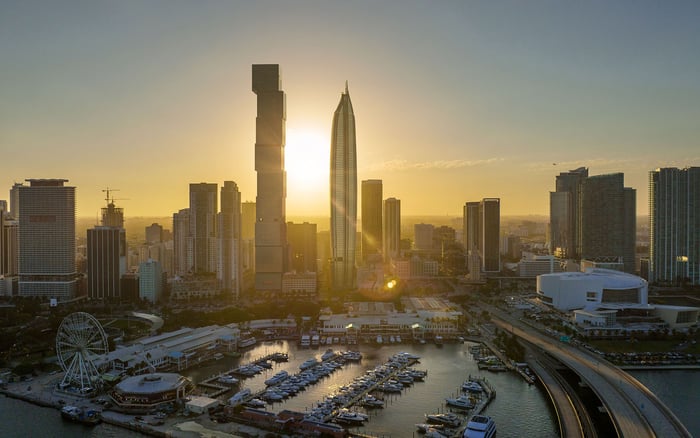
In Downtown Miami, Waldorf Astoria Residences Downtown Miami illustrates the coexistence of hotel operations and residential concierge services. Their presence together does not establish the residential share of payroll. Nor should a preliminary fee estimate be treated as an adopted condominium budget.
The right question is more specific than whether a tower offers hotel-standard service: what portion of the service infrastructure is a residential common expense, and what document establishes that obligation?
The same discipline applies to a Brickell search. A buyer considering Cipriani Residences Brickell should request the applicable service and expense documents rather than infer a cost structure from the name. This is a diligence principle, not a suggestion that different branded residences use identical operating models.
Branding describes an experience. The governing documents establish the financial obligations associated with delivering it.
An owner who rarely visits an amenity may still contribute to its operation through association dues. In condo-hotel arrangements, those dues can support hotel-operated facilities even when an individual owner makes little use of them.
The practical distinction is between purchasing a service and funding an allocated common expense. Choosing not to order dinner is different from declining to contribute to an amenity’s shared operating costs. Whether a particular charge applies depends on the governing documents, not simply on personal usage.
For a seasonal resident, this deserves particular attention. Ask which costs remain payable while the residence is unoccupied and which charges arise only when services are requested. Do not assume that limited occupancy changes the unit’s allocated assessment obligation.
A hotel rental program introduces another financial relationship. Operator management fees and rental-revenue sharing may apply to participating owners, but those arrangements are distinct from condominium assessment obligations.
Buyers should therefore examine two separate calculations: the cost of ownership and the economics of rental participation. Rental proceeds should not be confused with a contractual promise that the hotel funds residential staffing.
Request an explanation of assessment obligations independently of any rental presentation. Then review the rental agreement for its own charges and revenue-sharing terms. Keeping those obligations distinct clarifies what the owner owes, regardless of rental performance.
Before comparing residences, request the recorded declaration and amendments, the operating budget, relevant shared-services agreements and the formula dividing staff costs among residential, hotel and commercial components. Obtain the charges for the specific unit in writing.
Ask the reviewing team to trace the staffing expense from the operating arrangement to the residential budget and then to the unit’s assessment. If an employee serves multiple components, identify where the division of that cost is established. If a service is optional, confirm how it is billed.
When considering St. Regis® Residences Brickell alongside other residences, apply the same document-led review without assuming a shared staffing model. Compare defined obligations, not merely similarly worded service descriptions.
Finally, distinguish projected figures from adopted budgets. A proposed monthly amount can help frame a purchase, but it should not be mistaken for a final allocation. The strongest comparison pairs the service offering with the documents explaining who pays for it.
Hotel-standard staffing can be a compelling part of residential ownership. The essential diligence is to understand the condominium’s share, the unit’s share and the services purchased separately. A recognizable name is no substitute for that accounting.
For a discreet conversation about evaluating Miami residences and their ownership obligations, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationResidential owners generally pay the condominium’s allocated share through assessments. Hotel branding alone does not make those services hotel-funded.
No universal hotel-versus-residential staffing formula follows from the common-expense framework. The applicable ownership structure, declaration and shared-services arrangements matter.
Staffing that operates or protects condominium common areas can fall within common expenses. The governing documents and applicable law determine the unit’s assessment obligations.
Florida law identifies a condominium containing both commercial and residential units as a mixed-use condominium.
No. Housekeeping, room service, spa and dining can be individually billed services, separate from shared operating expenses.
Yes. Association dues can support hotel-operated amenities even when an owner uses them infrequently, depending on the governing arrangements.
Request the recorded declaration and amendments, operating budget, relevant shared-services agreements and staffing cost-allocation formula. Obtain the specific unit’s charges in writing.
The declaration’s expense-allocation provisions and applicable law govern assessment obligations, rather than hotel-style marketing.
No. Operator management fees and rental-revenue sharing are distinct from an owner’s condominium assessment obligations.
No. Buyers should distinguish estimates from adopted budgets and confirm the specific unit’s charges and supporting allocation documents.