An enclosed terrace can cross several legal and insurance boundaries. For Miami condominium buyers, the essential review separates original construction from later alterations, structural components from finishes, and maintenance duties from actual policy coverage.
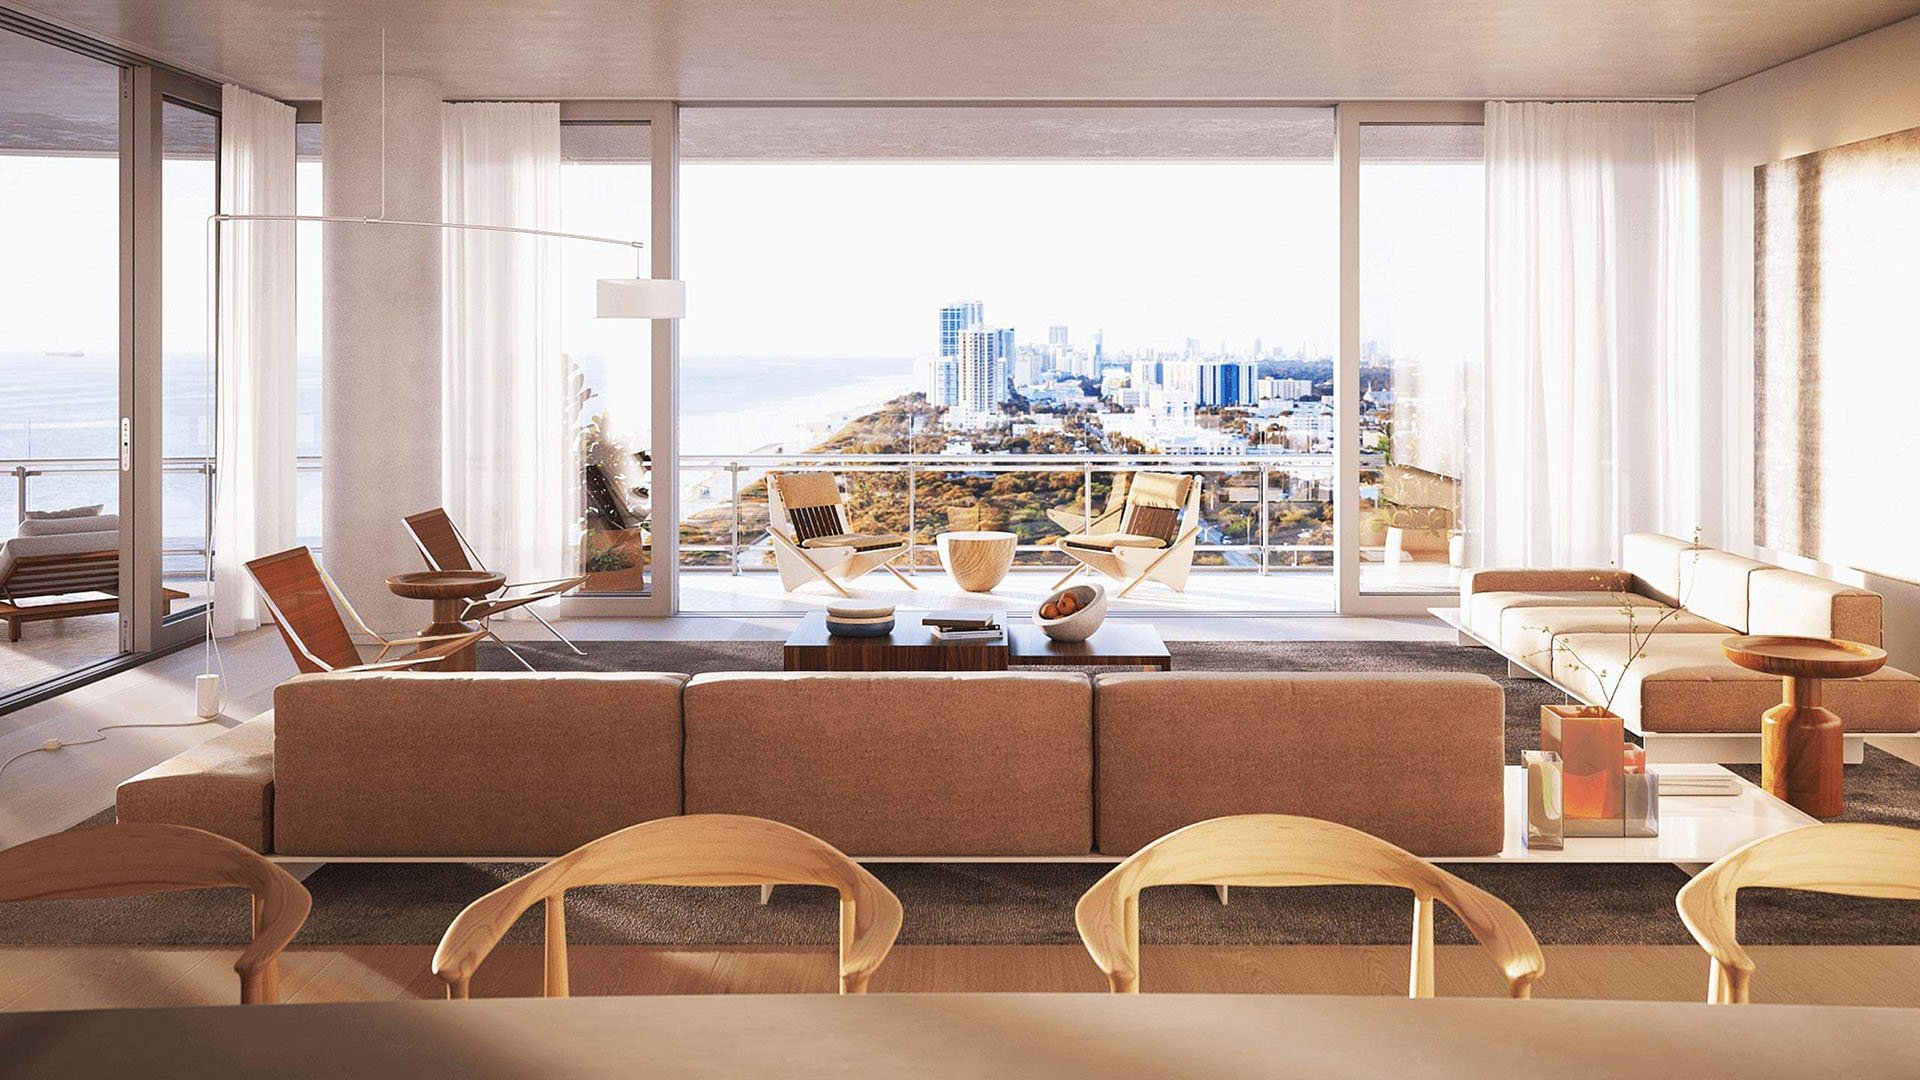
An enclosed terrace can feel like a seamless extension of a Miami residence: another sitting room, a quiet breakfast space, a setting for the view. Its insurance treatment, however, does not follow its appearance. Adding glass does not, by itself, establish whether the association or the unit owner must insure what sits behind it.
The answer requires reading several documents together: the recorded declaration, the original plans, any alteration approvals, the association’s master policy and the owner’s condominium policy. Legal boundaries, original construction and statutory exclusions all matter. For a buyer, the objective is not a reassuring label such as “fully enclosed,” but a written allocation of responsibility for each component.
Begin with the recorded declaration and amendments. A terrace may be part of the unit, a common element or a limited common element. Establish that classification from the governing documents, rather than inferring it from exclusive access or the way a residence is presented.
A limited-common-element designation does not place every item there under the association’s insurance. Personal property and other owner-responsible items can remain outside the association’s required coverage even within that space.
For buyers considering The Perigon Miami Beach or another Miami Beach condominium, this is a due-diligence principle, not a statement about any particular building’s terraces. The answer depends on the specific residence and its documents.
Treat ownership, maintenance and insurance as separate questions. A provision requiring an owner to maintain a component does not necessarily identify the policy that covers damage to it.
The 2025 version of Florida Statute §718.111 provides the framework discussed here; confirm subsequent amendments before relying on its wording. It requires a unit-owner-controlled residential condominium association to use its best efforts to obtain and maintain adequate property insurance for the property it must insure.
The statutory starting point is condominium property as originally installed, or replacements of like kind and quality consistent with the original plans and specifications. An enclosure included in the original construction may therefore fall within association-insured property. That does not guarantee coverage for every component or every loss: statutory exclusions and the actual policy still apply.
A later owner-installed enclosure requires a separate analysis. The statute addresses alterations and additions made pursuant to §718.113(2), so neither automatic association coverage nor automatic owner-only coverage is a sound assumption.
Request the original plans and enclosure approvals, then compare them with the existing installation. Ask the insurers to address the alteration explicitly. Approval of the work does not settle the insurance question.
An enclosed terrace is not a single insurance item. Its slab, structural walls, doors, glazing, finishes, fixtures and contents may require different treatment.
The association’s required property insurance excludes personal property within a unit or its limited common elements. The statutory exclusions also include floor, wall and ceiling coverings; electrical fixtures; appliances; water heaters and filters; built-in cabinets and countertops; and specified window treatments serving only the unit. Owners are responsible for insuring those excluded items.
For a carefully furnished terrace, the practical implication is straightforward: do not assume that flooring, cabinetry, qualifying fixtures or furniture are protected by the master policy simply because the enclosure itself may be association-insured.
Glass deserves a separate question. Windows and enclosure glazing are not the same as window treatments. The exclusion for treatments such as curtains, blinds and their hardware does not, by itself, resolve responsibility for the glass. Request a separate answer for windows, doors and enclosure panels.
An HO-6 condominium policy is commonly described as “walls-in” coverage. It primarily addresses the owner’s personal property and liability while also providing some structural coverage. The association’s master policy generally addresses the exterior structure and common areas.
Those descriptions are useful introductions, not component-by-component conclusions. An enclosed terrace is precisely where a simple interior-versus-exterior distinction can leave questions unanswered.
When evaluating a Brickell residence, including one at Una Residences Brickell, request both policies rather than relying on a general coverage summary. This recommendation makes no assumption about that project’s coverage or alteration rules. The task is to reconcile what the association insures with what the owner’s policy actually provides.
Ask whether each relevant owner-installed improvement is addressed, what limits apply and which exclusions could affect the contemplated space. A broad assurance that a residence has insurance is no substitute for those answers.
Before committing to a purchase, assemble the recorded declaration and amendments, original plans, enclosure approvals, master-policy coverage forms and deductibles, and the proposed or existing HO-6 policy.
Then request written answers from the insurers identifying the treatment of the slab, structural walls, windows, doors, enclosure glass, finishes, fixtures, contents and owner-installed improvements. Organizing those answers by component makes it easier to distinguish an unresolved question from an actual allocation of coverage.
For a Sunny Isles Beach buyer considering Jade Signature Sunny Isles Beach or another condominium, the same discipline applies without presuming anything about a particular residence’s enclosure. Test the answers against the actual documents, not the building’s name or the quality of its finishes.
Include loss-assessment coverage in the conversation. It can help pay an owner’s share of an assessment arising from a covered common-property loss, subject to policy terms and limits. It is not a blanket solution for every association assessment or an unresolved terrace-coverage question.
The most useful answer to “Who insures the terrace?” is often several answers, each tied to a different component. Establishing the responsible insured party is also distinct from determining whether that party’s policy covers a particular loss.
Where declaration language, alteration agreements, maintenance provisions and insurance terms appear inconsistent, seek review from a Florida condominium or insurance-coverage attorney. The goal is clarity before a loss: what must be insured, by whom, under which policy and subject to which limitations.
A terrace can remain an effortless part of daily life while its insurance arrangements receive exacting attention. For a substantial purchase, that distinction is worth preserving.
For a considered approach to South Florida condominium ownership, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Responsibility depends on the recorded documents, original construction, statutory requirements and applicable policies, not simply the presence of an enclosure.
Check the recorded declaration and amendments to determine whether the terrace is part of the unit, a common element or a limited common element.
An enclosure included in original construction may fall within association-insured property. Statutory exclusions and policy terms still determine coverage for specific components and losses.
No automatic allocation should be assumed. Later alterations require a separate review of the statutory framework, approvals, governing documents and policies.
No. Personal property and other statutorily excluded items remain the owner’s insurance responsibility even within limited common elements.
No. Window treatments are specifically addressed by statutory exclusions, while responsibility for windows and enclosure glass requires a separate review.
It primarily covers the owner’s personal property and liability, with some structural coverage. The actual policy must be checked to establish how it treats terrace components and improvements.
Not necessarily. Maintenance obligations and insurance responsibilities should be analyzed separately.
It can help pay an owner’s share of an assessment arising from a covered common-property loss, subject to policy terms and limits. It does not cover every assessment automatically.
Request the declaration and amendments, original plans, enclosure approvals, master-policy coverage forms and deductibles, and the owner’s HO-6 policy. Obtain written component-level coverage answers and legal review where provisions conflict.