Preconstruction and recently delivered residences call for different financial diligence. For South Florida buyers, the meaningful comparison is between budget assumptions and operating evidence, with careful attention to service charges, reserve funding, and special-assessment exposure.
For a South Florida luxury buyer, the distinction between preconstruction and a recently delivered residence is not simply anticipation versus immediate enjoyment. It is also a choice between two kinds of financial evidence: the assumptions behind a proposed association budget and the operating information available after delivery.
Neither category is automatically less expensive or better protected against assessments. The more useful question is whether the ownership structure supports your priorities: predictable carrying costs, selective use of services, or confidence in long-term building stewardship. A beautifully resolved residence deserves an equally considered financial review.
The monthly assessment is a starting point, not a verdict. Its meaning depends on what it includes, how reserves are funded, and which obligations fall outside it.
A preconstruction review should begin with the proposed association budget and its underlying assumptions. Condominium assessments generally fund both operations-staffing, management, maintenance, and shared services-and reserves for future repairs or replacements. Buyers should ask how each category is reflected in the quoted payment.
A developer-controlled Florida condominium association cannot vote to waive or reduce required reserves. Reserve assumptions therefore belong at the center of the review, not on a list of issues to revisit after delivery. Ask which obligations the reserve provision covers and how the proposed contributions relate to them.
For a Brickell search that includes The Residences at 1428 Brickell, keep the residence decision and financial review connected. Evaluate the relevant budget documents rather than treating the quoted assessment as a complete ownership estimate. This is a diligence principle, not a conclusion about that project's finances.
Preconstruction may suit a buyer comfortable evaluating projections. The discipline is to distinguish a documented assumption from an established operating result.
A recently delivered residence changes the questions; it does not remove them. Request the current budget, available financial statements, reserve information, and assessment disclosures. Compare planned and actual spending wherever the records allow, and establish how much operating history is available.
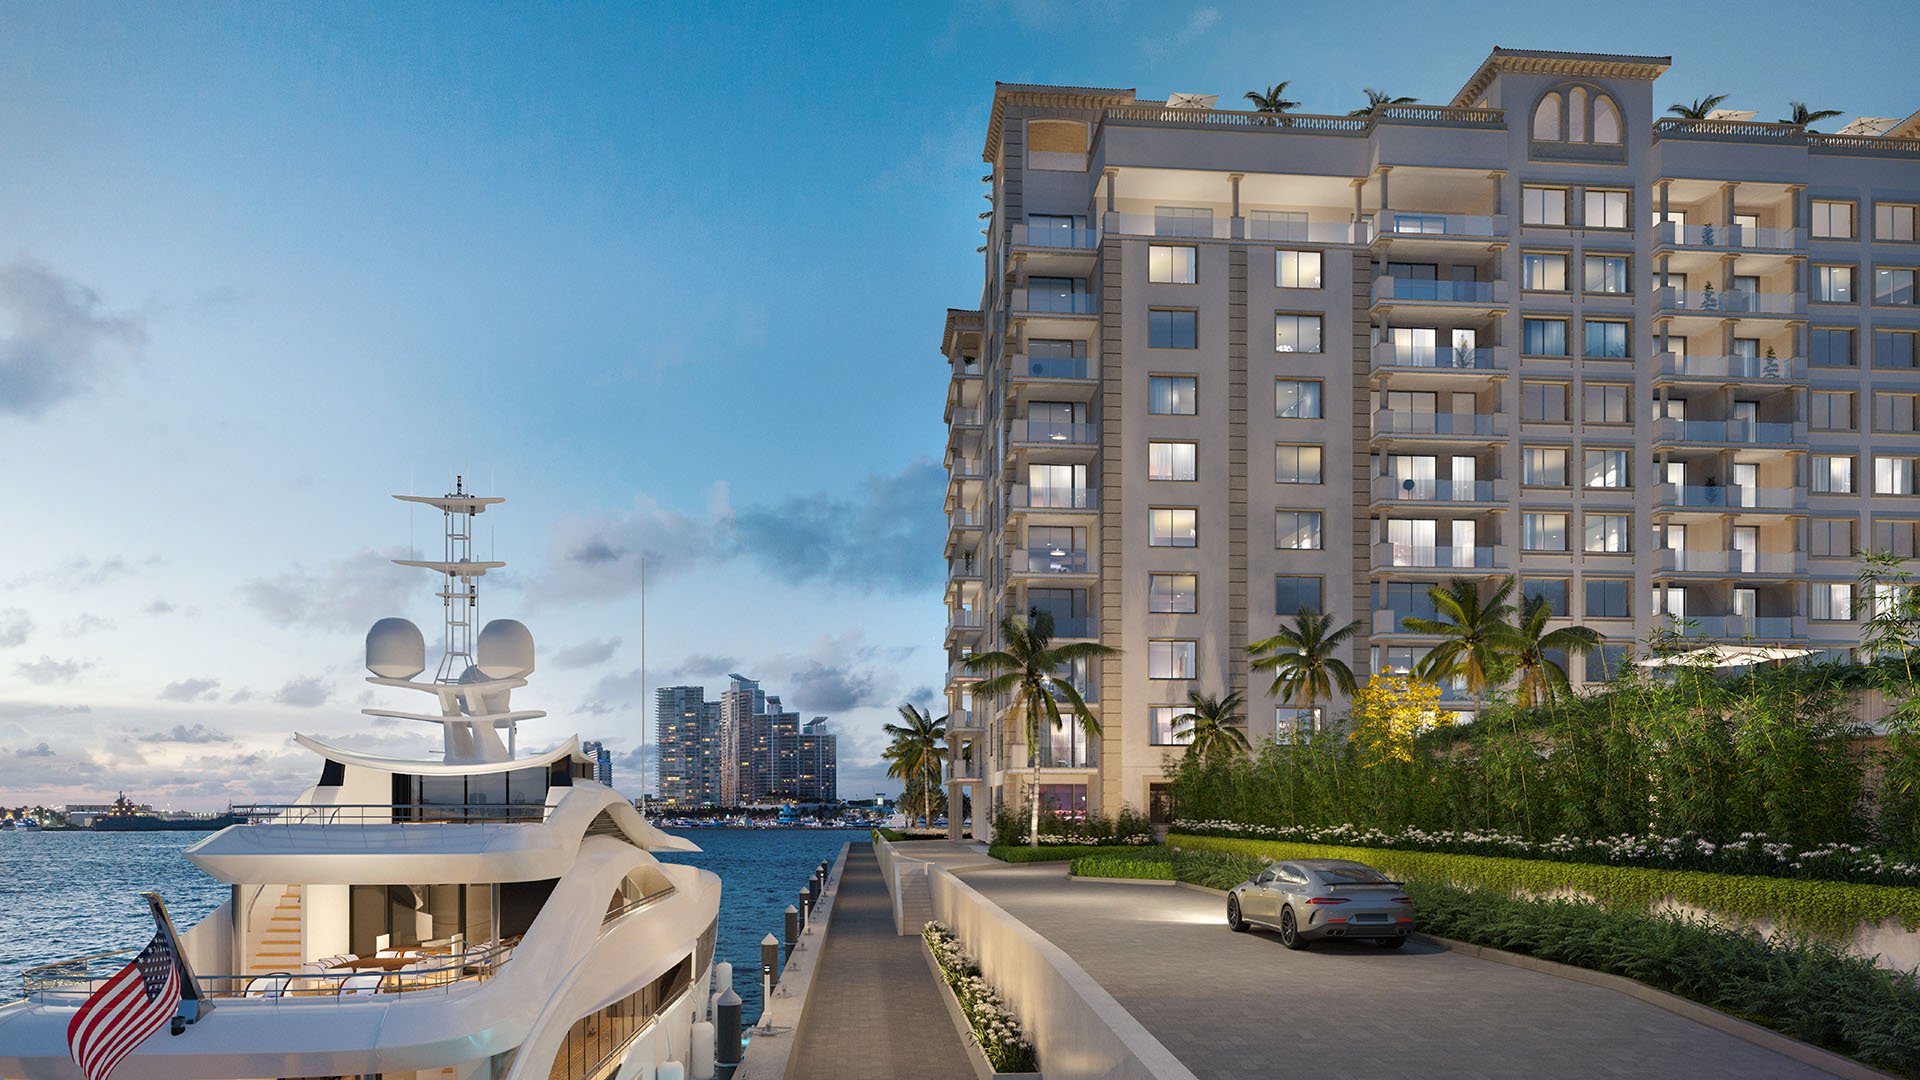
For someone considering Five Park Miami Beach within a Miami Beach search, those financial questions belong alongside the experience of the residence itself. Review any available operating evidence on its own merits, without inferring reserve strength from design, location, or apparent newness.
Recently delivered does not mean financially settled in every respect. A short operating record is not proof that future expenses will remain unchanged. This route may better serve buyers who prefer to review actual financial activity, provided they distinguish available evidence from long-term certainty.
Luxury ownership is easier to evaluate when services are divided into three written categories: included in the regular assessment, mandatory but separately charged, and billed only when used. Access to a service and payment for it are different questions.
Request written confirmation of each service's classification and applicable charges before building a personal ownership budget. A buyer expecting frequent use should evaluate a different spending scenario from one who values availability but anticipates only occasional use. Neither preference is inherently more economical without the actual terms.
If your Coconut Grove shortlist includes Mr. C Tigertail Coconut Grove, apply that distinction to the service documents you receive rather than assuming what is included. The relevant issue is the buyer's obligation, not the impression created by a service description.
Use one consistent calculation across candidates: regular assessments, mandatory separate charges, and anticipated usage-based spending. Determine whether reserves are already included before adding a separate reserve amount. Counting the same contribution twice can distort the comparison as readily as leaving it out.
A reserve balance is meaningful only in relation to the building's identified repair and replacement obligations. A structural integrity reserve study, or SIRS, evaluates major components the association must maintain and establishes anticipated funding needs for their repair or replacement.
Covered Florida residential condominium buildings of at least three habitable stories must undergo a SIRS at least every 10 years. A recently delivered building's age does not, by itself, eliminate reserve obligations. Buyers should establish what applies to the particular association rather than substituting age for analysis.
Read the study and funding plan together. Ask what work is identified, when the funds are expected to be needed, and how the association intends to provide them. The reserve balance alone cannot answer those questions.
Within a Sunny Isles Beach search that includes Bentley Residences Sunny Isles, the same principle holds: assess the applicable reserve documentation independently of the residence's lifestyle appeal. A reserve study is a planning tool, not a guarantee against special assessments.
Milestone inspections and reserve studies answer different questions. Under the 2025 framework, milestone-inspection requirements apply to qualifying residential condominium and cooperative buildings with three or more habitable stories. The initial inspection generally occurs at 30 years, or at 25 years if the local enforcement agency requires an earlier inspection, followed by inspections every 10 years.
Florida's 2025 HB 913 changed the applicable height standard from three stories to three habitable stories. It also extended the SIRS completion deadline for certain associations from December 31, 2024, to December 31, 2025. That extension was not universal.
These distinctions matter: the time remaining before an initial milestone inspection does not establish freedom from reserve obligations. Before a transaction, counsel should confirm applicable deadlines, exceptions, and subsequent legal changes.
Reserve funding need not come exclusively through regular assessments. Subject to statutory requirements and applicable approvals, associations may use special assessments, loans, or lines of credit. The 2025 framework also permits pooled reserve accounts and baseline funding plans subject to statutory requirements.
Ask not only how much is collected each month, but how the association intends to meet its obligations. Review assessment information and any applicable borrowing arrangements alongside the budget, financial statements, reserve study, and inspection findings. A lower recurring payment is not, by itself, evidence of a lower total commitment.
Preconstruction calls for confidence in reviewed assumptions. A recently delivered residence calls for scrutiny of available operating evidence. Both require a clear separation between mandatory ownership costs, discretionary service spending, and future funding exposure.
The stronger choice is the residence whose documents, financial structure, and service obligations align with your priorities-not simply the one with the more attractive monthly number.
For a considered approach to South Florida residential ownership, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Compare the budget assumptions, included services, reserve contributions, and separate charges rather than relying on the quoted monthly assessment.
They generally fund operating expenses such as staffing, management, maintenance, and shared services, along with reserves for future repairs or replacements.
A developer-controlled Florida condominium association cannot vote to waive or reduce required reserves. Buyers should examine the reserve assumptions in the proposed budget.
Request the current budget, available financial statements, reserve studies, applicable inspection findings, and assessment information. Establish how much operating history those records cover.
Obtain written confirmation of which services are included, mandatory but separately charged, or billed only when used. Model anticipated usage separately from mandatory ownership costs.
Determine whether reserve contributions are already included in the quoted regular assessment before adding a separate reserve amount to the ownership estimate.
A SIRS evaluates major building components the association must maintain and establishes anticipated funding needs for repair or replacement. Covered buildings must undergo the study at least every 10 years.
No. Building age alone does not eliminate reserve obligations, and milestone-inspection timing is separate from reserve-study requirements.
No. It is a funding-planning tool, and reserve strength must be evaluated against identified obligations rather than the account balance alone.
Subject to statutory requirements and applicable approvals, associations may use special assessments, loans, or lines of credit. Counsel should confirm the applicable legal framework and any subsequent changes.