A South Florida home purchase should be funded by available liquidity, not an anticipated IPO valuation. Separate contractual restrictions, market exposure, tax costs, and property obligations before committing.
A South Florida residence can be a considered next chapter for a founder, executive, or early investor approaching an IPO. The challenge is not necessarily the scale of the buyer’s wealth, but whether that wealth can become usable cash on the purchase timetable.
Paper wealth is not closing-ready liquidity. A concentrated stock position, a contractual lockup, and an anticipated tax bill are separate planning issues. Collapsing them into one optimistic estimate can leave a substantial balance sheet poorly matched to a property commitment.
For a buyer considering The Residences at 1428 Brickell, the first question is not what the shares might be worth after listing. It is what purchase budget remains comfortable without depending on their immediate sale.
IPO lockups contractually restrict covered shareholders, including insiders, employees, and early investors, from selling shares for a specified period after an offering. Approximately 180 days is common, but it is not a universal promise of liquidity six months after an IPO.
The registration statement and prospectus disclose lockup terms. The applicable agreement warrants individual review: restrictions need not be identical for every shareholder. Exceptions, early-release provisions, or waiver mechanisms may alter the timetable, but none should be assumed simply because another investor expects earlier access.
Ask counsel to identify the restrictions governing the specific shares intended to fund the purchase. Then distinguish the earliest possible release from the date when usable proceeds can prudently be expected.
Lockup expiration is a milestone to investigate, not a guaranteed cash-delivery date. A purchase obligation should not depend on the most favorable reading of an agreement that has yet to be reviewed.
Before selecting a residence, separate available cash and committed financing from projected stock-sale proceeds. Keep that distinction visible throughout the search rather than allowing it to disappear into a single net-worth figure.
A practical planning exercise uses three categories:
Funds already available for the purchase and associated expenses.
Financing whose availability, conditions, and timing have been confirmed.
Expected equity proceeds that remain subject to restrictions, market prices, and taxes.
Only the first two categories should define the budget for a purchase that must proceed independently of the IPO. Evaluate any financing proposal on its actual terms; discussions alone do not make it committed.
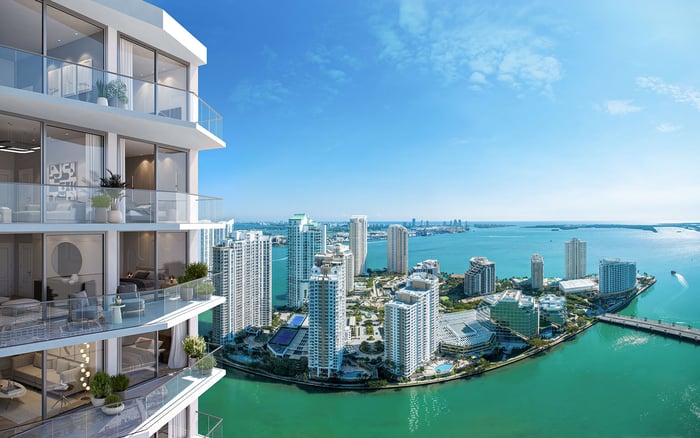
The same discipline applies to a Miami Beach search that includes The Perigon Miami Beach. The residence may fit the buyer’s long-term intentions while its proposed payment schedule does not fit current liquidity. Resolve that mismatch before committing, rather than relying on a future share sale to solve it.
Lockup expiration can increase the supply of shares available for sale and affect the stock price. The IPO price is therefore not a dependable forecast of what a shareholder will ultimately receive. Building a property budget around that price confuses a reference point with realizable proceeds.
Model a less favorable sale price alongside the expected case. Ask whether the purchase could still proceed, whether the household would retain sufficient liquidity afterward, and whether a sale would feel forced. These are planning questions, not predictions about any particular offering.
Next, separate gross proceeds from spendable cash. Selling appreciated shares can generate capital-gains taxes. Florida does not impose a separate individual income tax on stock gains, but federal capital-gains tax and potentially net investment income tax still apply.
Have a tax adviser estimate the applicable liability before allocating equity proceeds to the residence. A Florida purchase does not make a stock sale tax-free, and no uniform tax percentage should replace an individual calculation.
A concentrated stock position exposes wealth to company-specific risk. Diversification can reduce that exposure, but the best risk-management decision is not necessarily the fastest route to purchase cash.
Gradual sales can spread diversification over time rather than require liquidation of the entire position at once. Tax-loss harvesting may help offset realized capital gains where applicable. Gifting may belong in a broader wealth plan, but it should not be confused with funding the buyer’s own closing.
Exchange funds may diversify a position without an immediate taxable sale. Their illiquidity, holding requirements, fees, and tax implications require careful review. They are not automatic sources of a down payment. Hedging may help manage downside risk, but its costs and potentially complex tax considerations also warrant attention.
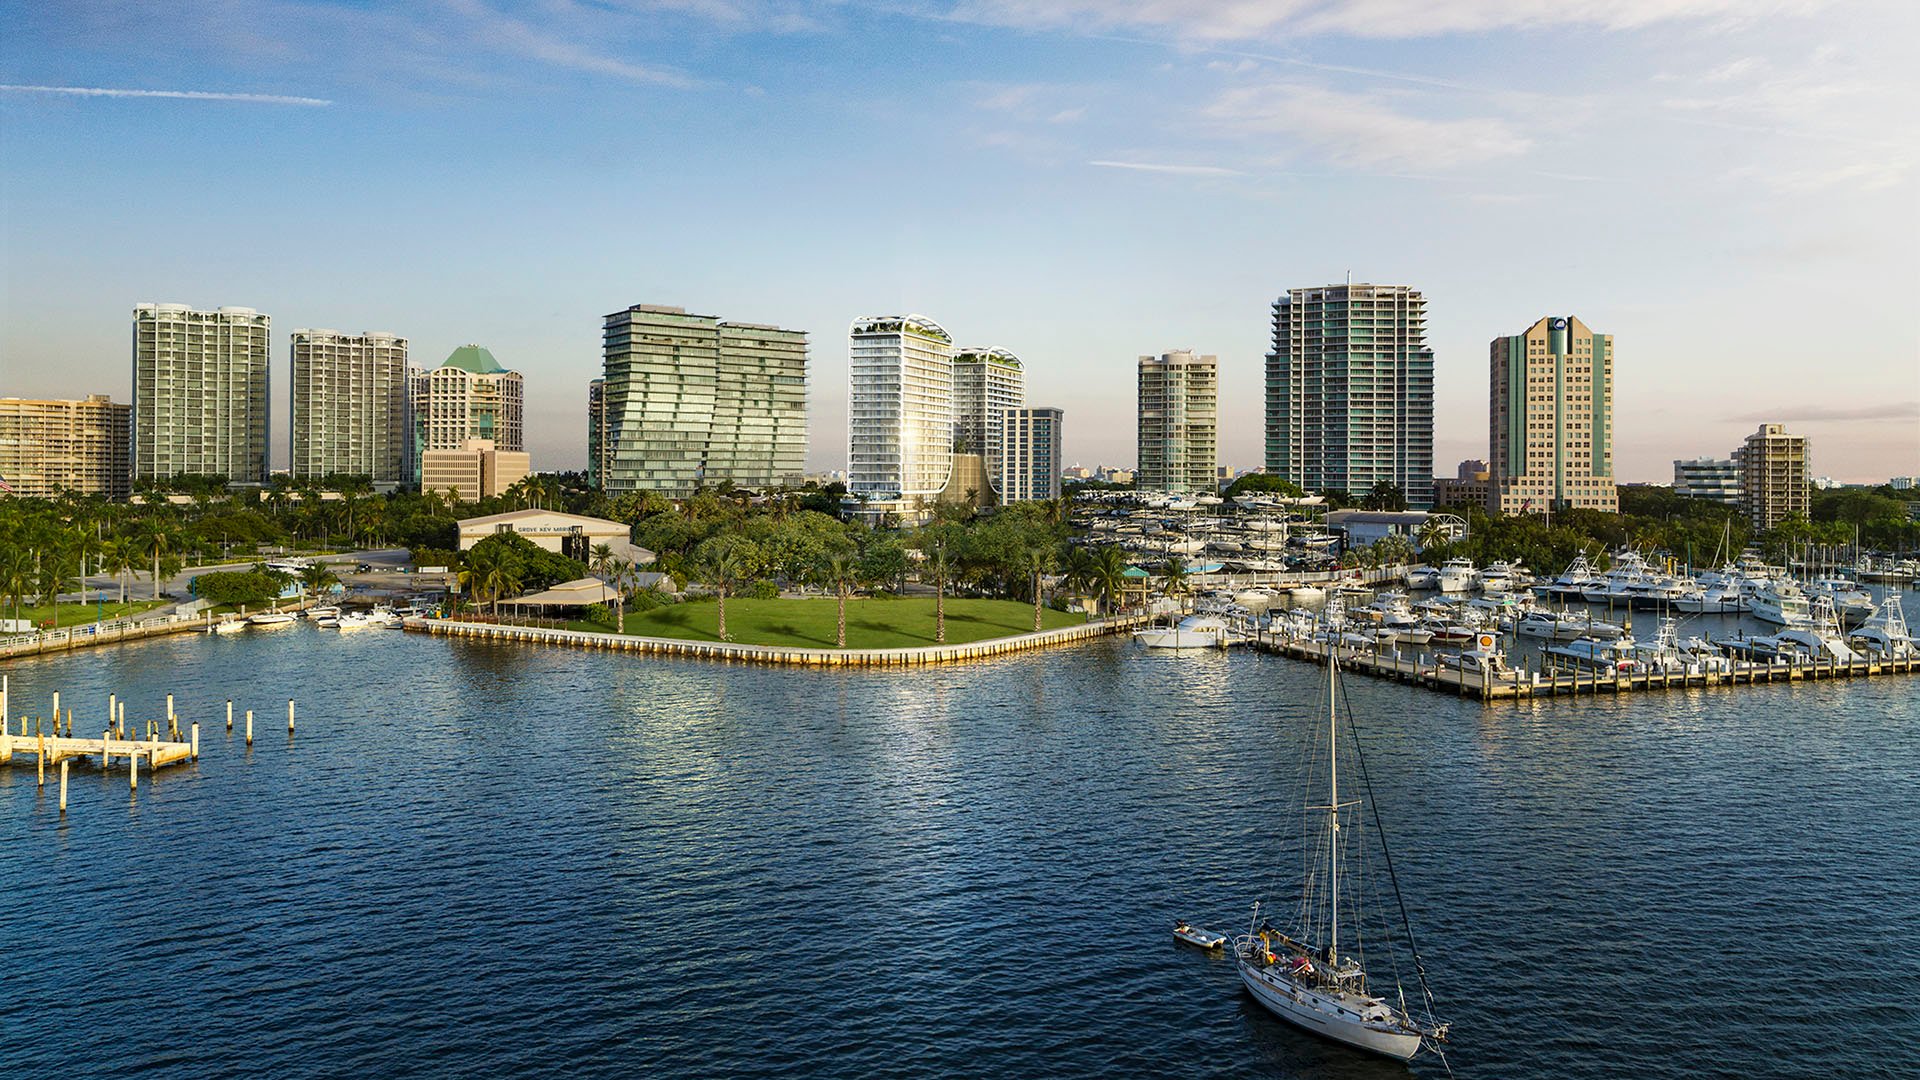
A Coconut Grove search involving Four Seasons Residences Coconut Grove should therefore sit alongside, rather than dictate, the portfolio plan. Ask advisers to distinguish actions that generate cash from those that reduce exposure or introduce new constraints. Those outcomes are not interchangeable.
Florida’s homestead exemption reduces the taxable value of an eligible permanent residence. It eliminates neither the property-tax bill nor federal tax on stock-sale gains.
Eligibility generally requires ownership and permanent-residence status on January 1 of the relevant tax year. The regular application deadline is March 1, with applications submitted to the county property appraiser. Confirm the applicable exemption amount and tax-year rules directly with that office.
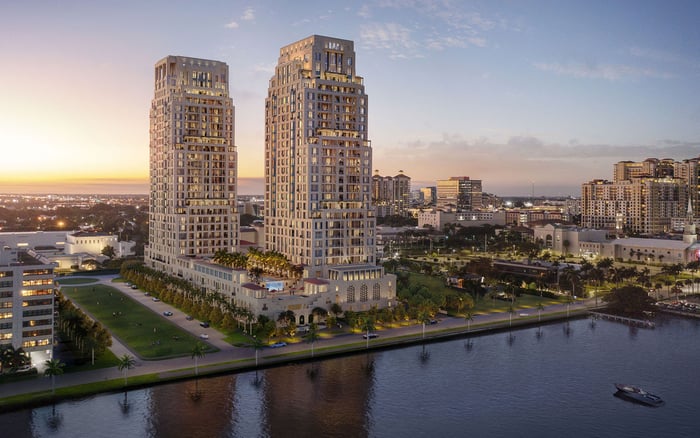
For a buyer evaluating Alba West Palm Beach, this creates a planning calendar separate from the IPO and lockup. Consider eligibility when discussing timing, but do not let an anticipated property-tax benefit justify a purchase dependent on uncertain equity proceeds.
Before signing, bring the purchase agreement, equity restrictions, funding plan, and tax estimate into one coordinated discussion with legal, tax, investment, and financing advisers as applicable. Request a clear account of each payment obligation and the funds intended to meet it.
The decisive test is straightforward: if the lockup lasts longer than expected or the eventual sale price disappoints, does the purchase remain manageable? If not, consider a smaller commitment, a later purchase, or a revised funding structure, subject to professional review and the terms actually available.
The goal is not to postpone a meaningful lifestyle decision indefinitely. It is to preserve choice, allowing the residence to serve the buyer’s life without requiring a favorable market outcome to make the transaction work.
Explore South Florida residences with MILLION while keeping your property ambitions aligned with a carefully reviewed liquidity plan.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationShares subject to a lockup should not be treated as immediately available sale proceeds. Separate available cash and confirmed financing from equity that remains restricted.
Approximately 180 days is common, but the actual duration and release provisions depend on the applicable agreement.
Not necessarily. Review the registration statement, prospectus, and applicable agreement to understand the restrictions affecting your shares.
No. It is a milestone to investigate rather than a guaranteed date for usable proceeds, and the eventual sale price remains uncertain.
Lockup expiration can increase the supply of shares available for sale and affect the stock price. The IPO price is not a dependable forecast of eventual proceeds.
Florida does not impose a separate individual income tax on stock gains. Federal capital-gains tax and potentially net investment income tax still apply.
Yes, gradual sales can spread diversification over time. Their suitability depends on sale restrictions, tax costs, and the buyer’s liquidity needs.
Not automatically. They may provide diversification without an immediate taxable sale, but illiquidity, holding requirements, fees, and tax implications require review.
Hedging may help manage downside risk, but it introduces costs and potentially complex tax considerations. It is not automatically a source of closing funds.
Eligibility generally requires ownership and permanent-residence status on January 1, and the regular application deadline is March 1. Confirm the applicable rules with the county property appraiser.