An installment sale can support a Florida relocation, but the residence budget should reflect after-tax receipts, continuing ownership costs and payment risk, not simply the size of the first check.
A Florida relocation can feel financially settled when the first installment payment arrives. Yet that payment is only one part of a longer transaction. For a buyer choosing a South Florida residence, the more useful question is not how much cash has arrived, but how much remains after taxes, transaction expenses and a deliberate liquidity reserve.
The residence should fit both the cash available at closing and the reliable after-tax income available afterward. A substantial first receipt does not, by itself, establish the capacity to support years of property taxes, insurance, association charges and maintenance. That distinction matters whether the search centers on Brickell, Miami Beach or a quieter address farther north.
An installment sale generally involves receiving at least one payment after the tax year in which the sale occurs. Under the installment method, qualifying gain is generally recognized as payments arrive rather than entirely in the year of sale. This changes the timing of a tax liability; it does not eliminate it.
A receipt may include principal and interest. Within principal, part may represent a return of basis and part taxable gain. The gain portion is generally calculated by multiplying the principal payment, excluding interest, by the sale’s gross-profit percentage. Interest is reported separately and belongs on its own line in the cash-flow model.
Before treating proceeds as purchasing power, have the tax adviser confirm eligibility, basis, depreciation recapture, interest treatment and estimated-tax obligations. A seller may elect out of installment reporting, changing when gain is recognized; the method also cannot be used to report a loss. Resolve these questions before the residence budget becomes a binding commitment.
The first budget is for acquisition. Begin with the initial installment actually received, then subtract sale-related obligations still payable, residence closing and relocation costs, tax reserves and liquidity reserves. The balance is cash potentially available for the purchase, not an automatic spending target.
The second budget is for ownership. Compare the residence’s full annual cost with reliable after-tax installment receipts and any other dependable resources. Model actual payment dates rather than smoothing an annual receipt into twelve imaginary monthly deposits. Housing bills must be payable when due, even when the next installment is months away.
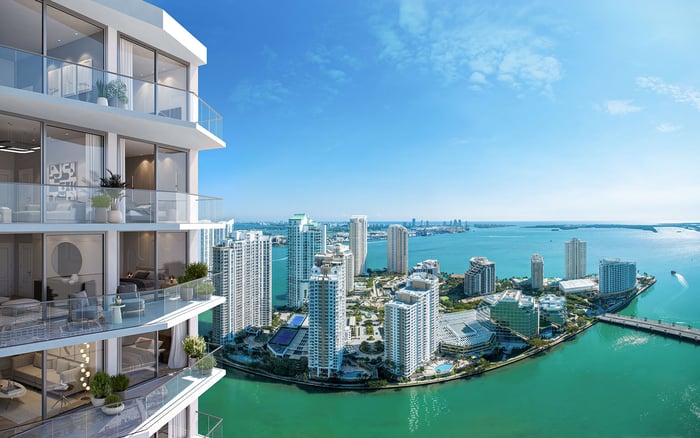
For a residence under consideration at The Residences at 1428 Brickell, this means evaluating the proposed purchase alongside a separate operating reserve. The address may define the search; it should not determine how much of the first payment can safely be committed.
Keep acquisition cash and continuing ownership reserves visibly separate. Otherwise, the same dollar can appear twice in the plan: first as available closing funds, then as the cushion intended to cover next year’s expenses.
The purchase price is only the beginning of the residence budget. Include property taxes, homeowners insurance, applicable flood insurance, association fees, maintenance, utilities, debt service and any staffing. Obtain property-specific figures wherever possible, and distinguish recurring expenses from one-time improvements or purchases.
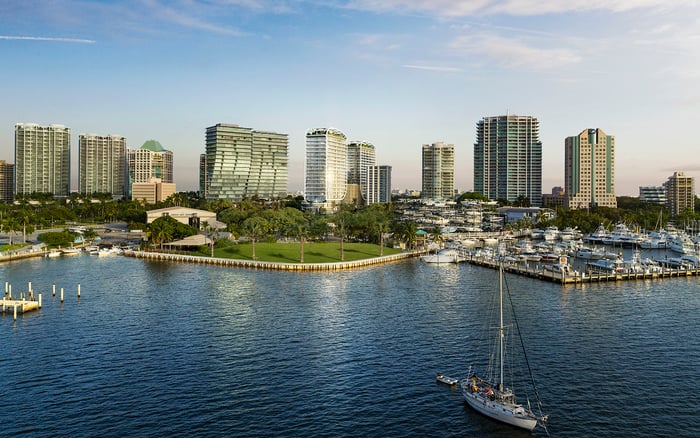
A Coconut Grove search that includes Four Seasons Residences Coconut Grove calls for the same financial discipline as any other candidate: review the relevant documents, request current cost information and identify expenses that remain uncertain. A project’s name or positioning is no substitute for an ownership budget.
For a Miami Beach option such as The Perigon Miami Beach, keep insurance, association obligations and potential special assessments as explicit review items. These are diligence categories, not assertions about that property. The goal is a consistent comparison across residences, with unresolved costs clearly identified before funds are committed.
The seller’s current property-tax bill can be a poor guide to the buyer’s future bill. An ownership change can reset the assessment and remove the seller’s exemptions. The prior owner’s homestead exemption is generally removed in the following tax year, so the current bill should not simply carry into the buyer’s forecast.
Florida’s homestead exemption reduces the taxable value of an eligible permanent residence. It is not a dollar-for-dollar reduction in the tax bill. Eligibility and the expected assessment therefore belong in the property-specific estimate, not as an assumed discount against annual expenses.
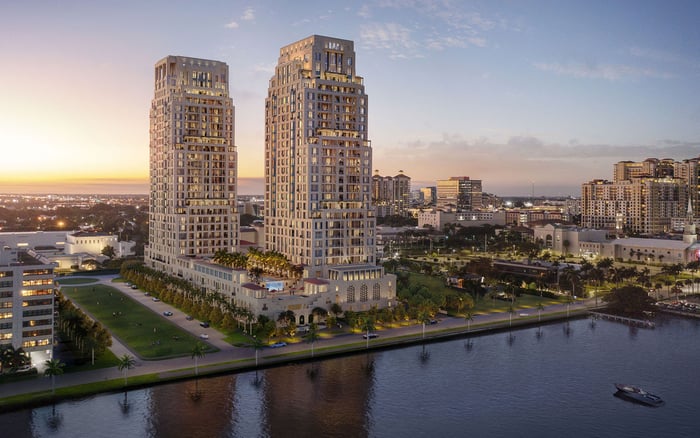
The same discipline applies to a West Palm Beach search that includes Alba West Palm Beach. Build the tax estimate around the contemplated purchase and the buyer’s circumstances, not another owner’s historical treatment.
For an eligible owner moving between Florida homesteads, portability may transfer some or all of the accumulated Save Our Homes assessment difference. The portable benefit is the eligible difference between the former home’s market value and assessed value, not the homestead exemption itself. The maximum transferable assessment difference is $500,000, subject to eligibility rules.
An existing exemption does not simply move to the replacement residence. The process generally requires a new homestead application and a portability application, using Forms DR-501 and DR-501T. Confirm the applicable March 1 filing deadline before relying on portability in the budget.
Eligibility also depends on a limited period tied to the previous qualifying homestead, not merely the former property’s closing date. Confirm the timing before relying on the benefit in the budget. For someone relocating from outside Florida, portability is not a mechanism for importing an out-of-state assessment benefit.
A residence budget should remain workable when events depart from the payment schedule. Model delayed installments and buyer default, then identify which liquid resources would cover fixed housing costs. Have counsel review the note’s security and default provisions rather than treating scheduled payments as equivalent to cash already held.
Also test an early payoff, insurance increases, major repairs and special assessments. These are planning scenarios, not forecasts. An early payoff warrants a fresh tax projection before the additional cash is treated as available for a larger home or discretionary improvements.
The strongest relocation plan leaves room to enjoy the residence without depending on every payment arriving precisely on schedule. For a discreet conversation about aligning your South Florida home search with that budget, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationAn installment sale generally involves receiving at least one payment after the tax year in which the sale occurs. Eligibility for installment reporting requires transaction-specific review.
No. Reserve for applicable taxes, outstanding transaction obligations, closing and relocation costs, and liquidity before determining the amount potentially available for the residence.
The principal payment, excluding interest, is generally multiplied by the sale’s gross-profit percentage. Interest is reported separately from installment-sale gain.
No. It generally defers recognition as payments arrive rather than eliminating the associated tax liability.
Yes, a seller may elect out, changing when gain is recognized for tax purposes. Review that decision with a tax adviser before setting the residence budget.
Include property taxes, homeowners and applicable flood insurance, association fees, maintenance, utilities, debt service and any staffing.
Not reliably. Ownership changes can reset the assessment and remove the seller’s exemptions, so buyers should obtain a property-specific estimate.
No. It reduces the taxable value of an eligible permanent residence rather than providing an equivalent dollar reduction in taxes owed.
Eligible owners moving between Florida homesteads may transfer some or all of their Save Our Homes assessment difference, up to $500,000 subject to eligibility rules. It does not transfer an out-of-state assessment benefit.
Portability generally requires Forms DR-501 and DR-501T for the new homestead and portability applications. Confirm the applicable March 1 filing deadline and eligibility timing before relying on the benefit.