A disciplined approach to a Cora Merrick Park condominium resale separates document review, estoppel verification, and any required association approval, with contractual deadlines and remedies established before closing.
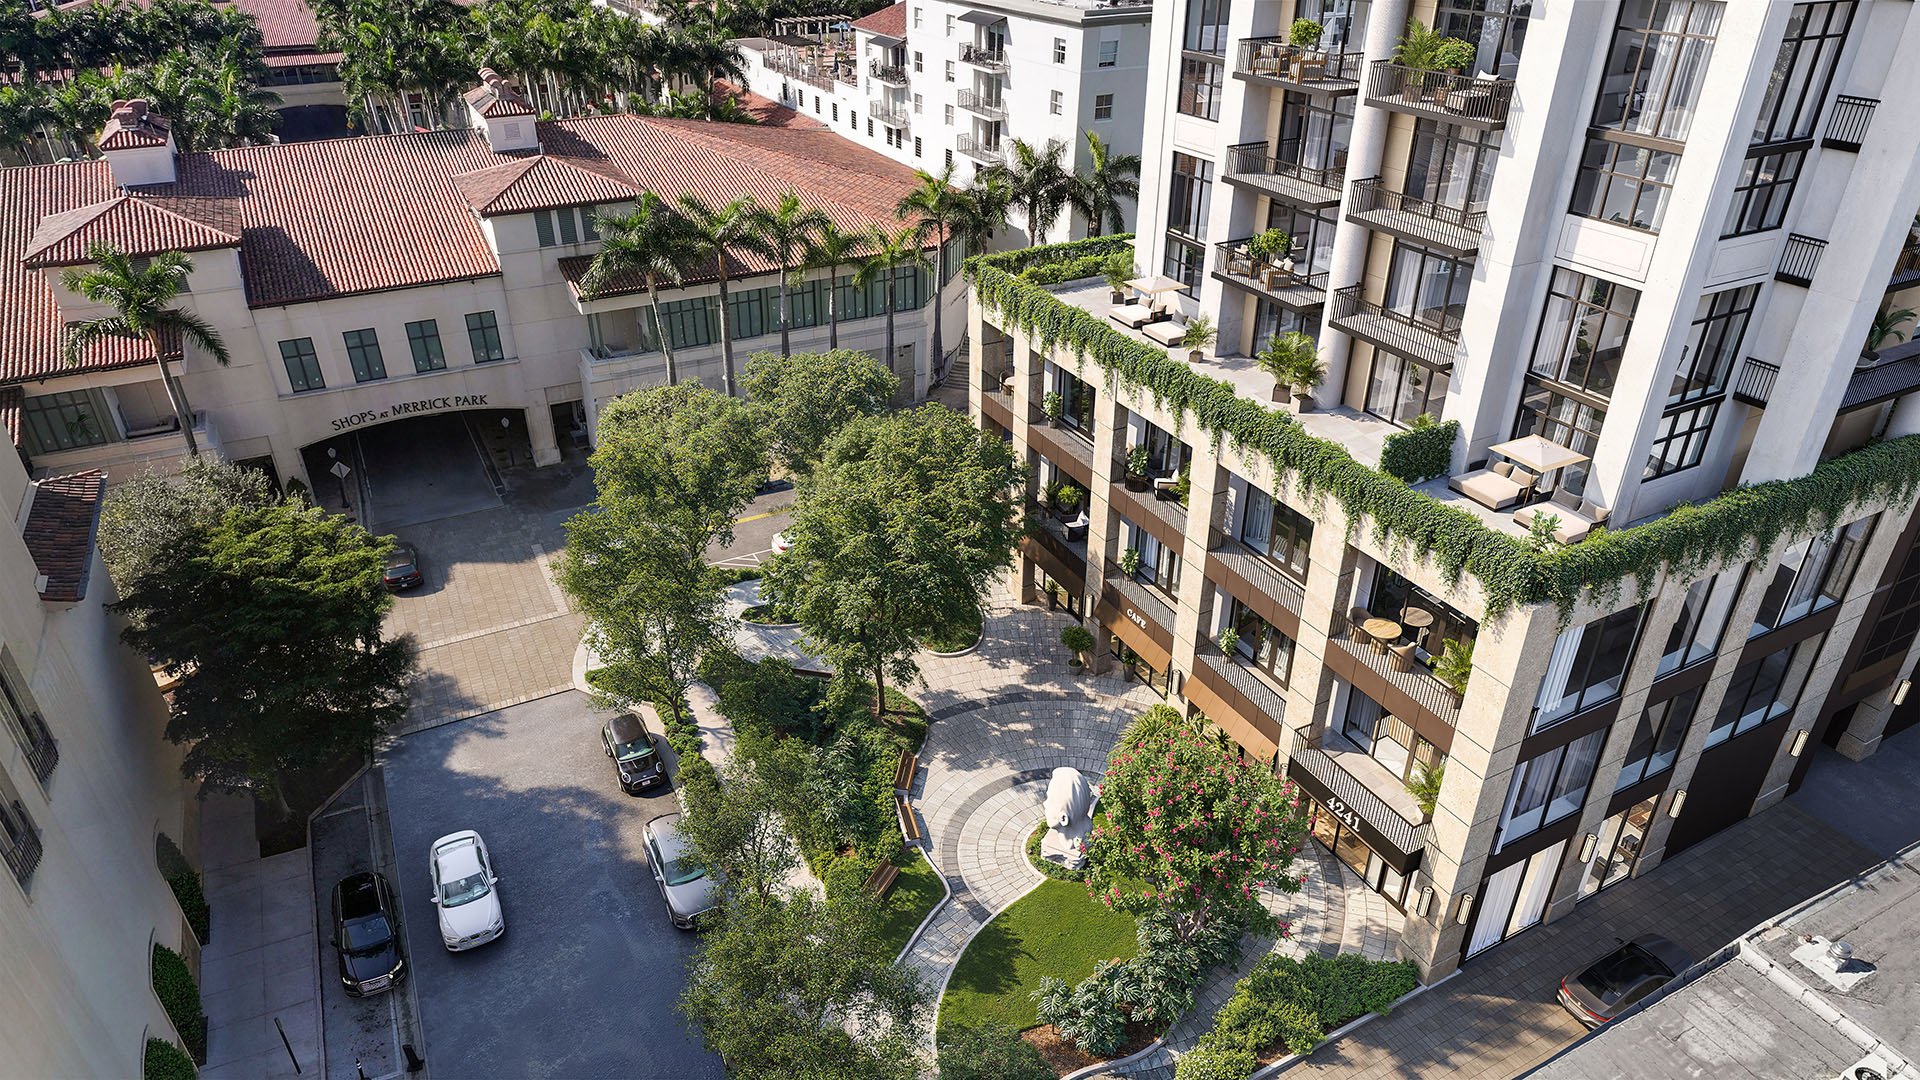
For a buyer considering a condominium resale at Cora Merrick Park, confidence at closing begins with three distinct requirements: the resale documents, the unit’s estoppel certificate, and any required association approval. Each answers a different question. The governing documents define the ownership framework; the estoppel addresses unit-specific financial and transfer information; approval, if required, confirms that the transfer has cleared the association’s process.
In Coral Gables, a residence’s appeal should be matched by precision in the purchase contract. Receipt of one document does not establish that every closing condition has been satisfied. A paid-up account does not resolve an open violation, and an application submitted to management is not written approval.
Before waiving contingencies, confirm Cora’s actual requirements through the recorded declaration, bylaws, current application package, management, and closing counsel. Do not assume a particular fee, interview requirement, board calendar, or processing time.
A residential condominium resale seller has no fixed statutory deadline for delivering the condominium documents. An express contractual deadline is therefore important: the agreement should identify what must be delivered, when delivery is due, and how receipt will be documented.
Separate governing and disclosure documents from the broader financial review materials. Have counsel identify the applicable statutory documents and contractual requirements, then request the association’s budget, reserve information, financial records, meeting minutes, and assessment notices for substantive review.
The statutory nondeveloper disclosure provision includes a seven-business-day cancellation period. Counsel should verify its applicability, the required documents, the contract wording, and the deadline calculation. Do not treat it as an unrestricted seven-day right that begins whenever a buyer chooses to review the file.
If your search also includes Ponce Park Coral Gables, distinguish the transaction type before applying a resale checklist. This framework concerns condominium resales; it does not assume that every purchase follows the same disclosure rules.
Under Florida condominium law, an association generally must issue an estoppel within 10 business days after receiving a written or electronic request from the owner, the owner’s designee, or a mortgagee or its designee. That issuance rule does not govern delivery of the entire resale package.
An estoppel delivered by hand or electronically generally remains effective for 30 days; one sent by regular mail generally remains effective for 35 days. Coordinate the request and issuance with the anticipated closing date rather than ordering the certificate without regard to the transaction calendar.
The contract should specify who orders the certificate and who pays for it. Counsel should also track the request date, delivery method, and effective period. If closing moves beyond that period, request an updated certificate rather than assuming the original remains usable.
Second-home buyers coordinating travel or a remote closing should keep these deadlines in view. A change in the closing date should trigger a fresh check of document review, estoppel effectiveness, and approval status-not merely a revised appointment.
The estoppel should disclose assessments and other amounts owed, along with relevant scheduled charges and special-assessment information. Reconcile those entries with the proposed settlement statement, including the contractual allocation of unpaid charges and assessments between buyer and seller.
Open violations identified in association records require separate attention. A certificate showing no outstanding balance does not confirm that there are no disclosed violations. Ask what each violation concerns, what remains to be done, and how responsibility will be resolved before closing.
The certificate must also state whether association rules require board approval for the transfer and, if so, whether approval has been granted. Treat that disclosure as a separate checkpoint, not a footnote to the financial figures.
An association may issue an amended estoppel when an error or additional information becomes known during the effective period, subject to statutory conditions concerning delivery and whether closing has occurred. If figures or disclosures conflict, have closing counsel reconcile them and obtain a corrected certificate before closing. An informal explanation is no substitute for a consistent closing file.
First establish whether approval is required at Cora. If it is, obtain the current application package and confirm the required submissions, authorized fees, and procedural steps directly with management. A transfer-approval fee may be charged only when approval is required and the fee is authorized by the declaration, articles, or bylaws.
The buyer’s contract should make closing contingent on written association approval by a stated deadline. It should also address denied, delayed, or conditional approval, including any negotiated extension, cancellation, and deposit-return rights. These protections are contractual recommendations, not automatic rights created by the estoppel.
Have counsel define the response to each outcome. A pending application is not completed approval. Conditional approval should prompt review of the condition before the buyer commits to proceed. If timing slips, the agreement should provide a clear path rather than leave the parties to negotiate under closing pressure.
The estoppel is essential, but it does not replace a review of the association’s broader financial position. Examine budgets, reserves, financial records, meeting minutes, and assessment notices together. Ask separately about proposed special assessments and planned repair or inspection work.
A current unit balance does not protect a buyer against future charges. The practical distinction is between amounts disclosed for the unit and possible obligations arising from association decisions. Counsel should help determine what needs clarification and what the purchase agreement must allocate.
The same discipline applies when comparing a prospective resale in Coconut Grove, including one at Park Grove Coconut Grove. Evaluate each association’s own records and requirements; do not carry conclusions about finances or approval procedures from one property to another.
Before releasing funds, have counsel confirm that the applicable document-review deadlines have been addressed, the estoppel remains effective, the settlement statement matches its disclosures, and any required written approval has been obtained. Confirm how the contract allocates unpaid charges, disclosed assessments, and pre-closing violations.
The objective is not more paperwork for its own sake. It is a purchase in which timing, financial obligations, and permission to transfer are understood before closing-preserving the discretion and certainty a considered acquisition deserves.
For a considered approach to South Florida luxury ownership, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Governing documents explain the association’s rules, while the estoppel provides unit-specific financial and transfer information.
The association generally has 10 business days after receiving a written or electronic request from an eligible owner, mortgagee, or their designee.
It generally remains effective for 30 days when delivered by hand or electronically, or 35 days when sent by regular mail. Coordinate that period with closing.
No. Establish separate contractual deadlines for resale-document delivery and review rather than relying on the estoppel issuance rule.
Counsel should confirm the applicable statutory documents, contract wording, and deadline calculation under the nondeveloper disclosure provision.
Review assessments, other amounts owed, relevant scheduled charges, and special-assessment information. Have counsel reconcile those disclosures with the settlement statement.
No. Open violations identified in association records must be reviewed separately from the unit’s financial balance.
Confirm the requirement through the recorded declaration, bylaws, current application package, management, and counsel. The estoppel must disclose whether approval is required and, if so, whether it has been granted.
Make closing contingent on written approval by a stated deadline and negotiate remedies for denial, delay, or conditional approval. Extension, cancellation, and deposit-return rights should not be assumed.
No. Review budgets, reserves, financial records, minutes, and assessment notices, and ask separately about proposed assessments and planned repair or inspection work.