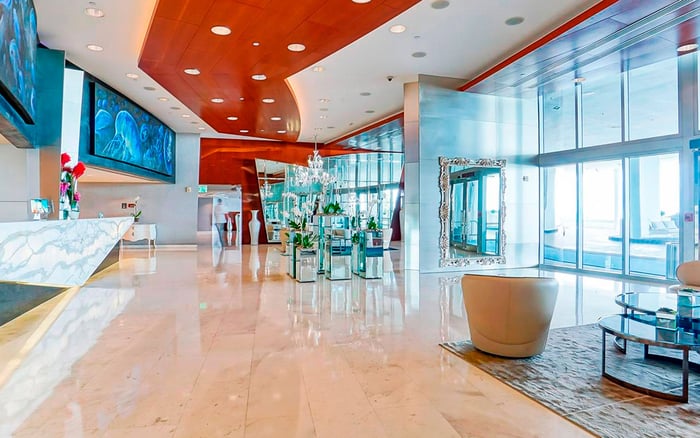
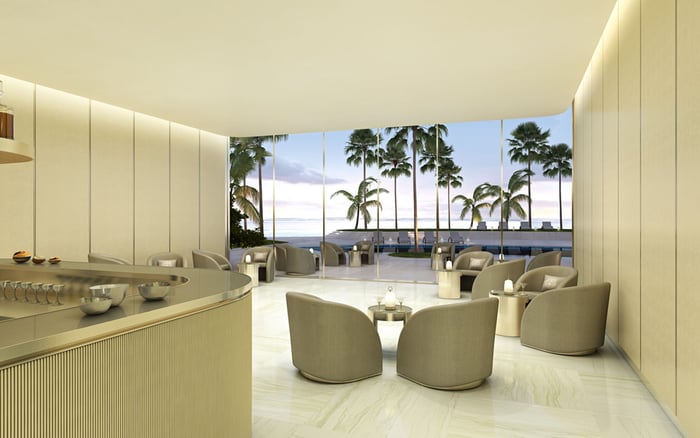
Five Sunny Isles Beach addresses offer distinct approaches to privacy and service. This buyer-oriented shortlist pairs their lifestyle appeal with the reserve, insurance, and capital-planning questions that should precede a purchase.
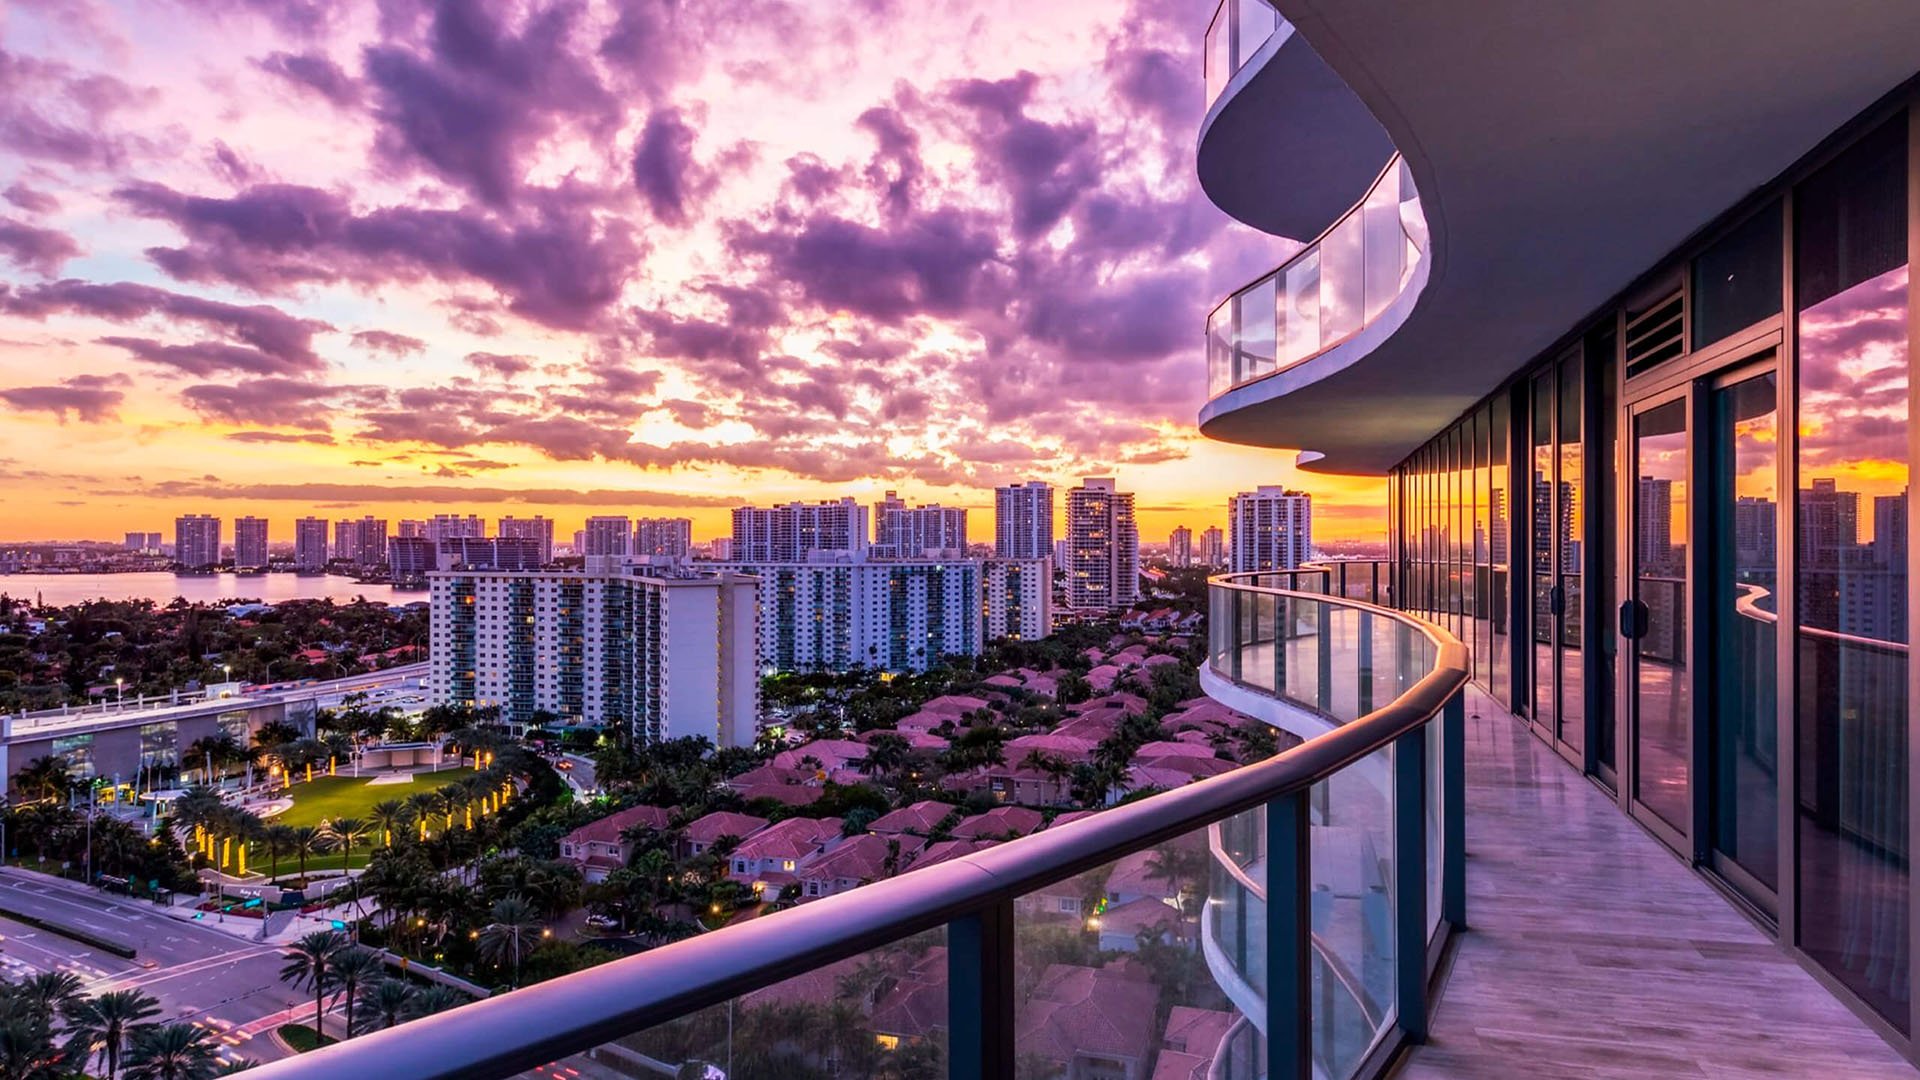
In Sunny Isles Beach, the most persuasive luxury purchase is not necessarily the residence with the longest amenity menu. For buyers seeking discretion and full-service living, the deeper appeal is a home that feels effortless day to day, with ownership obligations they can understand. Privacy, attentive service and financial clarity belong in the same conversation.
The five projects below offer distinct expressions of that proposition: an expansive two-tower setting, a relatively recent luxury building, a notably small full-floor community, an automobile-centered residential concept and an Acqualina-associated amenity environment. Their order is a lifestyle screening sequence-not a verified ranking of reserve strength, insurance quality or protection from special assessments. None should be treated as assessment-proof.
For buyers considering The Estates at Acqualina Sunny Isles, the essential distinction is between the experience being purchased and the association obligations that accompany it. A compelling residence warrants an equally careful review of the building behind it.
1. The Estates at Acqualina - Two oceanfront towers
The Estates takes first position for its Acqualina-associated luxury-service positioning and substantial two-tower setting. Approximately 502 linear feet of beachfront establish its physical scale, while its recreational offering includes an ice-skating rink. It is a candidate for buyers who want an extensive private residential environment rather than a tightly edited amenity collection.
Residential inventory is approximately 245 to 248 homes, with the exact count requiring tower-level confirmation. Address references include 17885 and 17901 Collins Avenue. Before comparing carrying costs, identify the relevant tower, legal condominium entity and allocation of shared expenses. The breadth of amenities makes capital planning particularly important to examine; it does not establish whether reserves are strong or weak.
2. Turnberry Ocean Club Residences - Approximately 154 residences
At 18501 Collins Avenue, Turnberry Ocean Club Residences combines approximately 154 residences with completion around 2020. Its second-place position reflects relatively recent construction and a smaller luxury ownership community than the Estates' overall residential count.
For buyers who prefer a more contained ownership setting, it merits close consideration. Completion date, however, is not a financial credential. The purchase decision should rest on current reserve funding, insurance terms and the capital-project schedule-not an assumption that newer construction eliminates future assessments.
3. Regalia - 39 full-floor residences
Regalia, at 19575 Collins Avenue, offers this group's clearest privacy proposition by residence format: just 39 full-floor homes in a 45-story oceanfront building completed in 2014. Its third-place position emphasizes residential seclusion, not an asserted advantage in association finances.
A very small ownership community warrants close attention to the allocation of common obligations. Buyers should establish the residence's actual share of expenses and any approved or contemplated work. A limited number of homes can be attractive for privacy, but it does not independently demonstrate lower assessment exposure.
4. Porsche Design Tower - Vehicle access to private sky garages
At 18555 Collins Avenue, Porsche Design Tower has approximately 132 residences and a distinctive vehicle-elevator concept that takes residents' cars directly to private sky garage spaces associated with their homes. For buyers drawn to that arrival experience, the concept is a meaningful differentiator.
Its fourth-place position recognizes this specialized residential format. The same systems warrant a separate maintenance discussion: request service arrangements, planned replacement work and the associated reserve assumptions. Architectural differentiation and maintenance predictability should be evaluated together, without allowing one to obscure the other.
5. The Mansions at Acqualina - Extensive indoor and outdoor amenities
The Mansions at Acqualina, at 17749 Collins Avenue, rounds out the shortlist with 11 private outdoor sanctuaries and 13 indoor amenity areas. Its positioning includes an amenity-rich pool deck, extensive public spaces and world-class services, making it relevant to buyers who prioritize a service-intensive residential experience.
The financial question is how that experience is sustained. Separate recurring service costs from future capital obligations, and examine plans for maintaining amenity spaces over time. Its Acqualina association should neither substitute for property-specific diligence nor be used to infer a construction date from another Acqualina property.
A reserve balance is meaningful only in relation to the work it is intended to fund. Request the current budget, financial statements, reserve studies and capital-project plan. Compare scheduled expenditures with available reserves and planned contributions, then ask how any identified funding gap would be addressed.
For Turnberry Ocean Club Residences, as for every building on this shortlist, reserve review should remain independent of the appeal of relatively recent completion. The central question is whether the funding plan aligns with the building's identified obligations.
A structural integrity reserve study is an important diligence document for covered components and recommended funding. Examine applicable inspection findings for required work and its financial implications. The 2024 Florida statutory framework distinguishes capital and deferred-maintenance reserves from ordinary operating expenses; buyers should have counsel confirm current requirements rather than rely on historical deadlines or funding rules.
Insurance transparency requires more than confirmation that a policy exists. Request current declarations and relevant policy terms, then review coverage limits, deductibles, exclusions, renewal dates and claims history with a qualified insurance adviser. Establish what the association insures and what protection the residence owner needs separately.
The decision is particularly personal at Regalia Sunny Isles Beach, where the full-floor format may be the central attraction. That privacy benefit does not explain how uninsured costs or deductibles would be funded or allocated. Those questions belong in the purchase review, not after closing.
Reducing surprise assessment exposure is an objective, not a promise. Obtain assessment disclosures, inspection findings, planned-work schedules and relevant board minutes. Distinguish approved assessments from projects still under discussion, and ask whether budgets, reserve schedules and insurance assumptions tell a consistent story.
Then compare the five candidates on two separate tracks: the residence's fit for private, service-oriented living and the association's documented financial position. An extensive amenity offering may justify its carrying cost for one buyer; a full-floor format may matter more to another. Neither preference establishes financial safety.
The best match is the address where the desired lifestyle and the documented ownership obligations are equally clear.
Explore a more considered approach to South Florida luxury ownership with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. It is a lifestyle screening order, not a verified comparison of reserve strength, insurance quality or special assessment risk.
Its first-place position reflects its Acqualina-associated luxury-service positioning and two-tower oceanfront format. Financial suitability still requires tower-specific association diligence.
Residence counts range from approximately 245 to 248. Confirm the inventory, tower address and legal condominium entity for the home under consideration.
Completion around 2020 does not establish lower assessment risk. Current reserves, insurance terms and capital plans remain essential to the purchase review.
Regalia has just 39 full-floor residences in a 45-story oceanfront building. That format supports its privacy appeal but does not establish financial safety.
Its vehicle-elevator and private sky garage concept warrants focused review of specialized-system maintenance, service arrangements and reserve assumptions.
Its amenity offering includes 11 private outdoor sanctuaries and 13 indoor amenity areas. It also emphasizes an amenity-rich pool deck, extensive public spaces and world-class services.
Review current budgets, financial statements, reserve studies, inspection findings and capital-project plans. Compare available funding and planned contributions with identified obligations.
Review coverage limits, deductibles, exclusions, renewal terms and claims history with a qualified insurance adviser. Clarify which exposures remain the residence owner's responsibility.
No such guarantee is established. Assessment disclosures, planned work, reserve funding and insurance terms should be reviewed before purchase.