A revised completion date deserves more than a calendar update. Buyers should reconcile deposit obligations, negotiate clear payment notices, confirm dollar availability, and document liquidity needs before accepting an extension.
A delayed completion date changes more than the expected arrival of furniture. For a South Florida luxury buyer, it can shift when capital must be available, extend the need for temporary accommodations, and disrupt the alignment of an overseas transfer with the purchase timetable. The negotiating objective is not simply a later date. It is a written connection between the revised schedule and every obligation attached to it.
Organize the discussion around four records: a reconciled deposit calendar, a proposed payment-notice protocol, a currency-conversion plan, and a short-term liquidity schedule. These are recommendations for buyer documentation, not automatic statutory entitlements. Counsel should distinguish existing contractual obligations from protections that require the seller's agreement.
Start with the executed purchase agreement, every amendment, payment notice, wire confirmation, and escrow acknowledgment. Consolidate them into a single schedule showing each installment's amount, contractual trigger, original due date, payment status, and proposed revised treatment. Where an obligation depends on a construction event rather than a calendar date, preserve that distinction.
Do not assume a completion extension also extends an earlier deposit deadline. Ask counsel to identify which obligations move, which remain unchanged, and whether any notice already delivered remains operative. The proposed amendment should address each point expressly.
Request documentation of the applicable escrow arrangements and the contractual provisions governing permitted use of deposits. Ask counsel to confirm the statutory protections and exceptions applicable to each installment rather than assuming all funds remain untouched until closing.
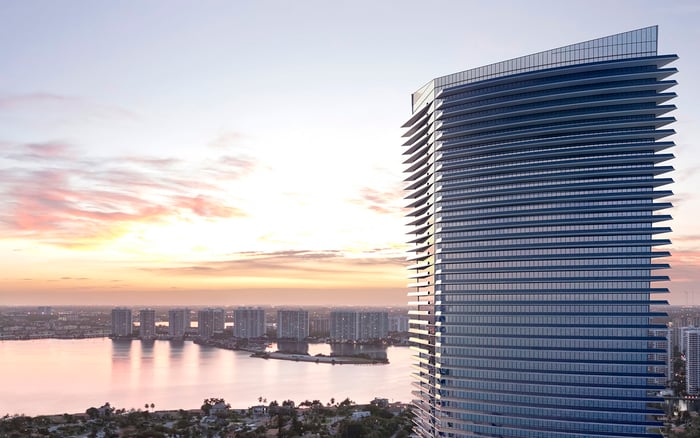
For a buyer evaluating The Residences at 1428 Brickell, this is a contract-review framework, not a statement about the project's timing or terms. The same distinction applies to every residence referenced here.
The phrase capital call should not obscure the payment being requested. Identify whether the demand concerns a purchase-contract installment, funding into the buyer's acquisition entity, or an association assessment. Keep these obligations in separate records, with the document authorizing each payment attached.
For purchase payments, propose a written notice protocol specifying the amount, contractual basis, triggering event, due date, intended recipient, and supporting evidence. Document who must receive the notice, how delivery is established, and who on the buyer's advisory team confirms that funding is ready.
Any requested lead time is a negotiated protection. No universal notice period is established here, and a buyer should not assume that a preferred administrative window overrides an existing contract. When negotiating an extension, ask counsel to address notice mechanics alongside the new date.
For a Miami Beach search that includes The Perigon Miami Beach, the useful question is whether the agreement defines each payment trigger clearly enough to prepare funds without relying on informal updates.
For an international buyer, wealth held abroad is not the same as dollars ready for a payment milestone. Plan for capital to be accessible and convertible into U.S. dollars in time for each obligation, allowing for potential processing delays.
Prepare a funding record identifying the source currency, intended dollar payment, account from which funds will move, and institution handling conversion. Ask that institution to confirm its processing requirements, expected timing, and applicable charges. Record the answers rather than assuming a transfer speed.
If completion shifts, revisit the conversion plan with the buyer's financial advisers. Document which funds are already dollar-denominated, which remain exposed to currency movements, and when the plan will next be reviewed. No fixed currency buffer or particular conversion strategy suits every buyer. The objective is a documented path to available dollars, not an exchange-rate forecast.
Keep a personal liquidity reserve distinct from money already committed to the purchase. Build a schedule of potential cash needs during the extension: temporary accommodation, storage, rescheduled moving arrangements, overlapping residence expenses, and professional costs where applicable. Separate estimates from signed commitments.
Compare those needs with accessible funds after allowing for unpaid deposits and the anticipated closing balance. Do not count the same dollars toward both the next installment and the extension reserve. Ask advisers to test a later-closing scenario as well as the seller's proposed date, using assumptions appropriate to the buyer's circumstances.
A Sunny Isles Beach buyer considering Bentley Residences Sunny Isles can use this exercise to distinguish purchase funding from lifestyle continuity. Neither a minimum reserve amount nor a universal reserve percentage is established here. Document the chosen amount, its underlying assumptions, and the events that would prompt a review.
Before accepting a revised closing timetable, request confirmation of the building's applicable milestone-inspection and Structural Integrity Reserve Study requirements and status. Ask counsel to distinguish requirements relevant to the property from those that do not yet apply to an unfinished development.
Where an inspection or reserve study is applicable, request its status, relevant deadlines, and available documentation. Have counsel confirm the building-specific requirements rather than relying on a general age threshold or an assumption based on coastal location.
Review available reserve documentation for potential association funding needs, but do not treat those needs as proof of an approved special assessment. Request separate documentation of any approved assessment, its payment schedule, and the purchase agreement's allocation of responsibility. Keep potential exposure distinct from an established payment obligation.
Before signing, assemble the proposed amendment, reconciled deposit schedule, notice protocol, conversion plan, personal liquidity schedule, and applicable building documentation. Ask counsel to confirm that the amendment and its attachments are consistent on dates, triggers, and amounts.
If seeking termination options, interest treatment, inspection access, or protections concerning defects, frame them as requests for legal review and negotiation. A delay alone should not be presented as creating those rights for every buyer. Confirm what the existing agreement provides and what the proposed amendment would change, including any releases or waivers counsel identifies.
The strongest extension package makes clear what the buyer must fund, what remains negotiable, and which uncertainties still require monitoring. That clarity supports a considered decision without confusing patience with an open-ended financial commitment.
For a discreet perspective on South Florida residential opportunities, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationDo not assume it does. Counsel should review the agreement and document expressly which payment obligations change under any extension.
Record each installment's amount, contractual trigger, original due date, payment status, and proposed revised treatment. Support the schedule with agreements, amendments, and payment acknowledgments.
No; request the applicable escrow arrangements and provisions governing permitted use. Ask counsel to confirm the protections and exceptions applicable to each installment.
Request the amount, contractual basis, triggering event, due date, recipient, and supporting evidence. Treat these fields as proposed documentation protections rather than universal legal requirements.
No universal notice period is established here. Review existing contractual requirements and negotiate any additional lead time in writing.
Identify the source currency, funding account, conversion institution, and expected processing requirements. The plan should make dollars available at each payment milestone.
There is no universal amount or percentage established here. Base the reserve on documented extension costs, remaining purchase obligations, accessible funds, and buyer-specific scenarios.
Do not treat potential funding needs identified in reserve documentation as proof of an approved assessment. Request separate documentation of approval, payment dates, and the purchase agreement's allocation of responsibility.
Request confirmation of the building's applicable requirements, inspection status, relevant deadlines, and available reports. Have counsel verify applicability rather than assuming a timetable based on coastal location.
A delay should not be assumed to create automatic termination rights. Counsel should evaluate the existing agreement, applicable law, and any negotiated amendment.