Buying a Miami home with a business partner calls for more than shared taste. These five questions address ownership, exit rights, funding, homestead expectations and property-specific risks before the purchase.
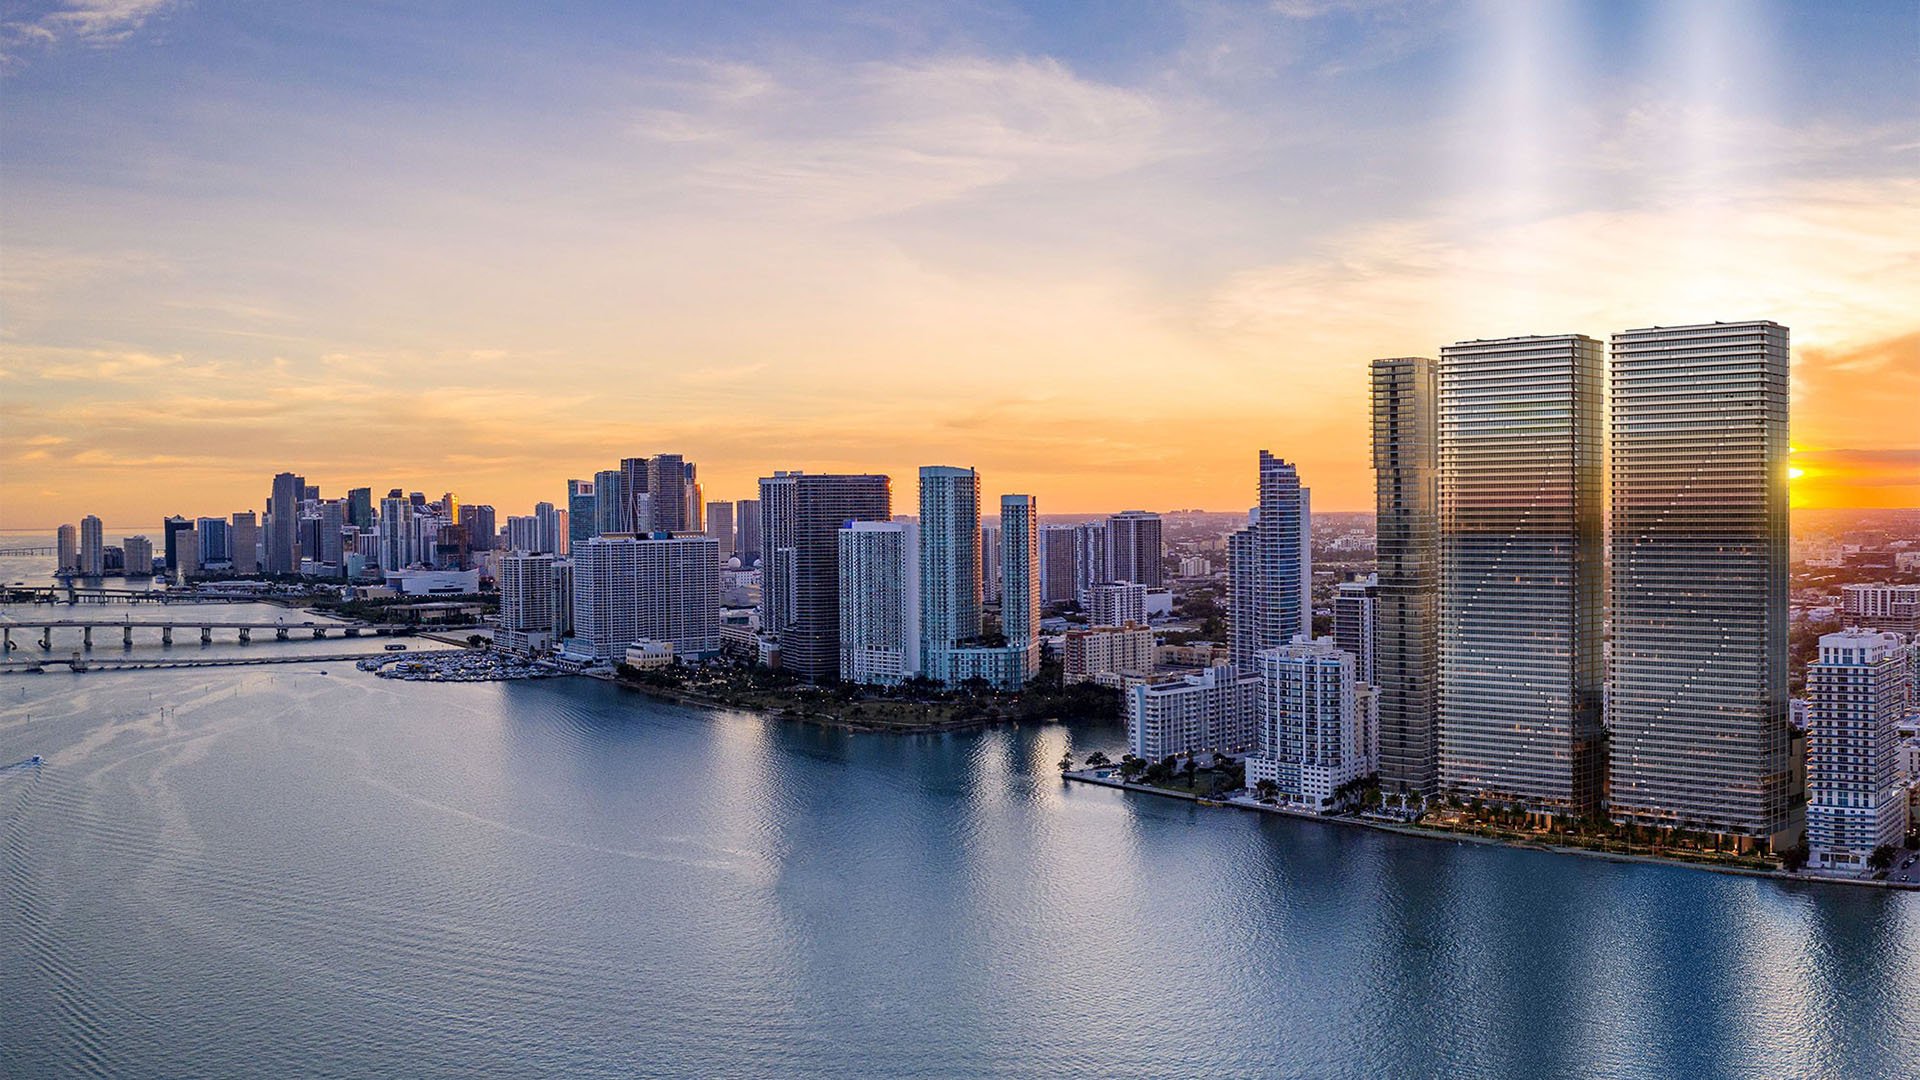
Buying a Miami home with a business partner brings two distinct decisions into one transaction: which residence to acquire, and how to own it together. Shared taste can resolve the first. It does not resolve the second. Before evaluating a floor plan or discussing an offer, partners should establish whether their expectations align on use, financial commitment and eventual exit.
Whether the search begins with 2200 Brickell or moves toward another address, the ownership conversation deserves its own agenda. A business relationship is no substitute for property-specific advice or written terms. The aim is not to anticipate every disagreement, but to decide how consequential decisions will be made before either partner has a reason to resist them.
These five questions give that discussion a practical sequence, moving from title and control to expenses, tax expectations and the property's condition.
1. What legal structure and ownership percentages will we use? - Title and control
Identify the proposed titleholders and each partner's ownership share before treating the purchase as agreed. Ask transaction counsel to evaluate the proposed structure against the partners' intended use and decision-making preferences. Discuss ownership percentages, financial contributions and spending authority explicitly; do not assume that one automatically determines the others.
Florida law permits joint tenants and tenants in common to bring partition actions against co-owners. That makes the form of ownership more than an administrative choice. Ask counsel how the proposed arrangement addresses that risk and which decisions should require both partners' agreement. Treat voting thresholds and contribution remedies as negotiated legal questions, not universal rules.
2. What happens if one partner wants out or the partners disagree? - Exit planning
Discuss the exit while both partners still want to buy. A negotiated process should address how a departing partner's interest would be valued, whether the other partner would have an opportunity to purchase it, and how the partners would proceed if they cannot agree. Ask counsel to translate those preferences into transaction-specific provisions rather than relying on an informal promise.
Partition can result in a court-supervised division or sale of the property. Litigation can also involve other parties with interests in the home, not just the two purchasing partners. An agreed buyout and dispute-resolution process therefore deserves attention alongside the acquisition itself. Neither partner should assume the home will remain available indefinitely simply because the original intention was long-term ownership.
3. How will we fund the purchase and ongoing expenses? - Shared financial capacity
Prepare a property-specific budget that separates acquisition funding, recurring ownership costs and potential extraordinary spending. Establish who will contribute, when funds must be available and who can approve an expense. If one partner cannot meet an agreed contribution, what response should the documents provide? Resolve those questions with counsel before a payment becomes contentious.
For property taxes, investigate the home's assessment information and recorded exemption status through county resources. Do not build the budget solely around a listing's stated costs or the seller's tax bill. Verify how the partners' intended ownership and use affect their tax expectations, then establish a process for reviewing the shared budget as circumstances change.
4. Will the property qualify for the tax benefits we expect? - Residence versus investment
Homestead eligibility depends on qualifying ownership and permanent-primary-residence conditions, not simply on purchasing a home. Do not assume a jointly acquired second residence or investment property will receive the same treatment as an eligible primary residence. Clarify each partner's intended use before factoring any anticipated benefit into the purchase decision.
Where one partner expects to live in the property and the other does not, seek advice specific to that arrangement rather than assuming a shared result. Check property-specific exemption information and have a qualified adviser assess eligibility under the proposed ownership. The seller's exemption history provides context, not confirmation of the buyers' future treatment.
5. What property-specific risks could create a major unexpected expense? - Condition and reserves
For a condominium purchase, make structural condition and reserve funding central to due diligence. Ask which condition assessments and reserve studies are available, what they address and what further review your advisers recommend. Both partners need to understand the building's financial and physical questions before deciding how much uncertainty they are willing to accept.
Have counsel confirm applicable requirements and the significance of the documents for the particular transaction. Separately, agree on how the partners would approve and fund an unexpected expense. Reviewing the building and reviewing the partnership are complementary exercises: one investigates the property; the other establishes how the owners intend to respond.
Location can shape the desired experience without answering the ownership questions. If the search includes Five Park Miami Beach, use the Miami Beach viewing conversation to clarify occupancy expectations: who intends to stay, how often and how conflicting preferences should be handled. These are planning questions, not assumptions about a particular building's policies.
Apply the same approach in Coconut Grove when considering Park Grove Coconut Grove. Separate enthusiasm for a residence from agreement about its use. Before comparing finishes, ask whether both partners envision the same holding period and financial commitment. A beautiful home cannot resolve incompatible expectations about access or liquidity.
For an Edgewater shortlist that includes Aria Reserve Miami, retain the same review framework. Compare the property-specific documents and unanswered questions rather than allowing a preferred address to compress due diligence. These examples are starting points for discussion, not conclusions about any project's ownership eligibility, reserves or condition.
Before proceeding, prepare a concise ownership brief covering titleholders, proposed shares, intended use, funding responsibilities, approval preferences and exit expectations. Identify which points are agreed and which require negotiation. Ask legal and tax advisers to test those preferences against the actual transaction rather than selecting documents first and fitting the partnership around them.
Keep the property review distinct from that brief. Assessment information, exemption questions and condominium documentation each deserve separate attention. The objective is a purchase both partners understand: how they enter, how they carry it and how they can leave.
For a considered approach to your Miami residential search, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationClarify titleholders, ownership shares, intended use, funding responsibilities and exit preferences. Have transaction-specific legal and tax advice guide the final arrangement.
Florida law permits joint tenants and tenants in common to bring partition actions against co-owners. A partition dispute can result in a court-supervised division or sale.
Discuss valuation, the remaining partner's opportunity to purchase the departing interest, and a process for unresolved disagreement. Ask counsel to assess and document appropriate provisions.
Yes. Other parties with interests in the property can be involved, so the potential dispute is not necessarily limited to the original buyers.
Do not assume the two are interchangeable. Ask counsel to document ownership shares and decision-making authority expressly for the proposed arrangement.
Review property-specific assessment information and recorded exemption status. Do not assume a listing's stated costs or the seller's tax circumstances will match the buyers' situation.
No. Homestead treatment depends on qualifying ownership and permanent-primary-residence conditions, not simply on purchasing a home together.
They should not assume a second home or investment property receives the same treatment as an eligible primary residence. Have an adviser evaluate the intended ownership and actual use.
Structural condition and reserve funding should be central review topics. Ask advisers to evaluate available documentation and confirm the requirements applicable to the transaction.
Discuss how additional spending would be approved and funded before buying. Have counsel address contribution responsibilities and potential disagreements in the transaction documents.