For a nonresident purchasing through a U.S. entity, securities-backed financing calls for a precise record of collateral, response deadlines, accessible liquidity, and eventual repayment. Keep that financing file distinct from the acquisition and future sale’s FIRPTA analysis.
For a nonresident buying South Florida real estate through a U.S. entity, the financing file deserves as much attention as the residence itself. A securities-backed line of credit, or SBLOC, is secured by an investment portfolio rather than the purchased property. Borrowing capacity therefore depends on the pledged assets and the lender’s requirements, not simply the property’s value.
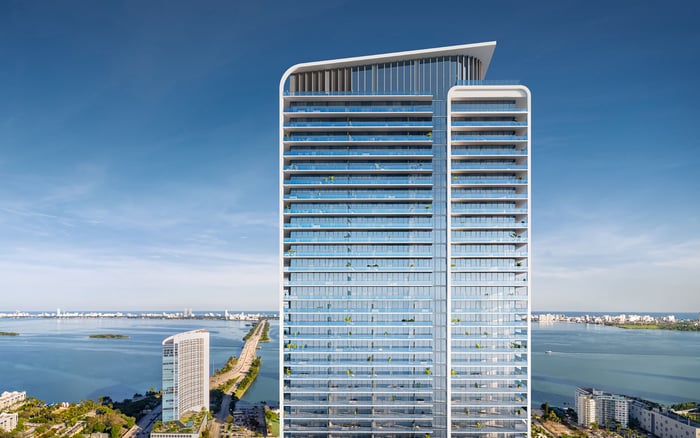
A buyer considering Una Residences Brickell should keep the property decision separate from the portfolio-credit decision. The question is not only whether funds can reach closing, but whether the borrower can manage the facility afterward. No project-specific financing arrangement is implied.
The objective is a coordinated record of collateral, maintenance calls, independent liquidity, interest costs, and eventual payoff. These are planning recommendations, not a universal statutory closing checklist or a substitute for transaction-specific legal and tax advice.
A portfolio statement establishes asset value, but not, by itself, borrowing capacity. A more useful record identifies the securities the lender accepts, their applicable advance rates, concentration exposure, and the maintenance requirements governing the facility.
Ask the lending team to make the following points explicit in the financing file:
Which securities are eligible collateral and which are excluded.
The advance rates applied to eligible holdings.
Concentrated positions that warrant particular attention.
The maintenance requirements and how compliance is measured.
The lender’s contractual ability to change requirements or securities eligibility.
Borrowers can generally continue trading pledged securities, subject to the lender’s collateral requirements. That flexibility is not unrestricted use of the portfolio. The record should allow the buyer and advisers to assess whether proposed changes in holdings affect available credit.
Document the interest-rate calculation and potential payment changes as well. Liquidity planning must account for financing costs alongside collateral calls. An acquisition budget that captures the initial draw but overlooks changing interest payments is incomplete.
A decline in the value of pledged securities can prompt a maintenance call requiring additional eligible collateral or repayment. Such calls typically must be satisfied within two or three days. The contractual deadline-not a general expectation-belongs prominently in the borrower’s file.
The consequence of delay is material: if the call is not satisfied, the lender may sell pledged securities without the borrower’s approval and apply the proceeds to the debt. The response plan should therefore identify people and instructions, not merely acknowledge the risk.
Document who receives the notice, who can authorize a response, which lender contact receives instructions, and whether the intended response is a collateral transfer or repayment. For a nonresident coordinating across time zones, establish a backup contact and confirm that the proposed authorization process can operate within the deadline.
Where an entity is involved, ask counsel and the lender to confirm the authority needed for those specific actions. This response plan is not a comprehensive entity-authorization or beneficial-ownership checklist.
The central distinction is between wealth and resources available to meet a call. Identify cash and eligible securities outside the pledged portfolio rather than relying exclusively on assets already supporting the loan.
For each proposed reserve, document its amount or value, where it is held, who can authorize its use, and whether it can reach the lender within the contractual window. Ask the lender to confirm whether securities intended as additional collateral would be acceptable. A reserve is useful only if it can serve its intended purpose.
For a Miami Beach purchase such as The Perigon Miami Beach, anticipated property equity should remain distinct from this response reserve. A future sale or refinance is not an assured solution to a call due within two or three days.
No universal buffer percentage suits every borrower. Set the reserve with the lending and advisory teams based on the actual portfolio, facility requirements, potential interest payments, and available response options. Record the assumptions so the plan can be revisited as circumstances change.
FIRPTA withholding requires an analysis separate from the financing decision. On the current acquisition, the relevant foreign-status question concerns the seller or transferor, not simply the nonresident buyer’s nationality. The purchaser generally acts as the withholding agent when acquiring a U.S. real property interest from a foreign person.
Document the seller-status analysis with the closing and tax advisers. A qualifying certification of nonforeign status, provided under penalties of perjury, can support an exception from withholding, subject to applicable requirements.
The U.S. entity also warrants careful attention when planning a later sale. For FIRPTA purposes, a disregarded entity is not treated as the transferor; its owner’s status matters. Do not assume that a U.S. entity’s involvement resolves the foreign-status question.
Whether the contemplated acquisition is Four Seasons Residences Coconut Grove or another Coconut Grove residence, keep property selection separate from the tax-classification analysis. Document the relevant transferor and obtain advice on the appropriate certification for the transaction.
A foreign person’s disposition of a U.S. real property interest generally triggers withholding of 15% of the amount realized, subject to exceptions and special rules. That general calculation is not based on the cash remaining after loan payoff.
For an eventual sale, prepare a proceeds schedule showing applicable withholding separately from the intended SBLOC repayment. Because the facility is secured by securities rather than the residence, explicitly coordinate any planned repayment from sale proceeds with the lender and closing team. Do not assume the property transaction itself resolves the portfolio debt.
Address taxpayer identification numbers early. Forms 8288 and 8288-A generally report and transmit applicable withholding. Form 8288-B is used to apply for a withholding certificate under specified categories. Coordinate any proposed reduction with the closing’s withholding analysis rather than treating it as assured cash availability.
Ask the advisers to reconcile anticipated proceeds, withholding treatment, the intended repayment amount, and repayment instructions before those proceeds become central to the liquidity plan.
The strongest documentation is a working decision record: current collateral terms, a clear call-response plan, identifiable outside reserves, and a separate tax-and-payoff analysis. Review it when holdings, lender requirements, or the intended exit change. The aim is to preserve choice when a short deadline could otherwise force a decision.
For a considered approach to South Florida’s exceptional residences, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationAn investment portfolio secures the facility rather than the purchased property. Borrowing capacity depends on the pledged securities and the lender’s collateral requirements.
Record eligible securities, advance rates, concentration exposure, and maintenance requirements. Also capture the lender’s ability to change collateral requirements or securities eligibility.
Borrowers generally can continue trading, subject to the lender’s collateral requirements. Proposed portfolio changes should be evaluated for their effect on available credit.
Maintenance calls typically must be satisfied within two or three days. Confirm the actual contractual deadline and document who can authorize the response.
The lender may sell pledged securities without the borrower’s approval and apply the proceeds to the debt. A documented response plan helps address that risk before a call occurs.
Identify accessible cash and eligible securities outside the pledged portfolio. Confirm that the proposed resources can be transferred or applied within the contractual response window.
An anticipated sale or refinance should not be treated as an assured solution. A response window of two or three days may not accommodate either transaction.
No. FIRPTA analysis on the acquisition concerns the relevant seller or transferor’s tax status, and the purchaser generally serves as withholding agent when buying from a foreign person.
Do not assume it does. A disregarded entity is not treated as the transferor for FIRPTA purposes, so its owner’s status matters.
Show applicable withholding separately from the intended debt repayment. The general 15% withholding calculation is based on the amount realized, subject to exceptions and special rules, rather than cash remaining after payoff.