A Miami primary residence and a federal tax home are not necessarily the same place. These five questions clarify homestead documentation, business-travel records, mixed-purpose trips, and commuting after a purchase.
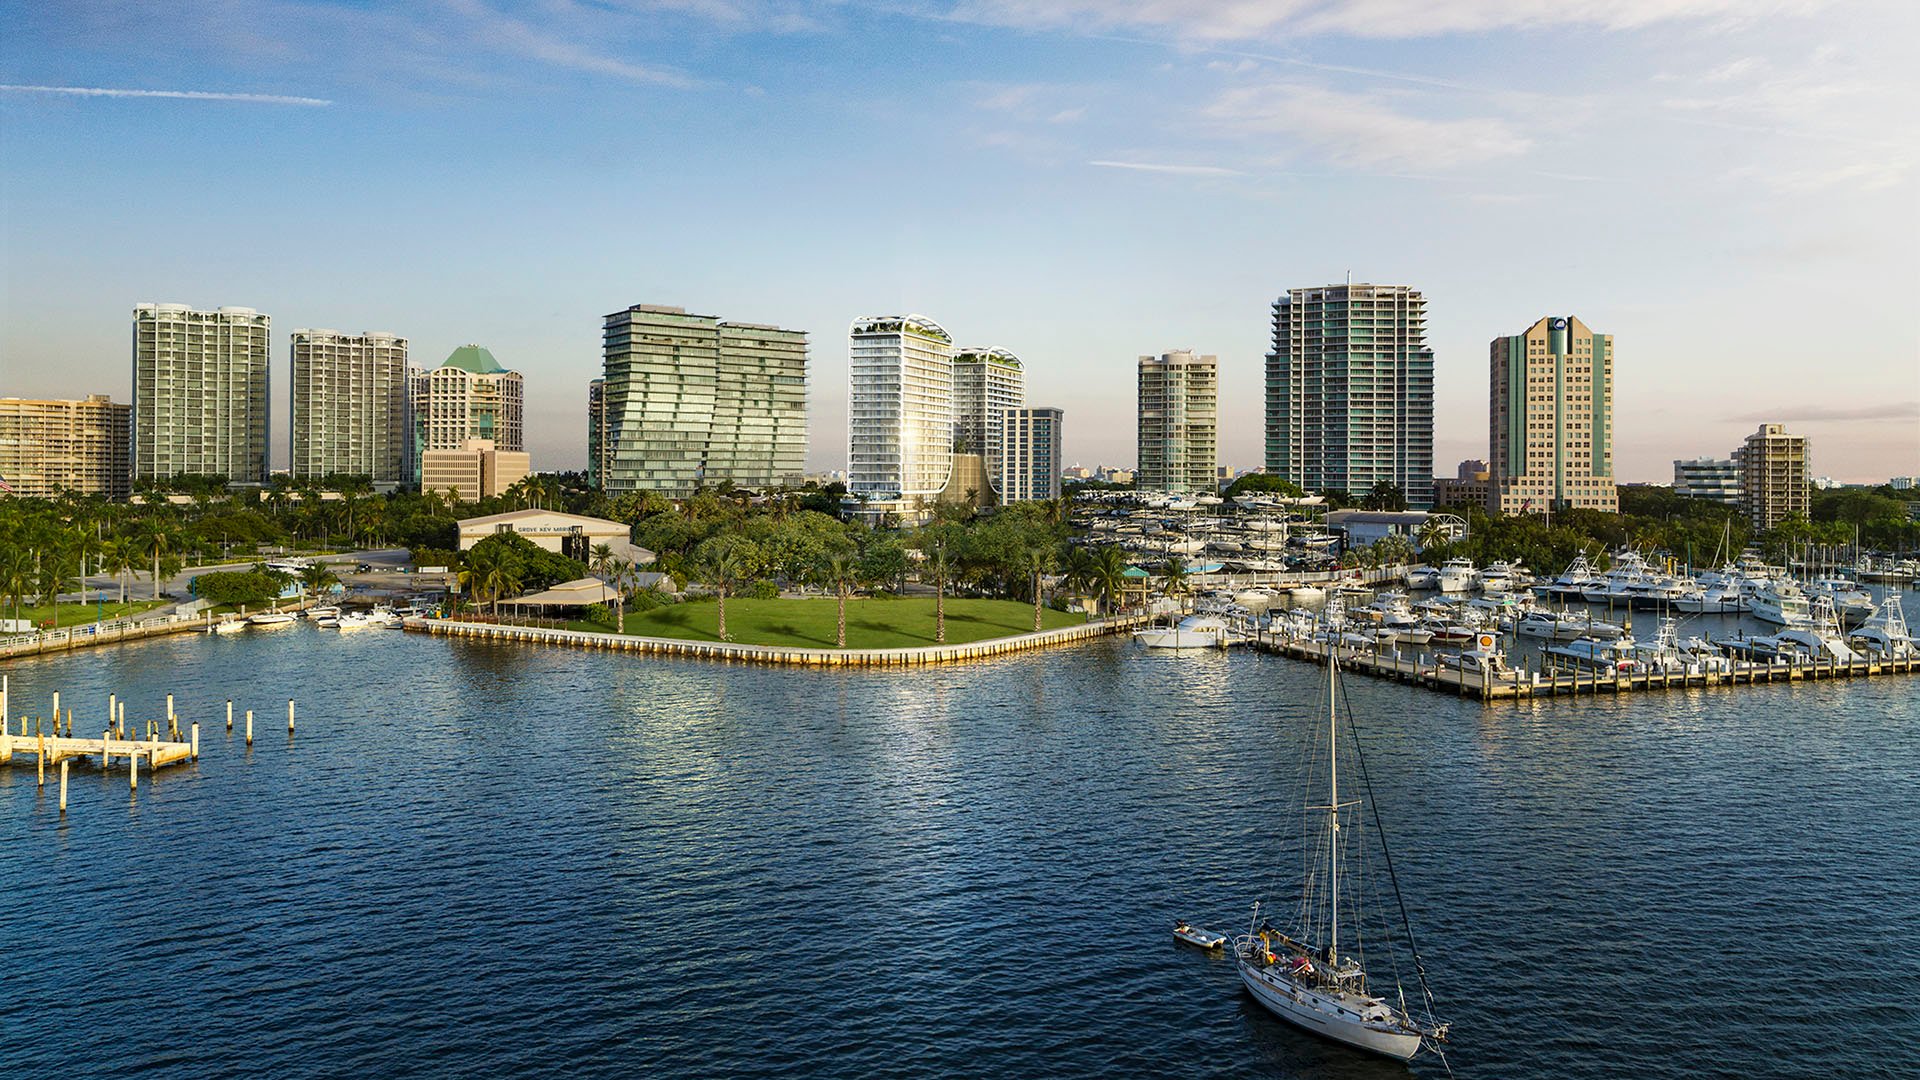
Buying a primary residence in Miami can bring a welcome sense of permanence to a life organized around business travel. Yet the purchase leaves two separate questions unresolved: what establishes the property as a permanent residence, and where is the owner's tax home for work-travel purposes? The answers need not point to the same place.
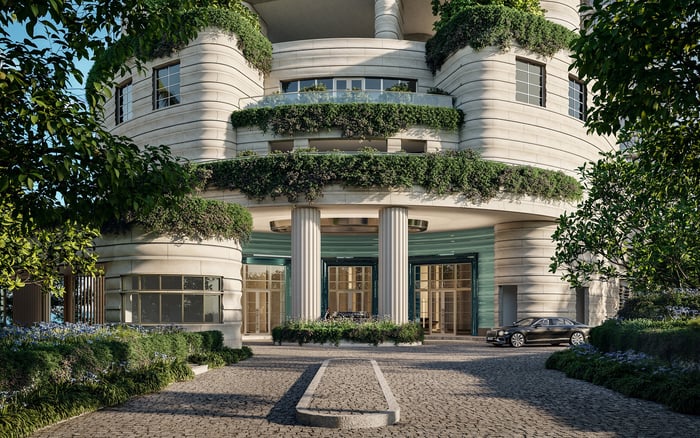
For a buyer considering 2200 Brickell, the relevant distinction is not Brickell's appeal as a home base. It is the difference between documenting residence and documenting business activity. A purchase alone settles neither inquiry.
Start with two files: one for permanent-residence eligibility and another for business travel. Keeping them separate helps prevent a residential decision from becoming an unsupported tax assumption.
1. What establishes the Miami property as a permanent residence? - Homestead eligibility
Miami-Dade homestead eligibility generally requires legal or equitable title and permanent residence at the property as of January 1. The regular application deadline is March 1. Ownership alone is not the complete test; residence at the relevant time matters too.
Supporting evidence can include a Florida driver's license or identification card, vehicle registration, voter registration, a prior-year federal income-tax return or current W-2, bank statements, utility-payment records, and a recorded Declaration of Domicile. If the property is held through a trust, a copy of the trust document is required for the application. Assemble evidence that reflects the actual ownership and residence circumstances rather than assuming the closing file is sufficient.
2. Does buying a Miami primary residence automatically make Miami the tax home? - Business location
No. For business-travel purposes, the tax home generally follows the regular place of business or duty, regardless of where the family home is maintained. When there are multiple regular business locations, the main place of business generally determines the tax home. A Miami residential address does not override that analysis.
For someone without a regular or main workplace, relevant considerations include business activity near the main home, duplicated living expenses, and residential or lodging ties. An itinerant worker without a regular workplace or regular residence generally cannot claim to be traveling away from a tax home. Address these distinctions before classifying travel expenses, not only when preparing a return.
3. What work-travel records should be kept? - Timely substantiation
Maintain a trip log that establishes dates, destinations, business purposes, and expense amounts. A diary, notebook, log, or comparable written record can support the file when paired with appropriate documentation. Make entries at or near the time of the expense rather than reconstructing a busy travel calendar long afterward.
Keep receipts, invoices, itineraries, payment evidence, and relevant mileage records with the log. Include employer-reimbursement documentation so reimbursed costs remain distinguishable from other expenses. A reservation or payment record may establish part of the trip, but the complete file should also explain its business purpose. Documentation supports evaluation; it does not independently establish deductibility.
4. How should mixed business-and-personal trips be documented? - Clear separation
For domestic or international travel that combines work with personal time, identify business activities, personal extensions, and the expenses associated with each. Do not classify the entire itinerary as business travel merely because it includes a meeting. The record should distinguish the professional portions from the personal ones.
Annotate the itinerary while the trip is underway and match supporting documents to the relevant activities. Ordinary and necessary business-travel expenses may qualify for deductions, but documentation cannot convert a personal expense into a business expense. The taxpayer's work pattern, trip purpose, reimbursement arrangements, and applicable tax-year rules still matter.
5. Can travel between the Miami residence and another workplace be deducted? - The commuting boundary
Travel between a personal residence and a regular workplace is generally nondeductible commuting. Purchasing a Miami home does not automatically change that classification. What matters is the relationship between the residence, the regular workplace, and the tax home-not the owner's preferred description of the journey.
Keep the itinerary and business context, but do not treat departure from Miami as proof of deductible travel. Review the actual work arrangement before classifying a recurring journey as business travel. This distinction is particularly important when the home and regular workplace are in different locations: the purchase itself does not establish that the resulting journeys qualify.
For buyers considering Park Grove Coconut Grove, the administrative principle is the same: a Coconut Grove address and a work-travel calendar answer different questions. The residence file should establish the ownership and permanent-residence facts relevant to the homestead application.
Organize title-related material separately from supporting residence evidence. If a trust holds the property, include the trust document in the application materials rather than leaving it elsewhere in the ownership records. Keep January 1 eligibility and the regular March 1 filing deadline visible in the planning calendar.
Distinguish evidence from conclusions. A bank statement or utility-payment record can support residence, but it does not determine the owner's federal tax home. Likewise, a detailed itinerary is no substitute for establishing permanent residence.
A practical travel file should let the owner or adviser understand what happened without relying on memory. Begin with the dates, destination, and business purpose, then connect each expense to its supporting document. Keep reimbursement records with the same trip so the financial picture remains clear.
For a buyer evaluating Aston Martin Residences Downtown Miami as a primary-home option, recordkeeping remains independent of the residential choice. Downtown Miami may be the intended home address; the regular or main business location still requires a separate assessment.
Use a consistent structure for every trip, including journeys with personal extensions. Consistency makes the file easier to review, while timely entries reduce reliance on recollection. Neither practice guarantees a deduction, but both support a clearer assessment of the expenses.
The central distinction is straightforward: permanent residence concerns the home, while business-travel treatment depends on the work arrangement and the trip. Keep both files complete, but do not ask one to prove the other. Before claiming expenses, have a qualified tax adviser evaluate the relevant work pattern, reimbursement arrangements, and applicable tax-year rules.
For a discreet perspective on choosing your South Florida home, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Eligibility generally requires legal or equitable title and permanent residence at the property as of January 1, supported by appropriate documentation.
The regular application deadline is March 1. January 1 is the relevant date for ownership and permanent-residence eligibility.
Supporting evidence can include Florida identification, vehicle and voter registration, tax documents, bank statements, utility-payment records, and a recorded Declaration of Domicile.
A copy of the trust document is required for the homestead application.
No. The tax home generally follows the regular or main place of business, regardless of where the family home is maintained.
Relevant considerations include business activity near the main home, duplicated living expenses, and residential or lodging ties.
Record dates, destinations, business purposes, and expense amounts at or near the time of the expense. Keep supporting documents with the log.
Yes. Employer-reimbursement records help distinguish reimbursed costs from other travel expenses.
Identify the business activities, personal extensions, and associated expenses separately. A business meeting does not make the entire trip deductible.
No. Travel between a personal residence and a regular workplace is generally nondeductible commuting, and the purchase alone does not change that classification.