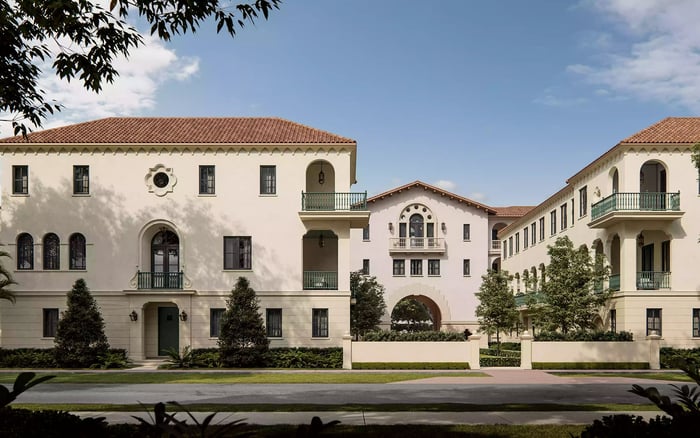
For buyers at The Village at Coral Gables, financial discretion starts with separating liquidity verification from funding-origin documentation, then agreeing on what each recipient actually needs.
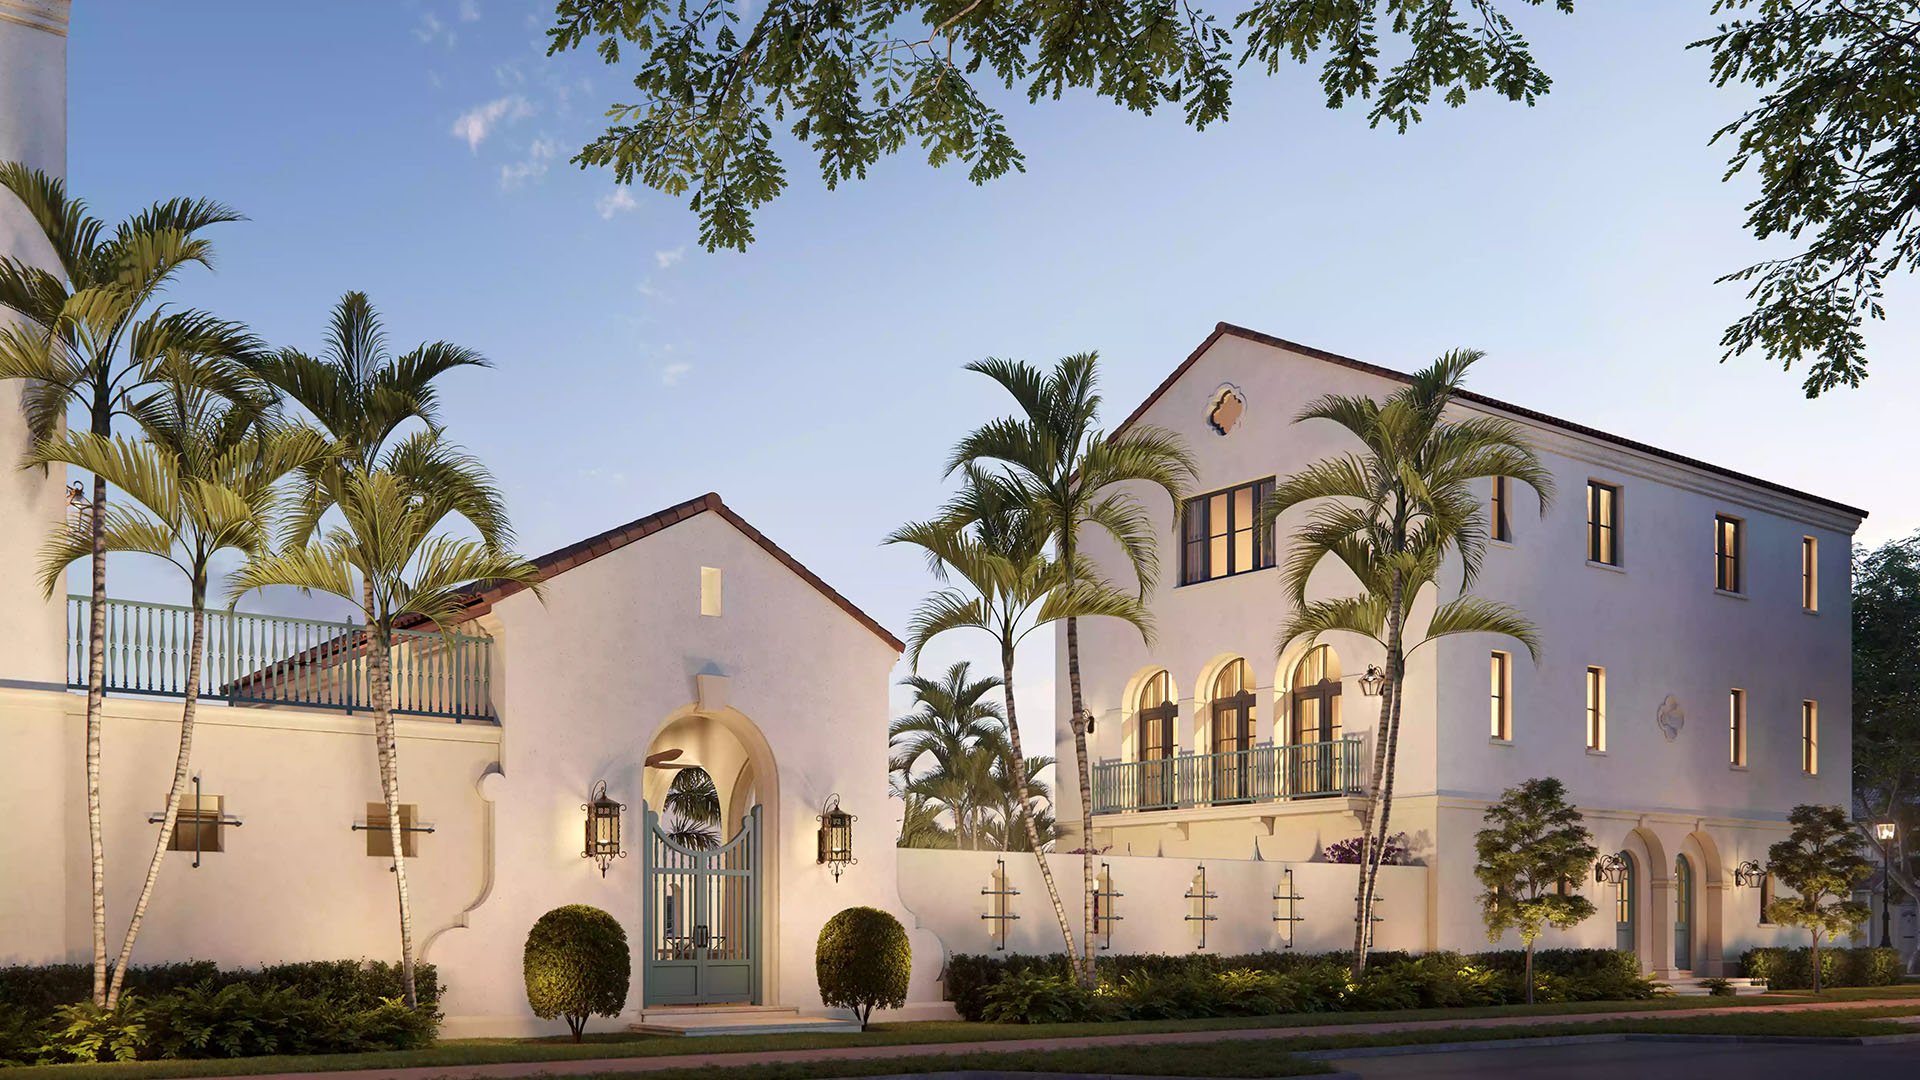
A luxury purchase should establish a buyer’s ability to proceed without unnecessarily exposing an entire financial life. At The Village at Coral Gables, MG Developer’s collection of 48 residences includes townhomes, flats and villas. For buyers considering this setting, financial discretion deserves the same attention as the residence itself.
The central distinction is straightforward: proof of funds demonstrates available liquidity; source of funds explains where the transaction money originated. Treating these as separate requests helps buyers prepare relevant evidence rather than circulate a comprehensive financial dossier at the outset.
Do not assume that The Village accepts any particular bank letter, redaction or alternative confirmation. Agree on the purpose, scope and recipient of each request before sending documents. Privacy here means limiting unnecessary disclosure, not withholding information required for verification.
Start by asking what the requesting party needs to establish. Is the request intended to qualify an offer, demonstrate capacity for a deposit, support financing or document funds for closing? These purposes should not automatically be treated as interchangeable.
Proof-of-funds documentation should identify the account owner, financial institution and available liquid balance sufficient for the relevant purchase obligation. Recent bank statements and letters on official bank letterhead are potential formats, subject to the recipient’s requirements. Aim for documents dated within 30 days when possible, but do not treat that guidance as a confirmed Village-specific rule.
Ask the recipient to specify the amount, acceptable document format and required date range. This gives the banker a defined assignment and reduces the risk of submitting a broad statement package that still fails to answer the actual question.
Where accepted, a tailored banker’s letter can demonstrate sufficient liquidity without revealing full transaction histories or unrelated assets. Ask whether confirmation that available liquid funds meet or exceed an agreed amount will suffice, rather than disclosing every account balance.
A useful request might read: “Please confirm whether a dated letter on bank letterhead identifying the account owner and institution, and confirming sufficient available liquid funds for the stated obligation, will satisfy this stage of review.”
Acceptance is specific to the recipient. A sales team’s approval does not establish that a lender or another institution will accept the same document. Nor should a letter imply that assets are liquid when they still require a sale or another funding event.
For buyers also considering Ponce Park Coral Gables, the same question is worth asking separately. A preferred document format can guide preparation, but acceptance should never be assumed across different purchases.
Source-of-funds evidence answers a different question: how did the buyer obtain the money being used? Potential origins include a property or business sale, investment liquidation, earned income or inheritance. A sufficient balance alone does not explain that history.
Prepare a concise explanation identifying the funding event, relevant amounts and dates, then connect it to supporting records. The aim is a clear account of the money used for the acquisition, not an unsolicited inventory of unrelated wealth.
If a recent property sale supplies the purchase money, a certified closing statement can help support the file alongside relevant bank records. Investment proceeds may call for investment and bank records; earned income may be supported by income or tax documents; inherited funds may require relevant inheritance documentation.
These are general documentation concepts, not a statement of Florida legal requirements or The Village’s checklist. Before treating the file as complete, ask the reviewing institution which records it needs and whether the proposed explanation provides enough detail.
Redaction should be an agreed safeguard, not a unilateral editing exercise. Obtain the recipient’s approval before masking account identifiers, unrelated transactions or other details. Information that appears incidental to the buyer may be necessary to establish the funding trail.
A practical privacy discussion should cover four points:
Which fields must remain visible for this particular review?
Who needs the underlying records, rather than confirmation of their review?
Can sensitive documents be delivered directly to the lender or title company?
What access controls, delivery method and retention practices will apply?
Direct delivery or a bank or title confirmation may be worth proposing, but neither should be presented as an accepted substitute without agreement. Likewise, confidentiality markings and restricted-circulation requests do not override required verification or recordkeeping.
If the search includes Cora Merrick Park, confirm the intended recipients again rather than automatically forwarding the same financial package. Keep a record of what was shared, with whom and for which purpose.
Foreign-national financing may require more documentation than initial purchase qualification. Potential requirements include two to three months of foreign bank statements, a bank reference letter and evidence of reserves. A passport, a visa where applicable and an ITIN may also be requested, depending on the lender’s and closing parties’ requirements.
Establish the financing checklist early and send identity documents only where a confirmed need exists. Do not assume passport copies belong in an initial showroom submission.
Keep a concise qualification package distinct from the more detailed records requested for underwriting or funding-origin review. This is an organizational approach, not permission to omit required information. Each recipient must confirm what satisfies its own review.
Financial evidence should match the actual obligation under consideration. Do not calculate a qualification amount from an advertised starting price or assume an older construction-deposit schedule describes today’s contract terms. Confirm the current residence-specific price, deposit obligations and timing before commissioning a letter tied to those figures.
Review the applicable purchase documents with counsel rather than treating marketing material as the controlling description of commitments.
The strongest privacy strategy is orderly cooperation: clarify the request, propose the least expansive evidence sufficient for the review, secure approval for any redactions and preserve the complete funding trail where required. This approach supports a credible transaction while keeping unrelated financial information out of unnecessary circulation. No privacy safeguard, however, guarantees acceptance or confidentiality.
For a discreet conversation about your Coral Gables property search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationProof of funds demonstrates sufficient available liquidity for a purchase obligation. Source of funds explains how the money used for the transaction was obtained.
Acceptance should be confirmed directly with the requesting party. A tailored bank letter is a potential option, not an established Village-specific policy.
It should identify the account owner, financial institution and available liquid funds sufficient for the relevant obligation. Confirm the recipient’s required format and amount before preparing it.
Documents dated within 30 days are a practical target when possible. That is not a confirmed requirement at The Village, so ask the recipient for its date requirements.
Ask whether the recipient will accept confirmation that liquid funds meet or exceed a stated amount. Acceptance of a threshold-based letter is not guaranteed.
Obtain the recipient’s approval before masking information. Details needed to establish the funding trail may have to remain visible.
A certified closing statement can help support the file, together with relevant bank records connecting the sale proceeds to the purchase money.
You can propose direct delivery and ask whether other parties can rely on an accepted confirmation. Do not assume this arrangement satisfies every recipient’s requirements.
Potential requirements include two to three months of foreign bank statements, a bank reference letter and reserve evidence. Identity requirements may include a passport, an applicable visa and an ITIN, depending on the parties involved.
No. Confidentiality markings, access restrictions and retention requests are proposed safeguards, not overrides of required verification or recordkeeping.