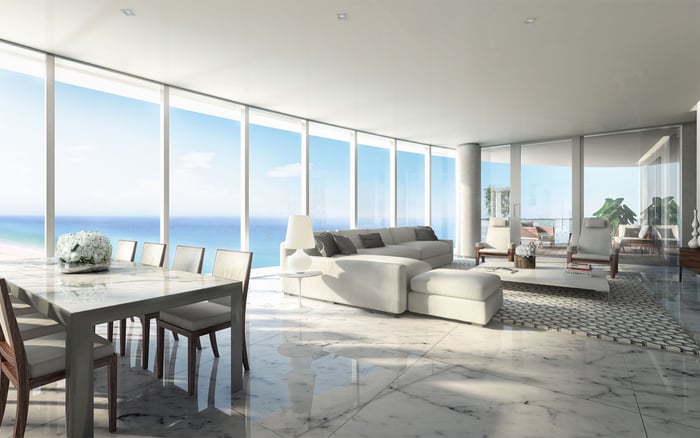
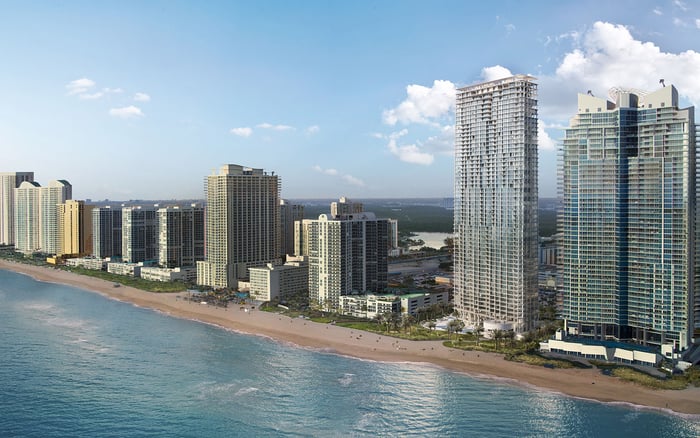
A primary-residence purchase at Armani Casa Sunny Isles Beach calls for more than a compelling floor plan. Evaluate homestead eligibility with counsel, build a buyer-specific carrying-cost model, and examine association obligations before committing.
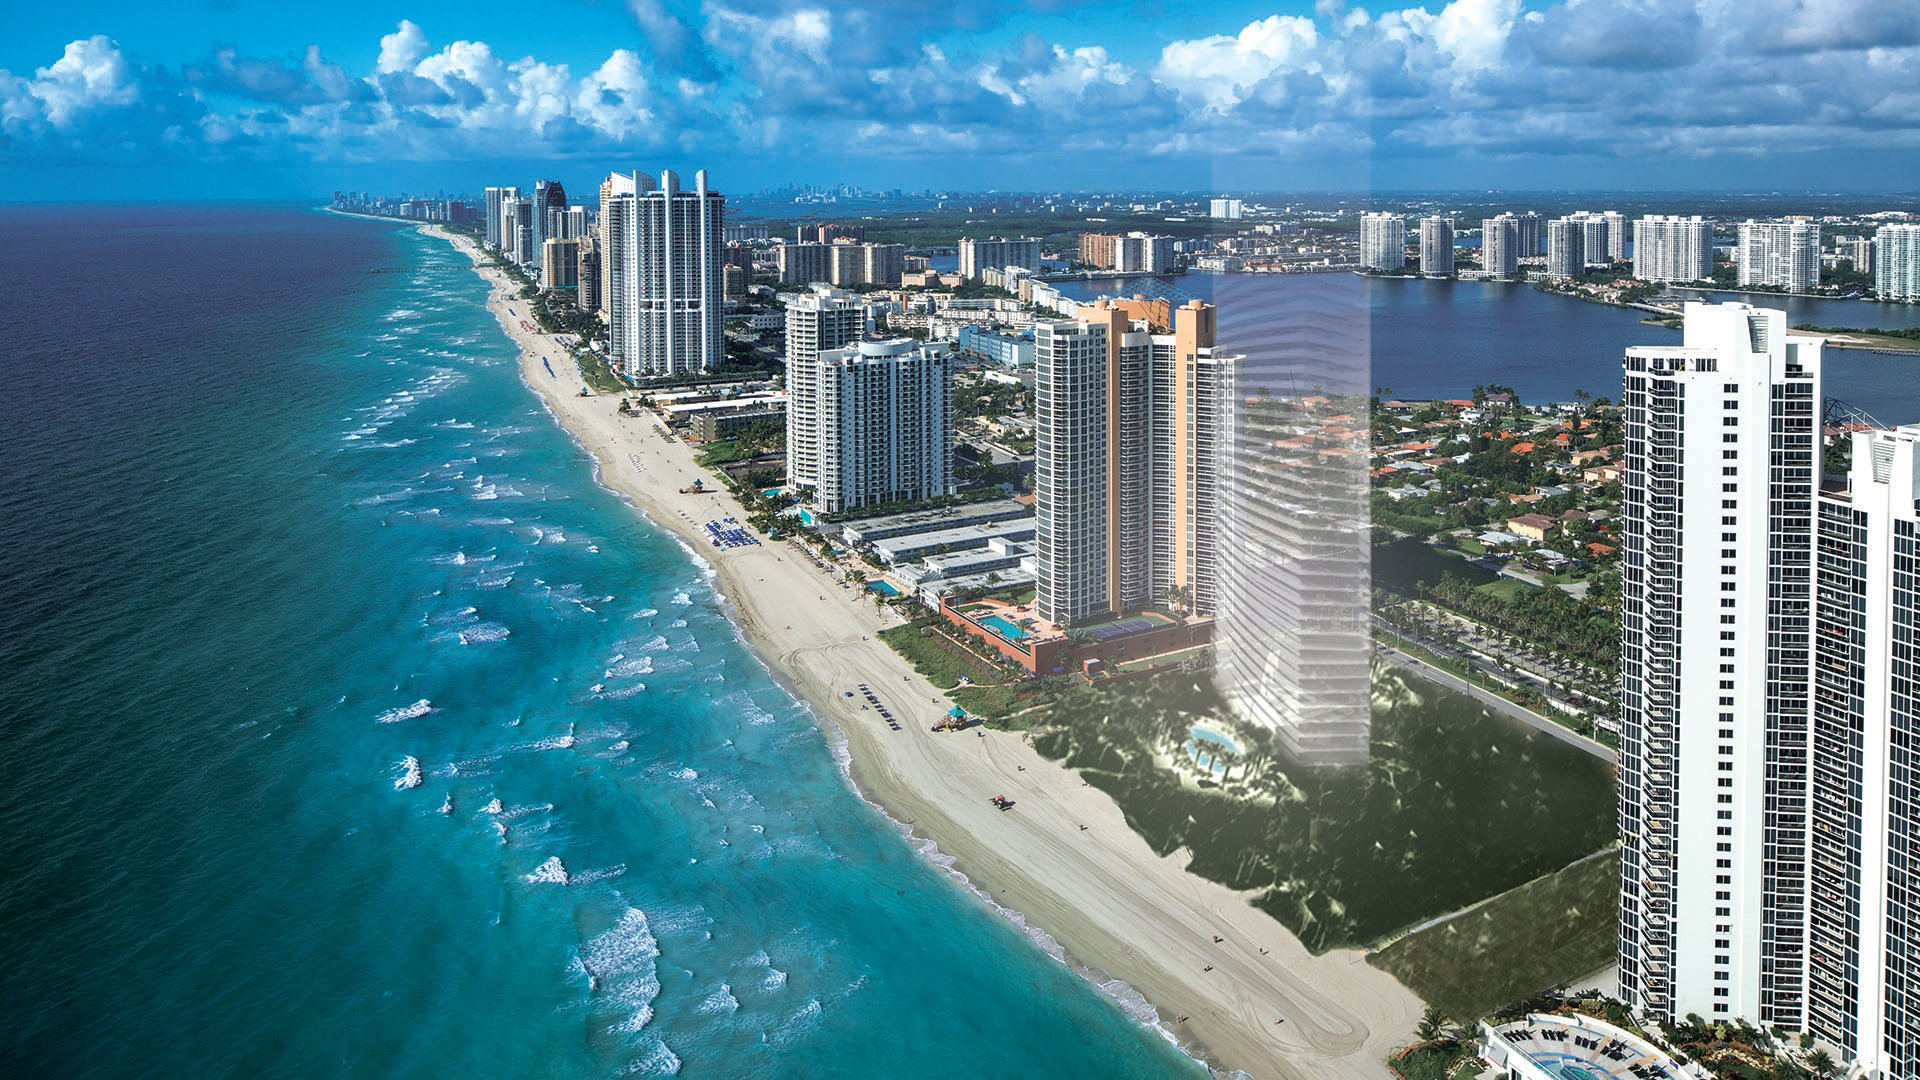
At Armani Casa Sunny Isles Beach, the primary-residence decision begins with an oceanfront address at 18975 Collins Avenue. The 56-story tower contains 308 condominium residences, with advertised sizes ranging from 1,326 to 4,150 square feet. Those dimensions establish the breadth of the residential offering. They do not settle the more consequential question: whether a particular home fits the buyer’s life and ownership plan.
For a serious buyer, homestead eligibility belongs at the start of due diligence-not in a conversation after closing. Treat potential benefits as a buyer-specific matter to establish with Florida counsel and a tax advisor, rather than an attribute of the building or asking price.
The discipline is simple: choose a residence that works without unconfirmed benefits, then refine the financial decision once professional advice supports the assumptions. An attractive address should complement a sound ownership strategy, not substitute for one.
Before relying on homestead treatment, prepare a written brief describing intended occupancy, the proposed ownership structure and any rental plans. Give the same brief to counsel and the tax advisor so their recommendations address the same household circumstances.
Ask them to identify the applicable eligibility requirements, documentation, filing timetable and consequences of the proposed title arrangement. If a trust or another ownership vehicle is under consideration, have that structure evaluated before finalizing it. A general discussion of Florida residency is not an individualized homestead determination.
The review should produce a coordinated answer to three questions:
Does the intended use support the homestead treatment being considered?
Does the proposed ownership structure support that treatment?
What assumptions should the buyer include in the purchase budget, and when?
If eligibility remains unresolved, exclude any anticipated benefit from the base-case budget. If advisors confirm the relevant treatment, ask them to quantify its effect for this purchase. Homestead should sharpen the ownership decision, not sustain an otherwise uncomfortable acquisition.
Unit #801 provides a concrete starting point. In an advertised snapshot updated August 31, 2026, its asking price was $4.7 million, with a quoted monthly association fee of $5,203. Annualized, that fee equals $62,436. The unit’s stated property taxes for 2025 were $48,552.
The annualized fee and stated taxes total $110,988 before financing and other owner expenses. The distinction matters: this combines a 2026 listing fee with 2025 taxes. It is neither an all-in carrying-cost estimate nor a forecast of a new buyer’s tax obligation. The unit’s homestead status is not established, so the historical tax figure should not be labeled a homestead or non-homestead benchmark.
Build a separate purchase model using a current association-fee confirmation and an advisor-prepared tax estimate. Add financing, owner insurance, utilities, interior maintenance and any applicable assessments as individually verified line items. Compare a base case that assumes no unconfirmed homestead benefit with a scenario incorporating only advisor-supported treatment.
Unit #302 offers another point of reference: its advertised monthly maintenance fee was $5,257. These examples warrant close attention to recurring expenses, but neither establishes a building-wide average or the fee for another residence.
The residence is only one part of the acquisition. Request the declaration, current budget, reserve information, insurance details, assessment notices and leasing rules. Have the relevant professionals explain how those documents affect the specific unit under consideration.
Separate ordinary recurring charges from other potential obligations. Ask what the monthly fee includes, which services carry additional charges and whether any assessment notices affect the purchase. Confirm the unit’s current financial obligations rather than importing another apartment’s figures into the analysis.
For a household also considering Jade Signature Sunny Isles Beach, use the same document checklist for each candidate. Base the comparison on verified obligations and the buyer’s intended use-not an assumption that similar addresses or positioning imply equivalent costs.
Keep homestead analysis and association analysis separate. A favorable tax conclusion does not replace an understanding of the condominium’s finances, insurance arrangements or ownership rules.
A permanent home needs to perform beyond the initial viewing. Unit #302 illustrates one configuration: four bedrooms, four full bathrooms, one half-bathroom, 2,682 square feet and two advertised parking spaces. That combination provides a practical starting point for assessing household accommodation, guest privacy and vehicle needs. It does not establish what another unit includes.
During a viewing, test furniture placement, work-from-home requirements, storage and circulation between private and shared rooms. Confirm parking rights and any associated conditions for the actual residence being purchased.
Advertised amenities include a heated pool, spa or hot tub, sauna, garage parking and valet service. For a primary-residence buyer, the question is not simply whether an amenity exists, but whether its operation supports everyday life. Ask about access, hours, guest arrangements and charges before assigning it value in the purchase decision.
If Turnberry Ocean Club Sunny Isles is also on the shortlist, apply the same daily-use questions there. A disciplined comparison should reveal which residence suits the household, not merely produce a longer amenity inventory.
Clarify whether rental use is a contingency or part of the original ownership plan. Ask counsel and the tax advisor to assess that intention alongside homestead eligibility, then examine the association’s actual leasing provisions.
Advertised asking rents provide context, not an investment conclusion. A rental snapshot offered two- to four-bedroom condominiums at $10,700 to $25,000 monthly. Separately, unit #504 was advertised in May 2026 at $15,500 monthly for two bedrooms and 1,516 square feet. Neither observation establishes achieved rent, occupancy or net yield.
Unit #1404 advertised a one-year lease with a renewal option. That term describes one offering, not a building-wide policy. Do not budget rental income until the intended arrangement has been evaluated and its economics independently modeled.
Before proceeding, bring the principal reviews together: occupancy and title advice, buyer-specific taxes, confirmed association obligations and the residence’s practical suitability. Identify which conclusions are documented and which remain unresolved.
The strongest primary-residence purchase remains comfortable without speculative savings or rental income. Confirmed homestead treatment can then inform the final decision rather than rescue it. At Armani Casa, that distinction pairs the appeal of oceanfront ownership with a clear understanding of its commitments.
For a discreet conversation about your South Florida primary-residence search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationResidences by Armani / Casa is at 18975 Collins Avenue, Sunny Isles Beach, FL 33160.
The oceanfront tower has 56 stories and 308 condominium residences. Advertised residence sizes range from 1,326 to 4,150 square feet.
No. Have Florida counsel and a tax advisor evaluate intended occupancy, ownership structure and rental plans before relying on any potential benefit.
Ask them to assess eligibility requirements, documentation, filing timing and the proposed title arrangement. Request a buyer-specific tax estimate for the purchase model.
Unit 801 was advertised at $4.7 million in a snapshot updated August 31, 2026. That is a dated asking price, not a confirmed current price or completed sale.
Its quoted $5,203 monthly association fee annualizes to $62,436; adding stated 2025 taxes of $48,552 produces $110,988. This mixed-period benchmark excludes financing and other expenses and is not a buyer-specific forecast.
No. Its homestead status is not established, and its historical taxes should not be used as a forecast of a new buyer’s obligation.
Request the declaration, current budget, reserve information, insurance details, assessment notices and leasing rules. Confirm the obligations and charges applicable to the specific unit.
Unit 302 advertised four bedrooms, four full bathrooms, one half-bathroom, 2,682 square feet and two parking spaces. Its advertised monthly maintenance fee was $5,257.
No. Asking rents do not establish achieved income or yield, and unit 1404’s advertised one-year lease with a renewal option does not establish association-wide policy.