A family-office framework for evaluating ONE Park Tower: separate ownership layers, document purchase authority, prepare a coherent funding file, and establish independent wire controls.
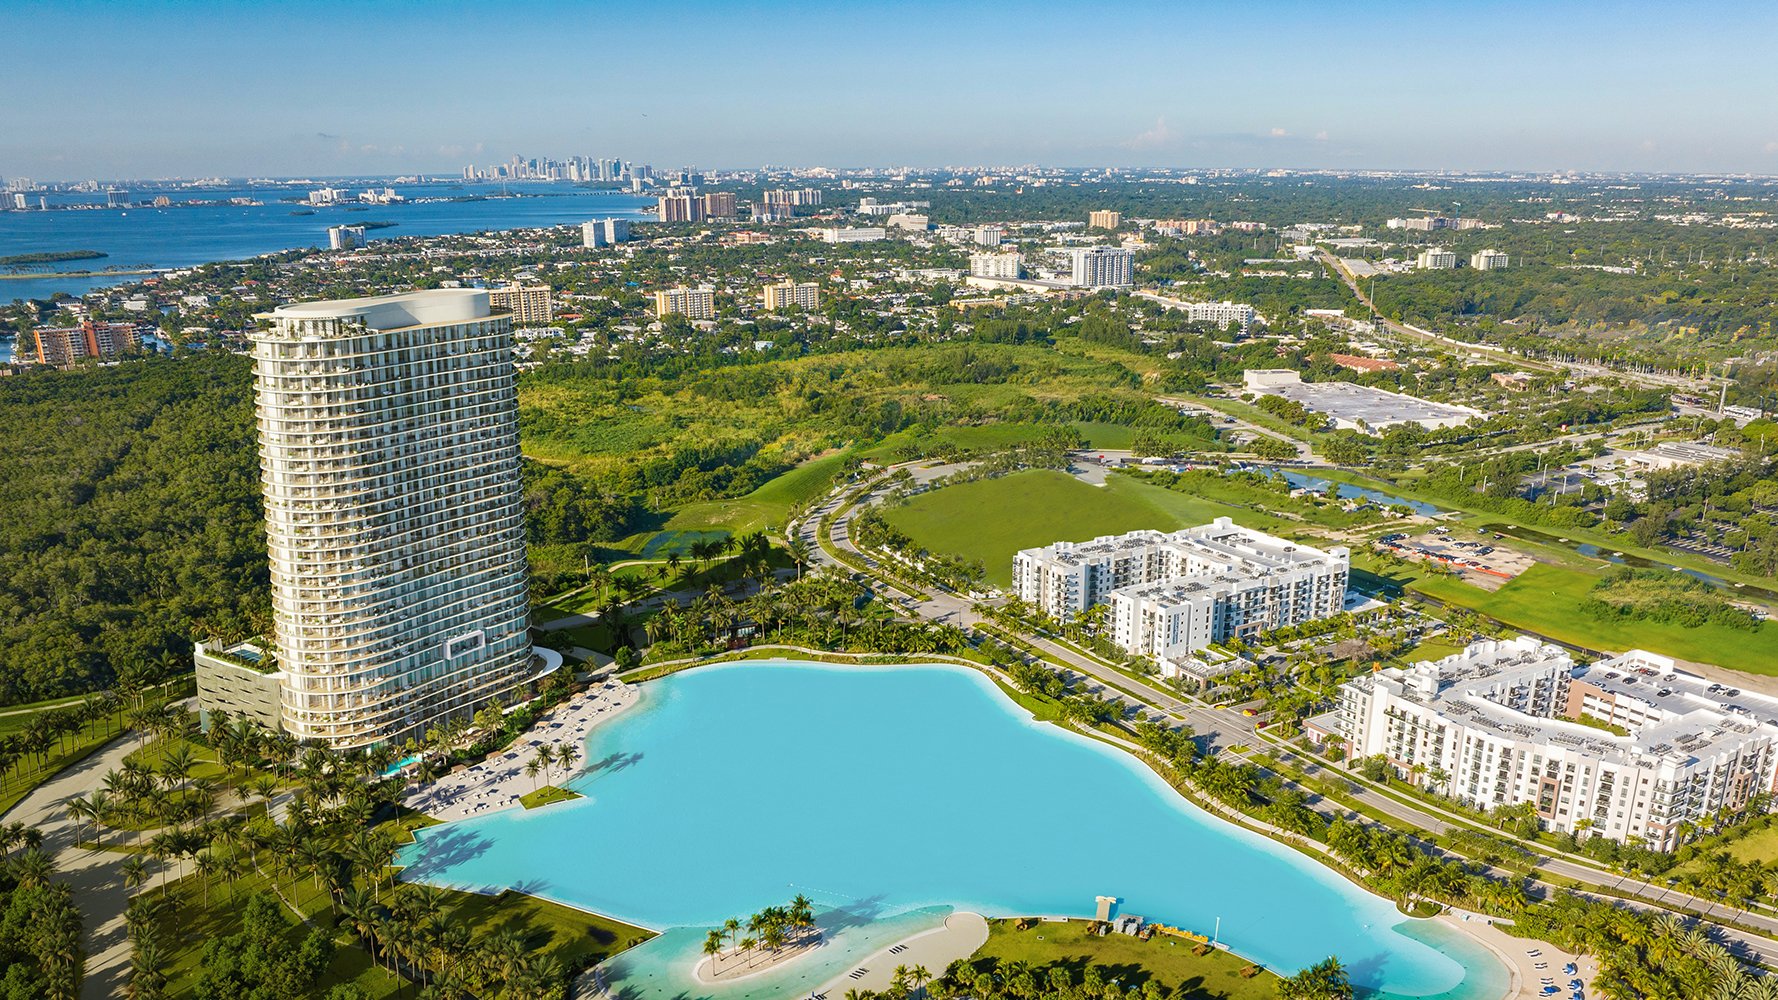
At One Park Tower by Turnberry North Miami, a 33-story condominium with 292 residences sits within SoLé Mia, North Miami’s 184-acre master-planned community. The address is 2411 Laguna Circle, North Miami, Florida 33181. Residences overlook a seven-acre Crystal Lagoon, and amenities include access to a private beach.
For a family office, that setting begins the evaluation; it does not conclude it. The ownership file should establish who is selling, who is buying, who can bind each party, and how capital reaches its intended destination. Lifestyle selection and transaction governance deserve separate attention.
The framework below is a recommended buyer-side discipline, not a description of ONE Park Tower’s internal procedures or a statement of transaction-specific legal requirements. Counsel should determine which documents, approvals, and regulatory obligations apply to the proposed purchase.
First, distinguish the master community from the condominium transaction. Turnberry and LeFrak are partners in the broader SoLé Mia development. That relationship does not fully describe the tower’s project-level ownership or identify the entity signing a residence contract.
Project history also demands attention to dates. Rosso Development was previously associated with the condominium; by March 27, 2024, it was no longer a project partner. An older brochure should therefore not determine the counterparty recorded in a current approval memorandum.
A useful ownership file would separate three layers:
Master development: identify the community-level parties without presuming they guarantee the condominium transaction.
Project and seller: have counsel establish the parcel owner, contracting seller, signatory authority, and any expressly documented guarantee or completion obligation.
Purchaser: map the buying entity, its ownership and control, and the individuals authorized to approve and execute the acquisition.
Do not assume these layers share obligations merely because their names appear together in marketing. A family considering Turnberry Ocean Club Sunny Isles in Sunny Isles Beach should likewise avoid carrying an ownership conclusion from one transaction into another. Each purchase deserves its own counterparty review.
A family-office approval should do more than endorse a desirable residence. As a recommended internal practice, prepare a concise decision memorandum identifying the proposed buyer, intended use, selected residence, proposed commitment, and unresolved conditions. Complete those fields using the actual transaction documents, not general project descriptions.
Separate the commercial decision from signing and payment authority. The person approving the acquisition may not be authorized to execute the contract or release a deposit. A written authority schedule can identify the approver, signatory, payment initiator, and payment reviewer, supported by entity resolutions or other authority documents as counsel considers appropriate.
The memorandum should also specify what requires renewed approval: a buyer-entity change, a different funding account, an amended payment schedule, or a material contract revision. These are proposed governance triggers, not stated developer requirements.
For a family also evaluating Rivage Bal Harbour, a consistent approval template can organize comparisons without implying equivalent ownership structures, contract terms, or delivery risk. Standardize the questions, not the answers.
The funding file should connect the purchasing entity to the capital intended for the transaction. As a buyer-side recommendation, begin with a short funding narrative: whose money is being used, where it is held, whether it will move between entities, and which account will send each payment.
Then agree with counsel, the bank, and the closing team on the supporting evidence. Depending on the structure, that might include relevant account records and documents explaining a distribution, asset sale, intercompany loan, or capital contribution. These are illustrative records, not a universal checklist or a statement of this project’s requirements.
If the account holder differs from the buyer, resolve the explanation before initiating payment. The objective is a coherent chain linking the approved purchaser, the authorized funding arrangement, and the remitting account. Update the narrative to reflect any later changes.
Identity and ownership information warrants discretion. A sensible internal protocol would limit access, designate an approved delivery channel, and avoid circulating sensitive records in broad email chains. Confirm what is needed before distributing a complete family ownership archive.
Source-of-funds preparation does not establish whether a transaction is reportable. Counsel and the closing team should confirm the operative rules, effective-date status, transaction coverage, exceptions, and responsible reporting party before treating any filing as required.
The federal residential real-estate reporting framework identifies an entity’s beneficial owners by substantial control or ownership or control of at least 25 percent of its interests, directly or indirectly, at closing. Relevant identity fields include legal name, date of birth, residential address, citizenship, and an identifying number; trusts involve their own relevant ownership categories.
Treat those concepts as preparation points, not a conclusion that every purchaser must file. Payment-account reporting also includes stated exceptions for certain escrow- or trust-account payments. Neither using an entity nor routing money through escrow, by itself, settles the transaction’s reporting treatment.
Wire instructions should undergo independent verification, not be accepted because an email looks familiar. Recommended buyer-side controls include confirming instructions through a previously established, independently verified telephone number and separating payment preparation from final authorization.
Record the intended recipient, account details, payment purpose, verification contact, and approval. Before release, a second authorized reviewer should compare the proposed transfer with the verified instructions and approved transaction schedule.
A changed beneficiary, account, or delivery instruction should trigger a pause and fresh verification. Do not use contact information supplied only in the message announcing the change. Establish an escalation path with the bank and counsel before payment day, including whom to contact immediately if a transfer appears misdirected.
These controls are recommendations, not verified ONE Park Tower procedures. They should supplement, rather than replace, the bank’s and closing team’s instructions.
The project secured a $172 million construction loan from Bank OZK in March 2024. It was approximately 60 percent presold that month-a historical sales position, not a measure of current availability. The tower topped out in April 2025, a construction milestone rather than confirmation of completion or occupancy.
For the purchase decision, anchor the file in the Florida prospectus and legally required purchaser documents, not renderings, advertising, floor plans, or oral representations. Before each commitment, reconcile the current contract, authority documents, funding plan, and verified payment instructions. A compelling residence merits equally disciplined execution.
For a discreet conversation about your South Florida residence search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe condominium is located at 2411 Laguna Circle, North Miami, Florida 33181, within the 184-acre SoLé Mia community.
The project is described as a 33-story condominium with 292 residences overlooking SoLé Mia’s seven-acre Crystal Lagoon.
No. Turnberry and LeFrak’s master-development partnership should be distinguished from the condominium’s project structure and the seller named in the purchase contract.
Rosso was no longer a project partner by March 27, 2024. Current transaction documents should guide the counterparty review rather than early marketing materials.
A recommended approval memorandum identifies the purchaser, intended use, residence, commitment, unresolved conditions, and signing and payment authority. Counsel should determine the appropriate supporting authority documents.
It should explain the proposed capital source, any transfers between entities, and the account expected to remit payment. Supporting records should be agreed with counsel, the bank, and the closing team.
No blanket filing conclusion follows from the proposed entity structure. Counsel should confirm operative rules, transaction coverage, exceptions, and the responsible reporting party.
A recommended control is to pause payment and independently reverify the change using an established contact channel. Obtain renewed authorization before releasing funds.
No. Topping out is a construction milestone, not confirmation of completion or occupancy; the March 2024 presale percentage is also historical rather than current.
The Florida prospectus and legally required purchaser documents should anchor the decision, rather than advertising, renderings, floor plans, or oral representations.