A disciplined ownership file separates Florida condominium association recordkeeping duties from a family office’s private transaction controls, connecting deposit decisions, payment instructions, approvals, and long-term document stewardship.
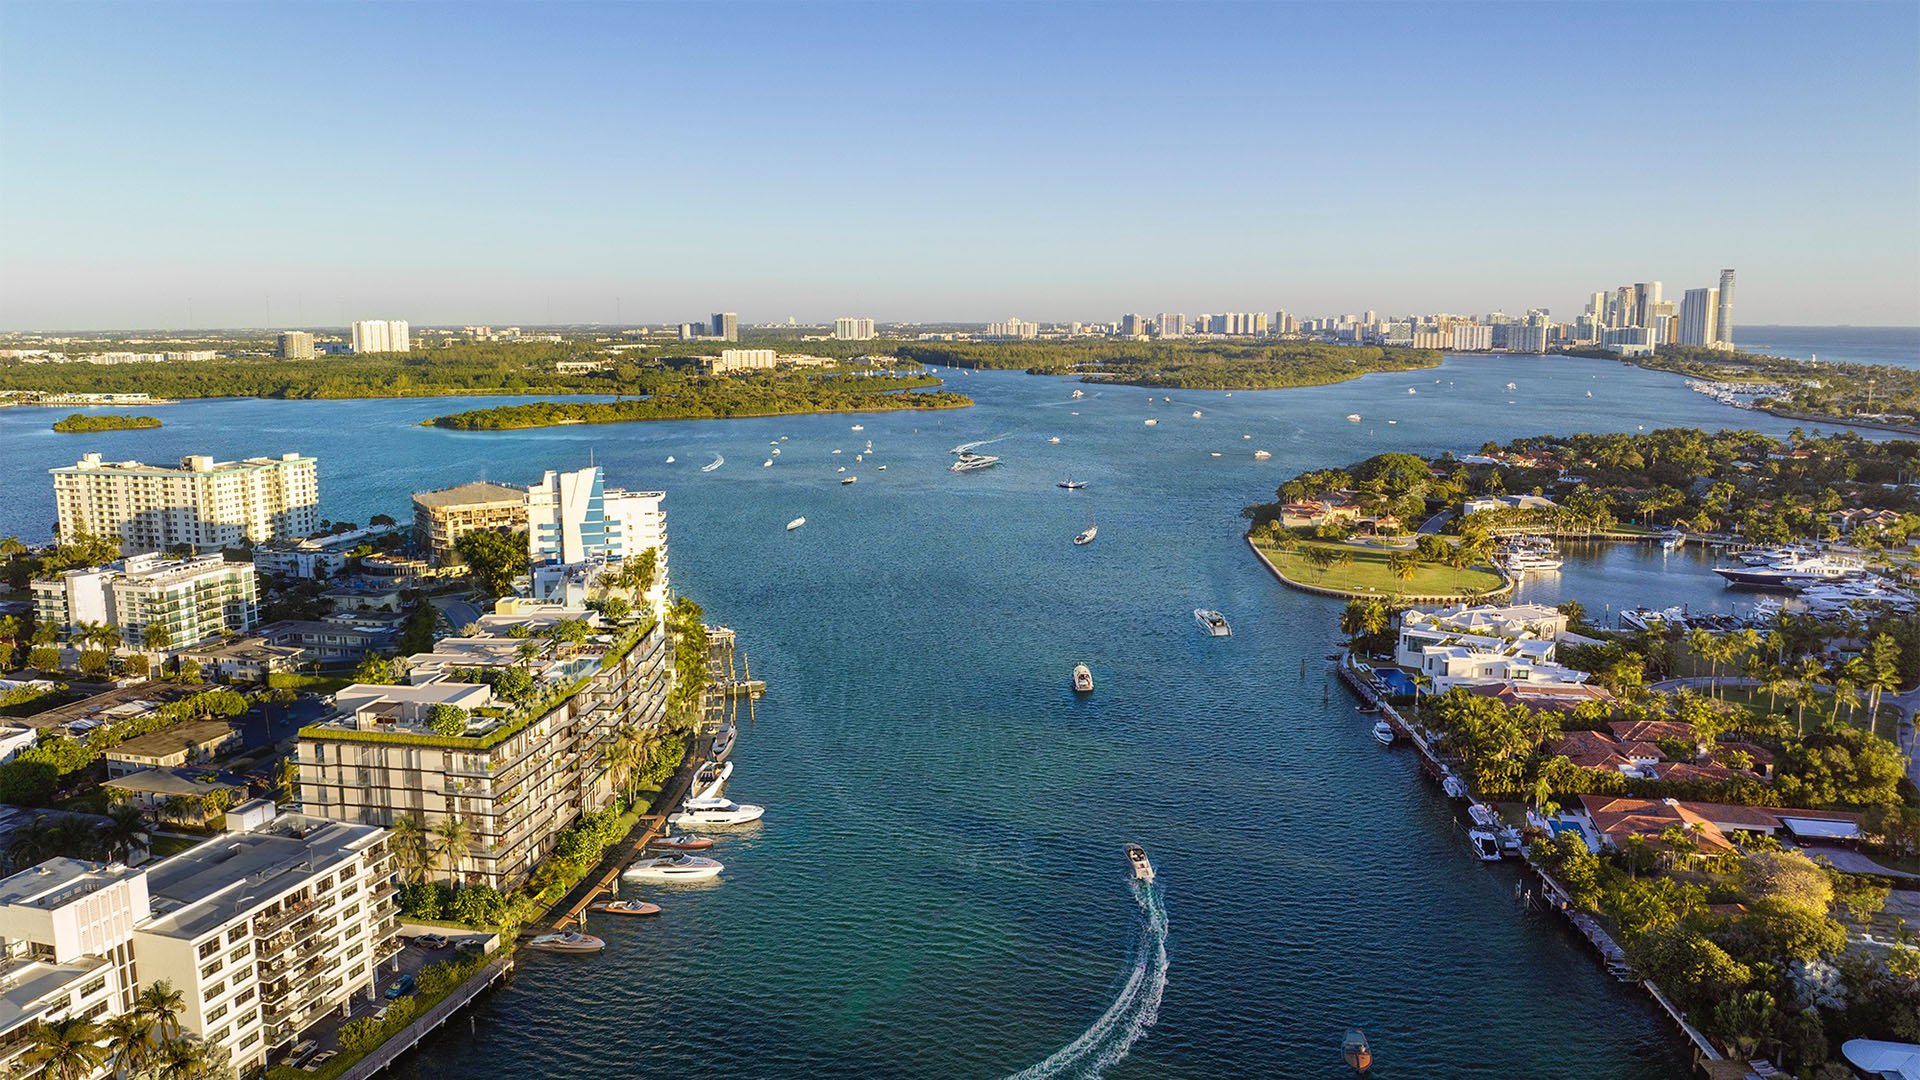
A luxury condominium purchase deserves a file as considered as the residence itself. For a family office evaluating Bay Harbor Islands alongside Bal Harbour, the objective is more than collecting closing documents. It is to preserve a clear account of what was approved, who had authority to approve it, where funds were directed, and which documents support ongoing ownership.
That discipline can begin while considering Alana Bay Harbor Islands, before selecting a unit or contract. The property search and the ownership process should remain distinct: an appealing residence does not resolve questions of payment authority or document custody.
The essential distinction is both legal and practical. Florida’s condominium recordkeeping requirements govern association official records. They do not establish a comprehensive retention schedule for a family office’s private acquisition file. The transaction controls below are proposed internal policies to discuss with advisers-not Florida legal requirements or representations about any named project.
A useful private file begins with ownership and authority. As an internal policy, the family office could identify the intended purchaser, the authorized signatory, the person responsible for reviewing payment requests, and the person permitted to release funds. If an entity will purchase, counsel can determine which authority documents belong in that section.
Separate the decision to acquire the residence from approval of each payment. The office might adopt a written approval matrix specifying who reviews contractual obligations and who authorizes disbursement. A second approval can serve as an elective control; it should not be described as a condominium-law requirement.
The file should also distinguish internal authorization from any transaction-specific approval. Do not assume every purchase follows the same approval process. Ask counsel to identify the requirements in the governing and transaction documents, then record their status without treating an internal checklist as legal clearance.
For every proposed deposit, consider creating a single record linking the relevant contract provision, requested amount, due date, intended recipient, internal approval, and payment evidence. These are suggested file fields, not a prescribed Florida deposit procedure. The applicable transaction documents should determine the actual obligation.
This distinction matters when evaluating Bay Harbor Towers or another residence: the ownership file should reflect the specific agreement, not assumptions carried over from another acquisition. No deposit amount, timing, or refund condition should be inferred from the project name.
Keep proposed, approved, and completed payments visibly separate. Approval does not establish that funds arrived, and a transfer confirmation does not by itself establish that every contractual condition was satisfied. As a proposed reconciliation step, the office can link payment evidence to recipient acknowledgment and flag unresolved differences for its advisers.
Payment instructions and authority to pay answer different questions. One identifies the destination presented for a transfer; the other records the family office’s decision to release funds. A proposed workflow should preserve both without allowing either to substitute for the other.
The office could verify instructions through a separately established contact channel and document who performed the verification. A callback and independent approval may form part of an internal policy, but they are not established here as Florida statutory requirements or independently verified best practices.
Revised instructions should remain distinguishable from the versions they replace. Consider pausing release until the change has been reviewed and reapproved under the office’s policy. Preserve the instructions, verification note, authorization, and transfer evidence together. No checklist should be treated as a guarantee against payment error or fraud.
The association’s official-record obligations provide a separate framework for understanding the documents an owner may need to consult. Recorded declarations and amendments, recorded bylaws and amendments, and articles of incorporation and amendments must be retained permanently. Current association rules and developer-provided plans and permits also belong in the association’s permanent records, as do association meeting minutes.
For a buyer considering La Maré Bay Harbor Islands, these categories can guide questions about the governing record set without implying anything about that project’s documents or compliance.
Most other condominium official records must be retained for at least seven years unless another requirement applies. The financial category includes bank statements, ledgers, receipts, invoices, and unit account statements. Association audits, financial reports, and contracts are also covered by the seven-year retention guidance. These periods describe association duties-not automatic deletion dates for an owner’s copies.
Structural integrity reserve studies and related inspection or life-safety reports have a 15-year retention period. Bids for work or materials generally must be retained for at least one year after receipt. A single seven-year label therefore cannot accurately describe the association’s entire archive.
Associations must organize official records to facilitate inspection by unit owners. They generally must make those records available within 10 working days after receiving a written inspection request. Failure to provide access within the statutory period may create a presumption of willful noncompliance.
Keep that access framework tied to unit-owner rights. It should not be presented as an unconditional pre-purchase entitlement for a prospective buyer. For the private file, consider retaining written requests, receipt dates, responses, and an index of materials received. Counsel can assess access rights and unresolved issues in the particular circumstances.
A family office considering The Well Bay Harbor Islands can use the same organizational approach without assuming association deadlines govern its own archive. Ask legal and tax advisers to define the private file’s retention policy around the ownership structure, transaction, and ongoing obligations.
An elective folder structure might separate authority documents, contracts and amendments, deposits, wire instructions, approvals, closing materials, and association records. Identify final versions clearly and preserve the connection between each decision and its supporting documents.
Access permissions, encryption, backup arrangements, and deletion approvals also belong in a separately designed internal policy. They should not be represented as duties established by condominium retention rules. Where a record has continuing relevance, seek advice before applying a routine disposal date.
The proposed closing review is straightforward: connect the executed agreement and amendments to approved payments, transfer evidence, and final closing materials. Mark discrepancies as unresolved rather than allowing an incomplete file to appear finished. Assign responsibility for maintaining the archive after closing.
A well-considered ownership file makes the purchase understandable later without confusing private controls with association law. Its value lies in continuity: the next adviser should be able to distinguish what was required, what was approved, what occurred, and what still needs attention.
Explore Bay Harbor Islands residences with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. They govern condominium association official records, not a comprehensive retention schedule for a family office’s private acquisition file.
Recorded declarations and amendments, recorded bylaws and amendments, and articles of incorporation and amendments must be retained permanently. Current rules, developer-provided plans and permits, and meeting minutes also belong in the permanent record categories.
Most must be retained for at least seven years unless another retention requirement applies. That period is not an automatic disposal date for a family office’s private copies.
The category includes bank statements, ledgers, receipts, invoices, and unit account statements. Association audits and financial reports are also covered by the seven-year guidance.
Structural integrity reserve studies and related inspection or life-safety reports have a 15-year retention period under condominium records guidance.
Bids for work or materials generally must be retained for at least one year after receipt.
Associations generally must make official records available within 10 working days after receiving a written inspection request. This unit-owner access framework should not be assumed to give prospective buyers an unconditional entitlement.
They are presented here only as proposed internal controls for a family office to consider with advisers. The condominium recordkeeping rules discussed do not establish those procedures as legal requirements.
A proposed record could connect the contract provision, requested amount, due date, recipient, approval, and payment evidence. The actual payment obligation should be determined from the applicable transaction documents.
The association’s seven-year requirement does not establish a private buyer-file disposal schedule. Legal and tax advisers should help define the family office’s own retention policy.