Making a South Florida second home your primary residence calls for more than an address change. A carefully assembled file separates occupancy, loan obligations, signing authority, international authentication, and document security without assuming every conversion requires refinancing.
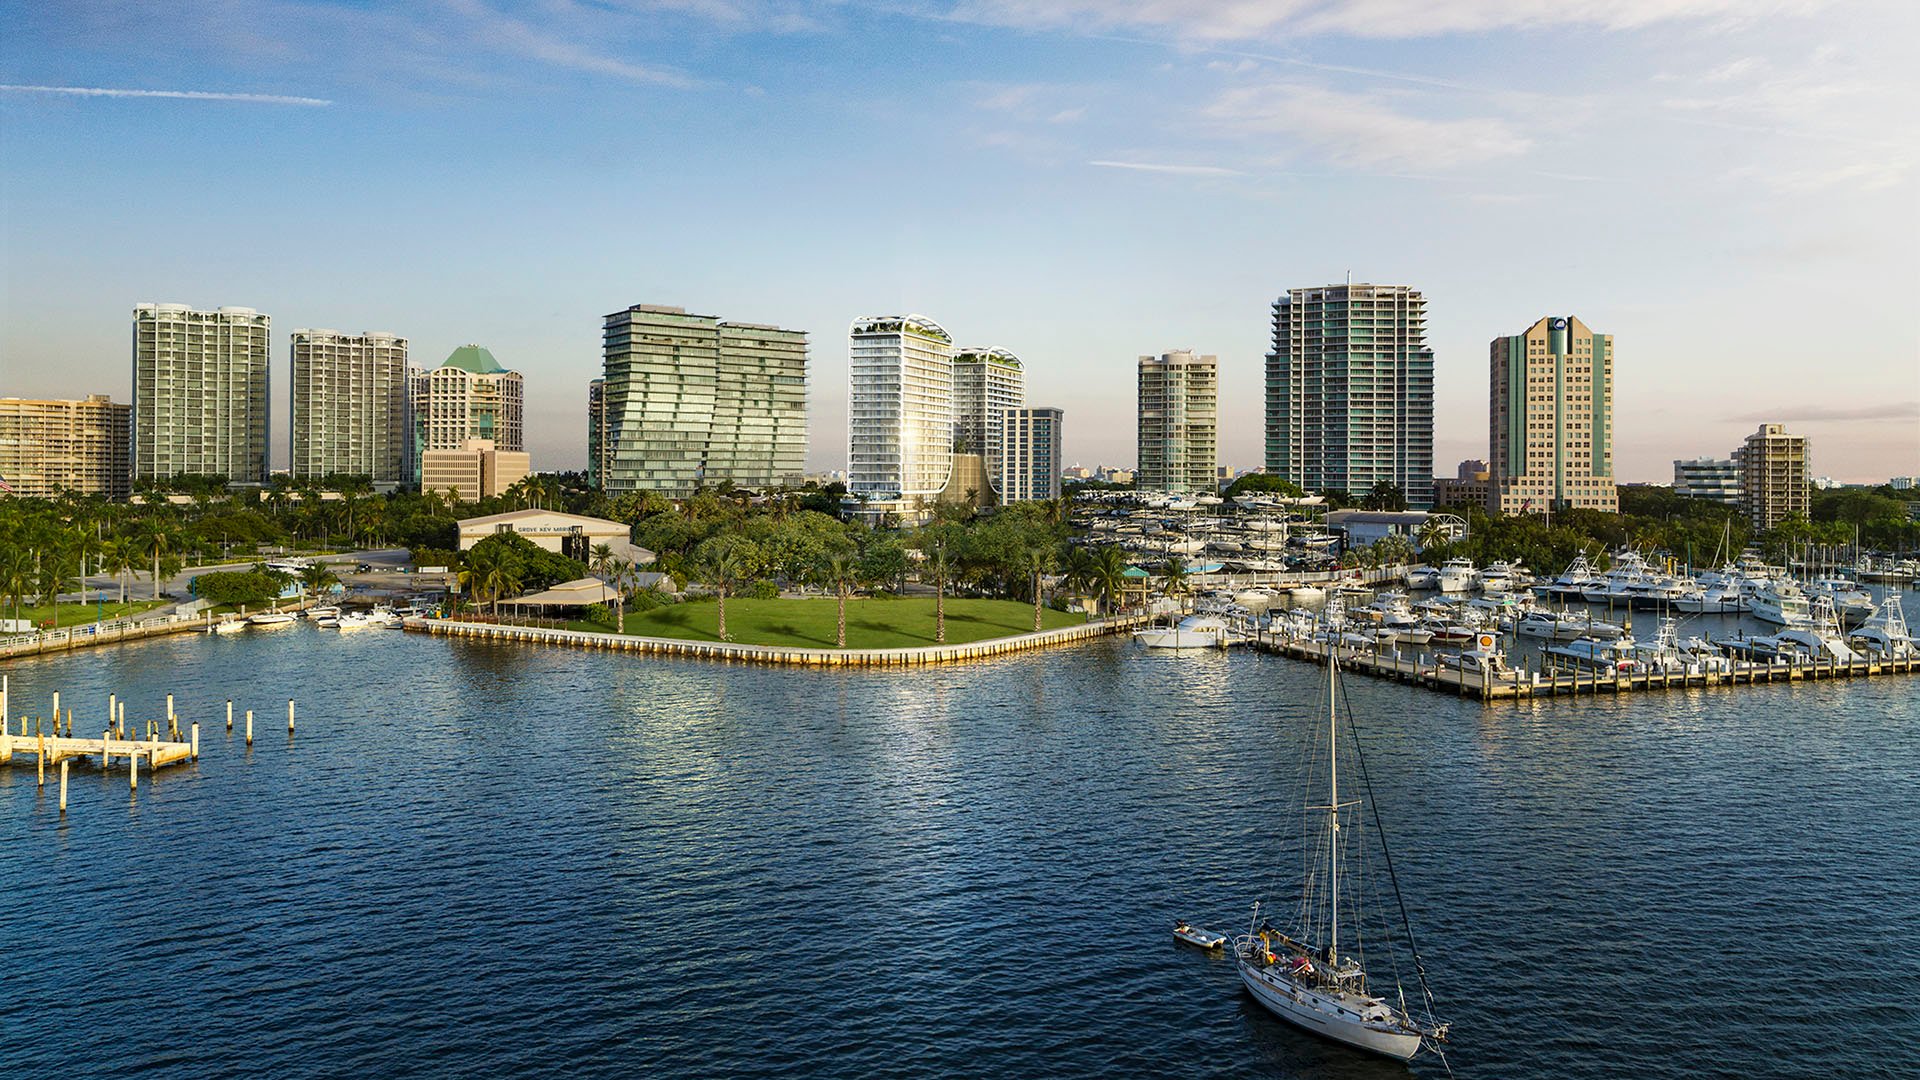
A South Florida home can become the center of daily life long before its paperwork catches up. For an owner considering that transition at Una Residences Brickell, the essential question is not simply where correspondence arrives. It is whether actual occupancy, financing representations, and supporting documents tell a consistent story.
The same discipline applies when buying a residence initially intended for seasonal use. Separate five questions: how the property will be occupied, what the loan documents require, who will sign, how signatures will be authenticated, and who must accept the resulting documents. Notarization, lender acceptance, and international authentication are distinct matters.
The mortgage considerations below concern a particular conventional-loan framework, not every financing program. The notarization rules concern Florida. Treat the file as a framework for discussions with counsel, the lender or servicer, and any title professionals involved-not as a universal conversion checklist.
Under the conventional-loan framework addressed here, a principal residence is occupied by the borrower as their primary residence. A second home is occupied for part of the year and must satisfy additional conditions, including that it is not a timeshare. These categories concern use, not merely the owner's preferred designation.
Prepare a dated account of the intended transition and retain relevant correspondence. Ask the lender what supporting information it needs. Do not revise the history of earlier occupancy to simplify the file; distinguish the original arrangement from the subsequent change.
A rental history deserves separate attention. Identified rental income does not automatically disqualify a second-home loan under this framework, provided that income is not used for qualification and all other second-home requirements are met. This is not blanket permission for every rental arrangement. Explain the facts rather than assuming a label resolves them.
Do not assume that moving into a second home automatically requires written approval, a loan modification, or refinancing. Nor should you assume the loan documents can be ignored because primary-residence occupancy may be viewed as lower risk than second-home or investment occupancy.
For exempt property transfers under this framework, an occupancy change must not violate the security instrument, including any applicable principal-residence occupancy requirement. This transfer-specific provision does not establish an approval requirement for every occupancy conversion.
For a Miami Beach owner considering a transition at Setai Residences Miami Beach, the next step is a loan-specific inquiry. Ask whether notice, consent, additional documentation, or another action applies to the proposed change. Request a written response for clarity, not because written approval is universally mandatory.
Keep the existing loan documents, your inquiry, and the response together. If refinancing is proposed, ask why it is recommended and assess its terms separately from the decision to live in the property.
Florida permits qualified notaries who complete the required application and training process to perform remote online notarizations. The online notary must be physically in Florida. The principal and witnesses may be outside the state, subject to statutory requirements.
The process includes confirming the identity of the principal and any witnesses appearing online and recording the two-way audio-video conference. If the principal is outside Florida, the notary must confirm verbally or in writing that the principal wants the notarization performed by a Florida notary under Florida law.
Florida also requires the notary's electronic signature to be unique, independently verifiable, under the notary's sole control, and linked to the document so later alterations are detectable.
Before arranging a session, ask the intended recipient whether the proposed document and execution method are acceptable. A legally available notarization route does not, by itself, establish acceptance by a lender, title company, recording office, or foreign authority. Confirm the signing plan before travel schedules make changes inconvenient.
An apostille authenticates a public document's origin for international use. It does not establish the truth of the contents, repair improper execution, or replace notarization where required. Nor does it guarantee acceptance by the receiving institution.
Florida's apostille and notarial-certification process requires a completed state request form and the document to be authenticated or certified. Before pursuing that process, ask counsel and the intended recipient which authentication route applies to the document's destination and purpose.
For an owner planning a move to Park Grove Coconut Grove while coordinating signatures abroad, the key distinction is between completing the document correctly and authenticating its origin. Resolve both questions before treating the international portion of the file as complete.
If someone else may sign on your behalf, submit the proposed power of attorney for review early. Ask counsel what authority is needed for the specific documents, and ask each relevant recipient what it will accept. Do not assume a general authorization will satisfy a particular transaction.
Avoid blanket assumptions about mandatory forms, wet-ink originals, execution dates, or acceptance of documents prepared abroad. Establish the requirements for your circumstances before execution, including whether any planned remote notarization or international authentication is acceptable.
For a Fort Lauderdale buyer evaluating Four Seasons Hotel & Private Residences Fort Lauderdale, this calls for advance coordination, not a last-minute substitute for personal attendance. Keep the reviewed authorization and recipient correspondence with the documents they are intended to support.
Occupancy representations may be checked through post-closing quality-control reviews. Property-insurance policies and related documentation can form part of occupancy reverification. Consistency therefore matters beyond the initial declaration.
Ask the insurance adviser whether the planned use calls for changes to coverage or documentation. Do not assume every conversion requires a replacement policy. Address any homestead or other tax questions separately with the appropriate adviser rather than treating a mortgage occupancy designation as a tax determination.
The mortgage framework addressed here includes fraud controls and quality-control procedures, including heightened sampling of loans presenting high fraud risk. As practical precautions, use secure document delivery, limit unnecessary circulation of identity materials, and independently confirm sensitive payment instructions through an established contact. These are recommended safeguards; not every step is mandated by that framework.
Before considering the transition documented, identify any unresolved lender instruction, signing-authority question, authentication step, or insurance review. Assign each to the responsible professional and retain the final responses. The objective is an accurate record of the home you now occupy, not simply a thicker folder.
For a considered approach to your next South Florida residence, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationUnder the conventional-loan framework discussed, a primary residence is occupied as the borrower's principal home, while a second home is occupied for part of the year. Additional second-home eligibility conditions also apply.
A universal approval requirement should not be assumed. Ask the lender or servicer which notice, consent, or documentation requirements apply to your loan and intended change.
Refinancing is not established as a universal requirement for this transition. Review the existing loan documents and request loan-specific guidance before deciding.
Not under the conventional-loan framework discussed, provided the rental income is not used for qualification and all other second-home requirements are met. This is not blanket approval of every rental arrangement.
Florida permits this subject to statutory requirements, while the notary must be physically in Florida. The notary must also confirm that you want the notarization performed under Florida law.
The process includes identity confirmation and a recorded two-way audio-video conference. The notary's electronic signature must also meet verification, control, and alteration-detection requirements.
An apostille authenticates a public document's origin for international use, not the truth of its contents. It does not correct improper execution or guarantee recipient acceptance.
Do not assume acceptance. Have counsel review the authority needed and confirm the applicable requirements with each relevant recipient before execution.
A universal replacement requirement should not be assumed. Ask your insurance adviser whether your planned use calls for coverage or documentation changes, especially because insurance records may inform occupancy reverification.
As practical precautions, use secure document delivery, restrict unnecessary sharing of identity materials, and independently verify sensitive payment instructions through an established contact. These recommendations are not presented as universal mortgage-program mandates.