For a Greenwich family office considering Bay Harbor Islands, the purchase deserves a treasury plan as carefully considered as the residence itself. Contrasting deposit schedules reveal how currency exposure, contractual deadlines, and closing liquidity should be evaluated separately.
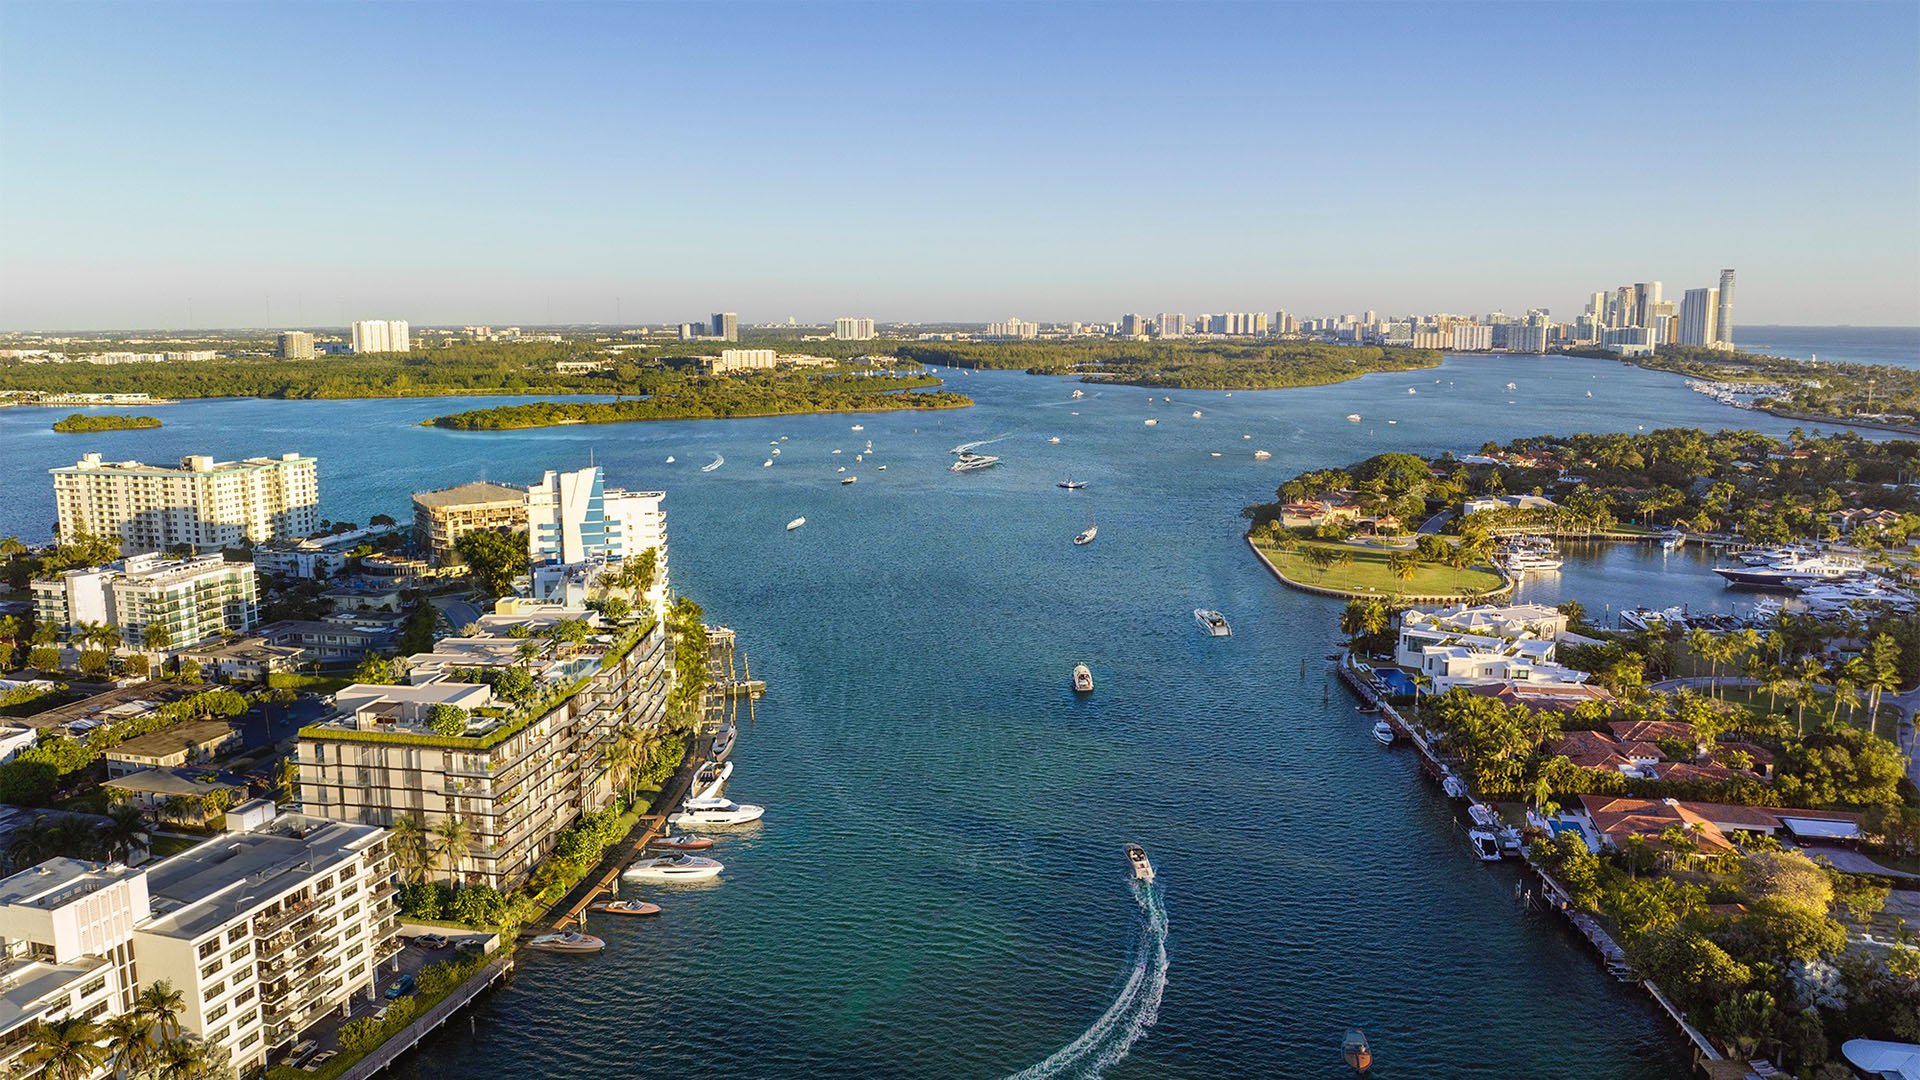
For a Greenwich family office considering a residence in Bay Harbor Islands, the most consequential design exercise may be the liquidity plan. A household can select its preferred address while its capital remains spread across currencies and accounts. The practical question is not simply whether the purchase is affordable, but when dollars must be available and which obligations they must satisfy.
Treat the relocation and the property acquisition as related but separate decisions. A Florida residence does not, by itself, resolve Greenwich-specific tax or residency questions. Those require individual advice. The acquisition plan should begin more narrowly: establish the contractual payment calendar, identify the intended funding accounts, and distinguish the unpaid purchase price from the cash needed around and after closing.
The payment schedule defines the funding obligation, not the optimal exchange date.
At Bay Harbor Towers, located at 10141 East Bay Harbor Drive, two published marketing schedules illustrate why a family office should not translate a sales summary directly into treasury instructions.
One schedule calls for 20% at contract, 10% at groundbreaking, 10% at top-off, and 60% at closing. Its intermediate payments are tied to construction milestones. The accompanying spring 2026 completion projection is an estimate, not confirmation of delivery.
A separate schedule calls for 20% at contract, 10% at 90 days, 10% at 180 days, and 60% at an estimated November 2026 closing. Under that structure, cumulative purchase-price deposits reach 40% by day 180. The remaining 60% still represents the majority of the purchase price.
These versions should remain separate. Combining the milestone triggers from one with the closing estimate from the other would create a payment calendar that neither establishes. Before committing funds, ask counsel to confirm the applicable installment amounts, triggers, notice provisions, and closing requirements in the transaction documents.
The topping-off milestone was documented on December 2, 2025. That provides context, but does not establish a buyer's current payment deadline or verify either completion estimate. For a purchase contemplated after a milestone, ask specifically how the proposed contract treats that installment rather than assuming it remains deferred.
The Well Bay Harbor Islands, a single tower containing 66 residences, presents a different published cash-flow profile: 10% at contract, another 10% 60 days after contract execution, and 80% at closing.
That places 20% of the purchase price before closing. The lighter initial commitment does not reduce the total purchase obligation; it concentrates more of that obligation in the final payment.
For a family office holding foreign-currency liquidity, this distinction matters. Compare not only the first deposit but also the largest future dollar requirement. An 80% closing balance and a 60% closing balance create different funding profiles, even before transaction expenses enter the calculation.
Neither profile establishes which residence is the better purchase or which currency approach is preferable. The useful comparison is how each schedule fits the family's available dollars, expected liquidity, and willingness to retain exchange-rate exposure before payment.
The published percentages establish purchase-price milestones. They do not identify a favorable exchange rate, an optimal conversion date, or a recommended hedge. A disciplined family-office discussion should keep those decisions separate.
Build a working calendar with a dollar amount beside each confirmed obligation. For every payment, record whether the trigger is a fixed date, elapsed time after execution, a construction event, or closing. Then identify which amounts are already held in dollars and which require conversion.
With that calendar in hand, ask the banking team to explain execution and settlement timing, applicable charges, and the conditions of any proposed currency arrangement. These are questions for the family's advisers, not reasons to assume a particular product is appropriate. Any conversion or hedging decision should reflect the actual contract and the family's broader liquidity position.
The central discipline is to avoid making contractual performance depend on a preferred exchange rate arriving just in time. A marketing completion estimate should not become the sole basis for deciding when to fund a binding payment.
Florida's broker escrow-handling rules operate on a different clock from the buyer's purchase contract. Real-estate associates and broker-associates must deliver escrow deposits to their broker by the end of the next business day after receipt. Brokers generally must deposit escrow funds within three business days of receipt.
Saturdays, Sundays, and legal holidays are excluded from those timing calculations. These rules govern the handling of money once received; they do not extend the buyer's contractual payment deadline.
For execution planning, ask the transaction team to identify the recipient, payment deadline, and required delivery procedure. Ask the bank separately about the transfer timetable. Keeping those instructions together, while distinguishing their purposes, helps prevent the family office from mistaking a handling rule for permission to pay later.
The closing balance is not the closing reserve. At Bay Harbor Towers, the published schedules leave 60% of the purchase price payable at closing; at THE WELL, the published schedule leaves 80%. Those percentages describe unpaid purchase price, not a complete cash-to-close budget.
Organize the liquidity plan into three categories: the remaining purchase-price obligation, transaction expenses and adjustments, and money intended to remain available after closing. Obtain transaction-specific figures for the second category and a household-approved budget for the third.
Consider furnishing plans and continuing liquidity needs separately from the purchase balance. No universal reserve percentage follows from these deposit schedules; assigning one would imply precision they do not provide.
Instead, maintain a clearly labeled working budget and update estimates as transaction figures become available. Counsel, the closing team, and the family's financial advisers can help distinguish confirmed obligations from discretionary allowances.
If the search also includes Alana Bay Harbor Islands, apply the same diligence without importing another development's terms into the comparison. Request the proposed schedule for the specific purchase, then assess its timing alongside the family's funding plan.
Before signing, the decision file should bring together the applicable payment schedule, unresolved timing questions, intended dollar funding, and a separate reserve budget. That clarity allows the residence to remain a lifestyle decision without making its execution an improvised currency decision.
For a discreet conversation about aligning your Bay Harbor Islands search with your acquisition priorities, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationOne lists 20% at contract, 10% at groundbreaking, 10% at top-off, and 60% at closing. Another lists 20% at contract, 10% at 90 days, 10% at 180 days, and 60% at closing; the applicable transaction documents need confirmation.
Cumulative purchase-price deposits reach 40% by day 180. The remaining 60% is payable at closing under that published schedule.
It lists 10% at contract, another 10% 60 days after contract execution, and 80% at closing. This places 20% of the purchase price before closing.
No. Spring 2026 and November 2026 appear as projections in different marketing materials, not verified delivery dates.
It documents Bay Harbor Towers' topping-off milestone. It does not establish a particular buyer's payment deadline or verify a completion estimate.
No. They establish payment milestones, not an optimal conversion date, exchange-rate forecast, or recommended hedging strategy.
Associates and broker-associates must deliver deposits to their broker by the end of the next business day after receipt; brokers generally must deposit funds within three business days of receipt. Saturdays, Sundays, and legal holidays are excluded from these calculations.
No. Broker handling deadlines are separate from the buyer's contractual payment obligations and should not be treated as extra time to pay.
These deposit schedules do not establish a universal reserve percentage. Separate the unpaid purchase price from transaction-specific expenses and the family's desired post-closing liquidity.
A property purchase alone does not answer those questions. Obtain individualized advice separately from the acquisition funding plan.