For yacht owners acquiring a South Florida residence, a disciplined closing strategy coordinates property insurance, lender acceptance, yacht coverage, and marina obligations without assuming that relief under one agreement protects the others.
For a yacht owner purchasing a South Florida residence, the closing date is only one part of the arrival plan. Property insurance must align with the purchase, financing must satisfy the lender, and the yacht needs both appropriate coverage and a workable dockage arrangement. Treat these as coordinated workstreams, not interchangeable protections.
A residential extension should never be assumed to extend a marina deadline, a yacht-policy obligation, or a lender commitment. Establish what each agreement requires before a storm threatens the timetable, then preserve written evidence if circumstances change.
For a buyer considering St. Regis® Residences Bahia Mar Fort Lauderdale, the same discipline applies: evaluate the residence purchase and any contemplated dockage arrangement separately. A project name or waterfront setting does not establish the buyer's contractual rights to a berth.
Begin with written confirmation from the insurance professional identifying the insured property, intended effective date, limits, deductibles, exclusions, and outstanding underwriting conditions. Ask what remains necessary to bind coverage and whether a weather-related restriction could prevent binding. A quote is not bound coverage, and neither a quote nor a broker's assurance substitutes for lender acceptance.
Do not assume a universal named-storm binding rule. Rather than assume that a storm's formation automatically stops coverage placement, request the carrier's position for the specific property and proposed effective date. If binding becomes unavailable, preserve the explanation and its timing.
For a purchase at Una Residences Brickell, focus the insurance inquiry on the actual residence and financing arrangement, not expectations associated with the building. The objective is a documented path from proposed coverage to effective coverage that the lender accepts.
Obtain the lender's transaction-specific insurance checklist early and request written acceptance of the proposed coverage. Track each outstanding condition. Insurance may be available while a financing condition remains unresolved; conversely, a lender's preliminary review does not establish that coverage has been bound.
Confirm the lender's requirements for approving the selected closing or title agent handling and disbursing its funds before treating the closing team as settled.
Keep ordinary closing obstacles visible alongside storm concerns. Association estoppels, unresolved liens, delayed payoffs, missing signatures, open permits, tax issues, and incomplete information can all delay a South Florida closing. A weather event should not obscure an unrelated deficiency or become the assumed explanation for every missed milestone.
Ask the closing team to maintain a single written status record identifying each outstanding item, the responsible party, and its effect on funding or completion. This is recommended transaction management, not a universal lender requirement.
Review the yacht's coverage separately. Ask the carrier to identify any named-storm deductible, navigation limit, seasonal restriction, hurricane-plan requirement, and haul-out or relocation condition. Request clarification wherever the proposed marina arrangement might conflict with those terms.
Do not assume a standard deductible percentage or relocation boundary. The applicable policy and endorsements define the obligations. If the vessel must move, the operational question is whether the owner can execute the required plan-not simply whether a plan exists on paper.
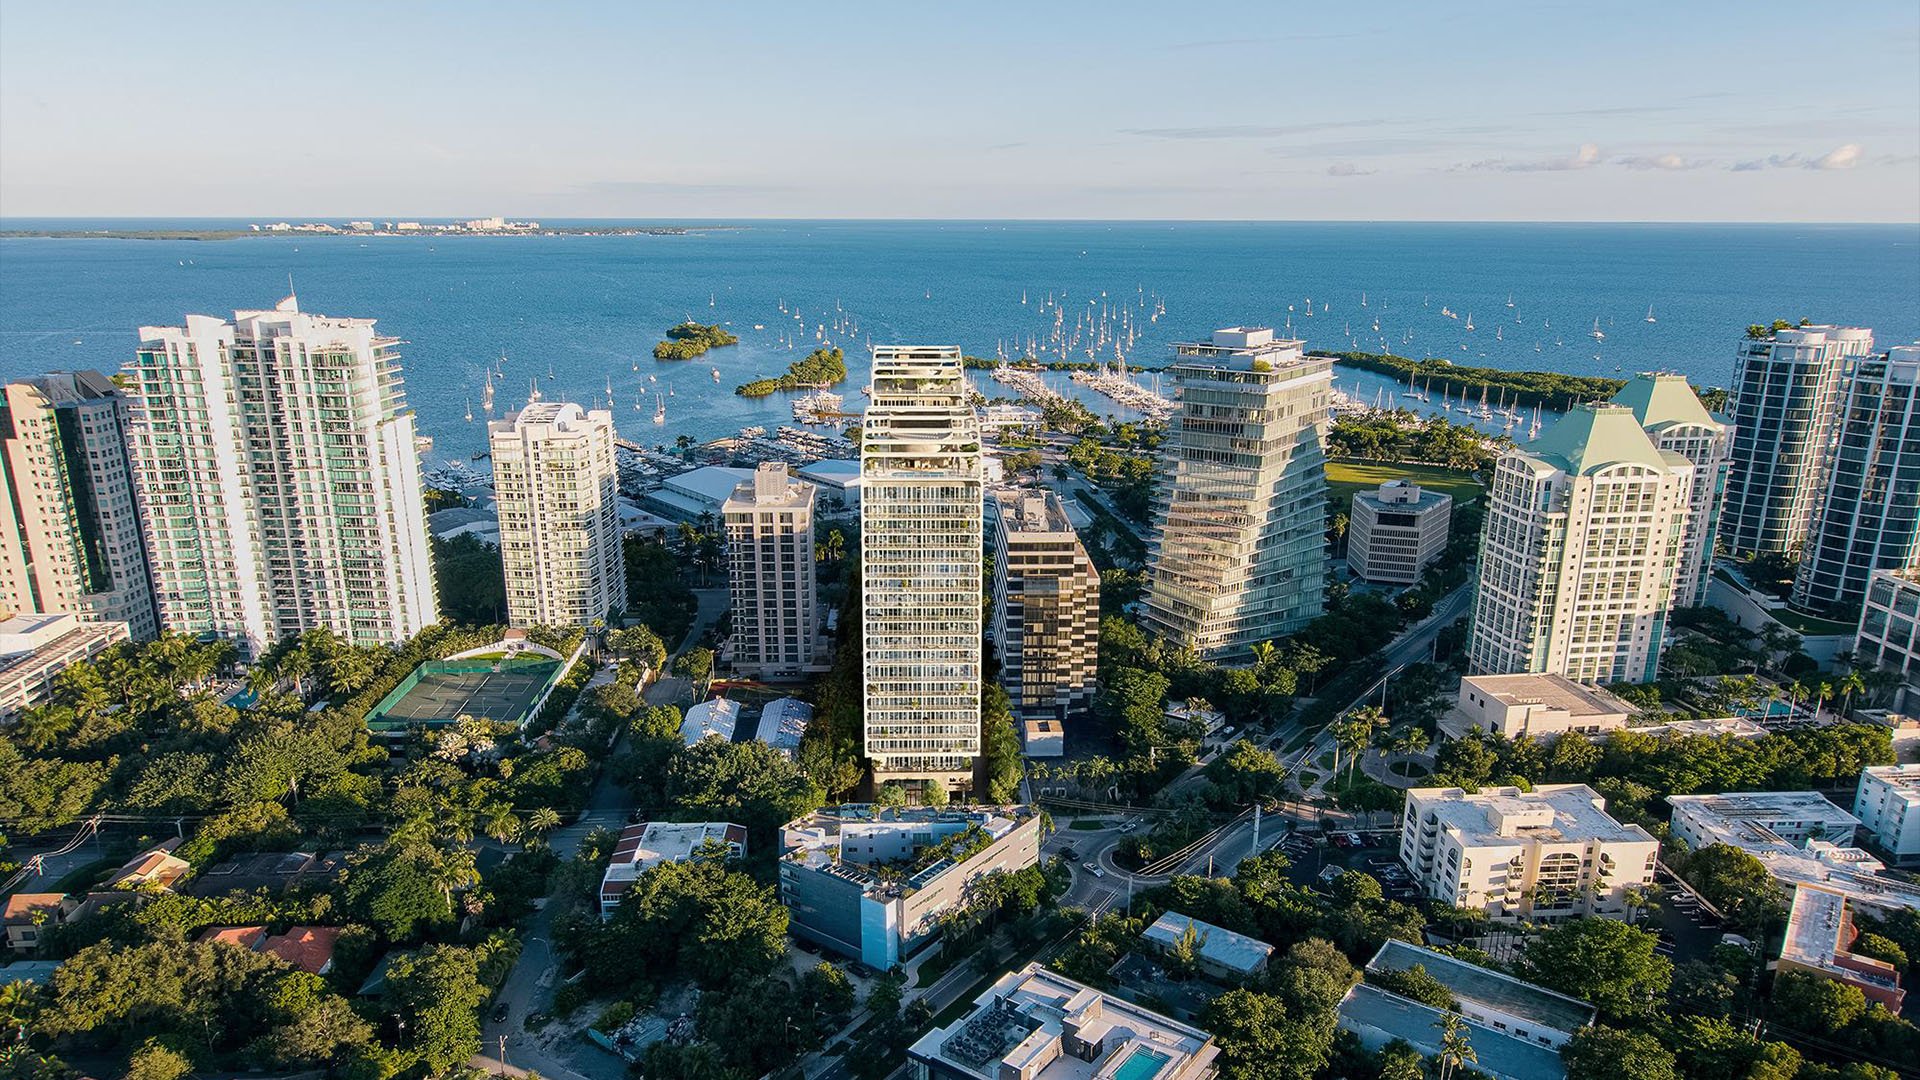
For buyers considering Vita at Grove Isle in Coconut Grove, keep residential selection distinct from verification of yacht logistics. Confirm contemplated dockage rights and storm procedures through the relevant agreements rather than inferring them from the residential offering.
Review the marina agreement for storm triggers, response deadlines, required insurance evidence, emergency access, and responsibility for lines and equipment. Establish who may act if the owner or captain cannot reach the vessel, and examine how the agreement allocates liability for emergency work.
Ask counsel to review any provision authorizing the marina to act if an owner fails to remove a vessel after a tropical-storm or hurricane watch. Confirm the applicable trigger, the owner's obligations, and the scope of the marina's emergency authority rather than assuming a blanket evacuation requirement.
Advance haul-out or relocation planning should address access and equipment responsibilities. Review any hold-harmless provision carefully, particularly language concerning accidental damage from emergency action or salvage. This planning guidance does not establish a marina's current terms or an insurer's requirements.
Confirm whether dockage or membership rights require separate transfer approval, what evidence of insurance is needed, and when access becomes effective. Align those dates with the yacht's intended arrival rather than relying solely on the residential settlement date.
Ask counsel to assess what happens if the residence closes before dockage approval, or if marina obligations begin while the residence closing is delayed. Identify any mismatch early enough to address it in the relevant documents, rather than assuming that one contract controls the other.
Do not assume that hurricane season alone permits postponement. Have counsel assess whether the signed agreement's force-majeure provisions apply to an actual prevention of performance or disruption of essential services, insurance, or approvals. Document whether the affected party could prevent or overcome the disruption through reasonably diligent efforts.
The signed agreement controls. General hurricane guidance cannot substitute for a review of its suspension, extension, and termination provisions. Before withholding performance, have counsel assess the actual impediment, applicable notices, and contractual consequences.
Preserve insurer correspondence, lender conditions, storm notices, and marina directives. Document efforts to overcome the disruption. If postponement is appropriate, separately confirm the status of financing, residential insurance dates, yacht coverage, and marina deadlines. An extension should resolve the residential timetable without creating an unnoticed gap elsewhere.
Before signing, consult an experienced Florida-licensed real-estate lawyer. Then bring counsel, the insurance professionals, lender, closing agent, and marina contact into a coordinated review of their respective obligations.
The final check should be straightforward: identify what is bound, what is accepted, what remains conditional, and who must act if weather changes the plan. For the yacht owner, a successful closing is more than a completed purchase. It is a residence and vessel arrival plan with contractual and operational obligations addressed separately and coherently.
Explore South Florida residences with MILLION while keeping your property and yacht arrangements aligned.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationDo not assume it does. Have counsel evaluate the actual impediment and the signed agreement's requirements for postponement.
No. A quote is not bound coverage, and lender acceptance is a separate step that should be confirmed in writing.
Request the insured property, effective date, limits, deductibles, exclusions, and outstanding underwriting conditions. Ask what remains necessary to bind coverage.
Do not assume a universal rule. Obtain the carrier's transaction-specific position for the property and proposed coverage date.
Review any named-storm deductible, navigation limits, seasonal restrictions, hurricane-plan requirements, and haul-out or relocation conditions in the applicable policy and endorsements.
Have counsel review the marina agreement's storm triggers, removal deadlines, and emergency authority. Confirm who may act if the owner or captain cannot reach the vessel.
Do not assume it does. Marina deadlines, yacht-policy obligations, and lender commitments must be checked separately.
Confirm the lender's requirements for approving the closing or title agent handling and disbursing its funds. Resolve any required approval early in the transaction.
Potential obstacles include lender conditions, association estoppels, unresolved liens, payoff delays, missing signatures, open permits, tax issues, and incomplete information.
Keep insurer correspondence, lender conditions, storm notices, marina directives, and documentation of efforts to overcome the disruption. Have counsel evaluate the signed contract before withholding performance.