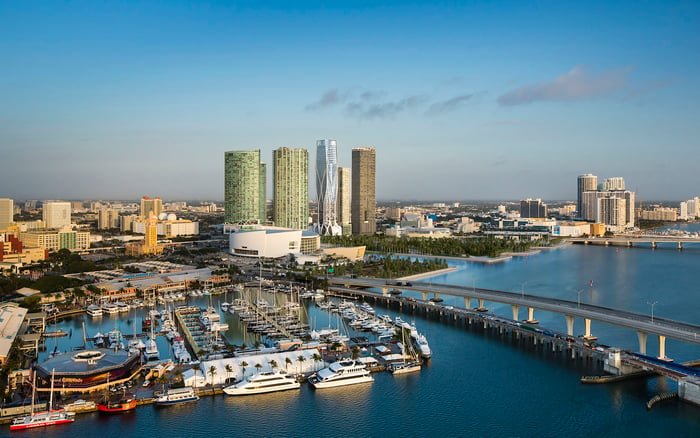
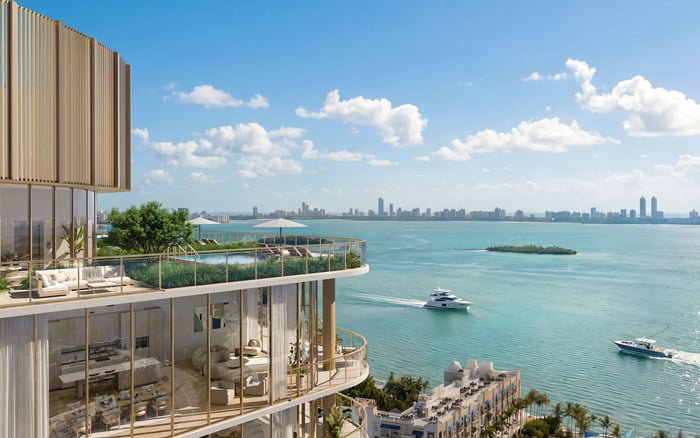
FinCEN’s residential real estate reporting rule is vacated, with an appeal pending in the early-October 2026 snapshot. For yacht owners, the distinction between federal filing obligations, closing-team diligence, and separate marina commitments is essential to coordinating a residence purchase.
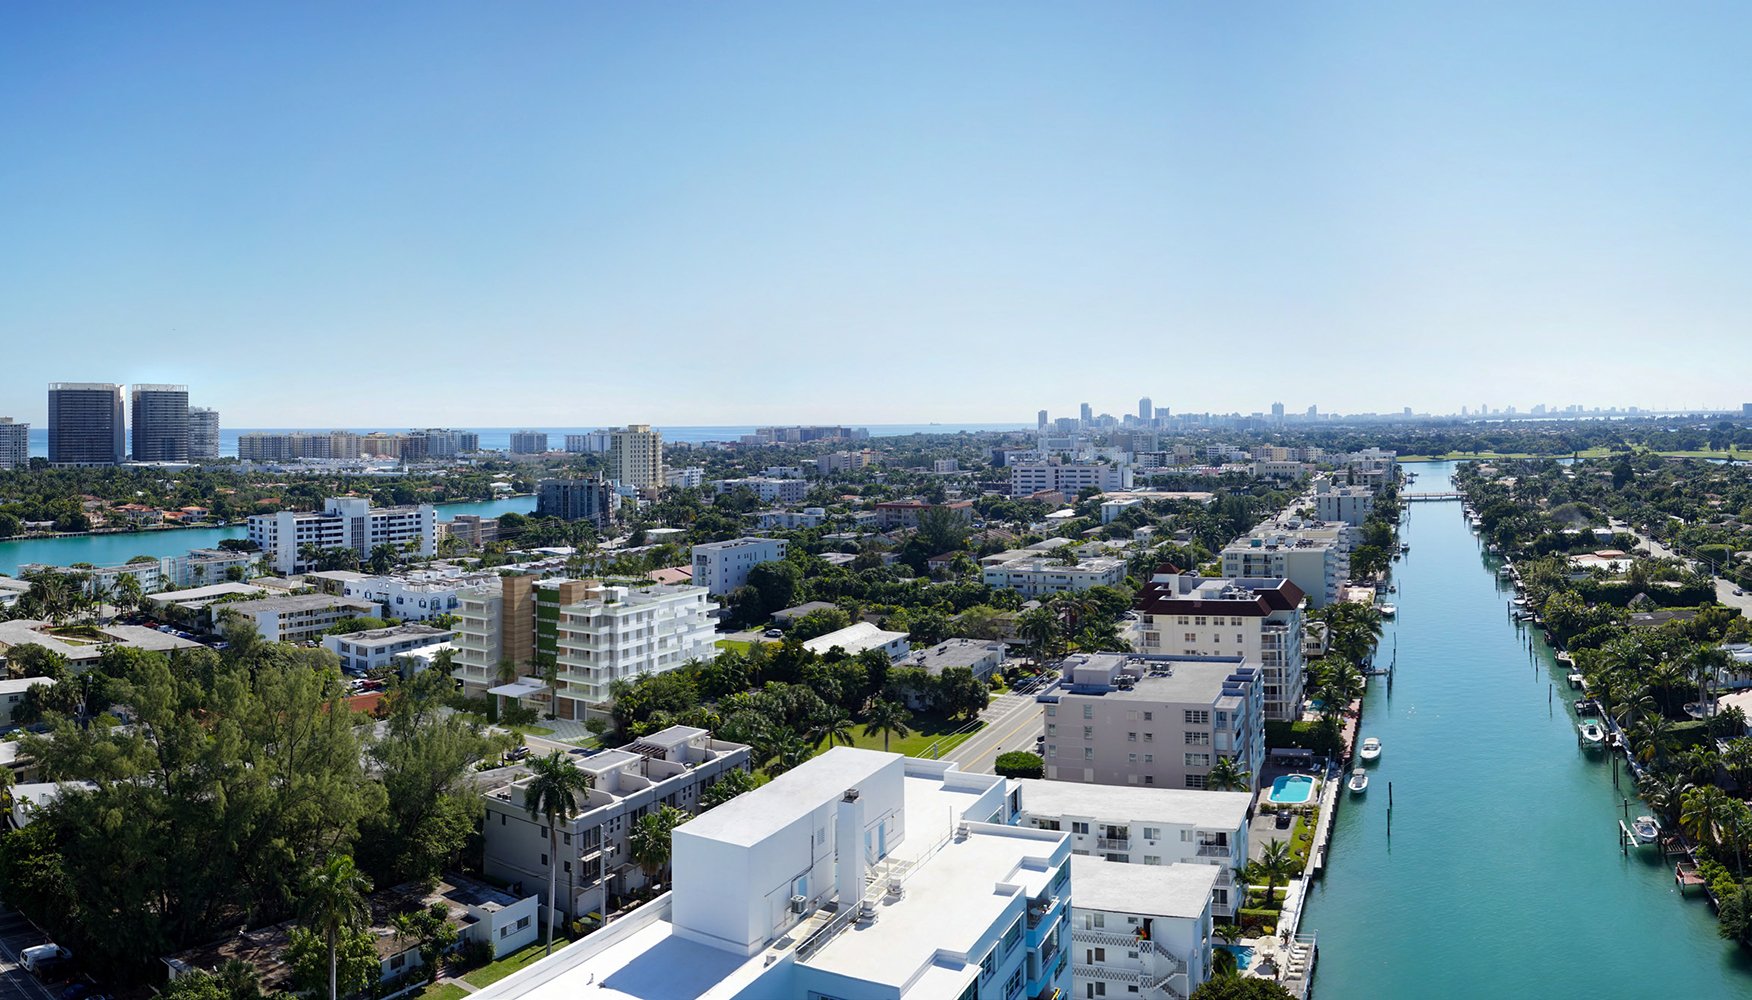
For a yacht owner acquiring a South Florida residence, the closing date can anchor a broader calendar: dockage, club membership, vessel management, insurance, and the yacht’s arrival. The residence and those marine arrangements call for coordinated planning, but they should not be assumed to share legal obligations or cancellation rights.
That distinction matters amid the 2026 litigation over FinCEN’s Residential Real Estate Reporting Rule. As of early October 2026, the rule is vacated, with an appeal pending, not permanently repealed. While the court’s order remains in force, reporting persons need not file Real Estate Reports and face no liability for failing to file during that period.
The practical implication is narrower than a general reprieve from paperwork. Buyers should distinguish the federal filing position from independent closing requirements, then review whether residence and marina contracts remain financially aligned if the purchase is delayed.
On March 19, 2026, the U.S. District Court for the Eastern District of Texas vacated the rule nationwide in Flowers Title Companies, LLC v. Bessent. The court held that FinCEN lacked statutory authority under the Bank Secrecy Act to impose it. FinCEN, working with the Department of Justice, appealed.
The timing requires precision. Exemptive relief had deferred compliance from December 1, 2025, until March 1, 2026. That compliance date was not the rule’s original effective date, and residential transfers closing before March 1 were outside its reporting implementation schedule. Descriptions of mandatory reporting beginning in March explain the implementation plan, not the post-vacatur filing position.
For a pending purchase, neither an old closing checklist nor an assumption of permanent relief is sufficient. Ask counsel to confirm the litigation posture before signing and again before closing. The early-October position is a planning reference, not an assurance that the same conditions will govern a later settlement.
The rule targeted certain non-financed transfers of residential property to legal entities or trusts-not every residential purchase. Depending on the property and transaction structure, its scope could include one-to-four-family properties, condominiums, and cooperative interests. An ordinary commercial-property transaction was not its target simply because the purchaser used an entity or trust.
For a buyer considering Una Residences Brickell, the relevant legal questions concern the proposed transaction: who takes title, how the purchase is financed, and which property interests are conveyed. Neither the project name nor the buyer’s yacht ownership answers those questions.
Historically, filing responsibilities were assigned to specified closing and settlement professionals, potentially including title companies, settlement agents, and closing attorneys, rather than automatically to the buyer personally. Preserve that distinction when allocating preparation tasks within a family office or advisory team.
Vacatur does not necessarily stop a closing professional from requesting entity, trust, or beneficial-ownership information. Independent compliance and underwriting procedures may still require documentation. Separately applicable sanctions, financial-institution reporting, lender, and title-underwriting obligations do not disappear because this particular rule was vacated.
A buyer evaluating Onda Bay Harbor should therefore ask the closing team to identify the basis for each request. An ownership questionnaire should not, by itself, be treated as evidence that federal Real Estate Report filing has resumed.
A useful written checklist separates three categories: information needed under independently applicable requirements, information requested for underwriting, and anything associated with a potential change in the rule’s litigation posture. Ask which items are necessary to close and when they must be delivered. This allows privacy concerns and transaction readiness to be addressed together, without mistaking relief from one filing obligation for relief from all diligence.
The central question for a yacht owner is contractual: if the residence purchase does not close on time, what remains payable elsewhere? Ask counsel whether marina deposits, membership fees, dockage charges, or yacht-service commitments survive a delay or termination of the home purchase.
When considering St. Regis® Residences Bahia Mar Fort Lauderdale, apply that review to any marine arrangements contemplated alongside the residence. Do not assume separate agreements are legally linked merely because they support the same lifestyle plan.
For each agreement, identify the counterparty, contracting entity, payment dates, commencement conditions, termination rights, and any extension provisions. Counsel should examine whether a delayed residential closing changes those obligations and whether coordination can be negotiated before commitments become binding.
The classification of a particular marina slip, dock lease, membership, or easement requires separate analysis. Neither blanket coverage nor blanket exemption under the residential rule should be assumed. The physical relationship between a home and a berth does not settle the legal character of the rights being acquired.
For a Coconut Grove search that includes Vita at Grove Isle, begin coordination before residence and marine documents move toward execution. Prepare an ownership chart identifying which entities would hold the residence, yacht, and marina rights, and which would enter insurance and operating contracts.
The objective is clarity, not an assumption that every asset belongs in the same entity. Have advisers compare the chart with the proposed contracts so the purchaser, vessel owner, marina customer, and insured parties are deliberately identified rather than inadvertently conflated.
Alongside that chart, create a payment calendar covering residence deposits, closing funds, marina payments, membership commitments, and vessel-management start dates. Mark which payments depend expressly on residential completion and which do not. Where a dependency matters but is not documented, ask counsel whether it can be negotiated. This turns a collection of lifestyle commitments into a transaction plan with clear decision points.
An appeal creates uncertainty because a change in the court-ordered posture could alter reporting expectations. It does not, by itself, establish when or how those expectations will change. Avoid building the closing calendar around either predicted reinstatement or permanent disappearance of the rule.
Before funds are committed, request a coordinated review: counsel confirms the litigation status, the closing team identifies outstanding information requirements, and the marine-contract adviser checks upcoming payments and termination deadlines. If the residential timetable shifts, revisit those separate commitments immediately rather than assuming they shift with it.
For the yacht owner, a well-managed purchase means understanding which obligations are inactive, which remain independently applicable, and which arise solely from signed contracts. That precision protects the intended rhythm of life ashore and afloat without confusing regulatory relief with contractual flexibility.
Explore South Florida residences with a considered approach to life ashore and afloat at MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe Residential Real Estate Reporting Rule is vacated nationwide, with an appeal pending. That is not the same as permanent repeal.
They need not file while the order remains in force and face no liability for failing to file during that period. Counsel should confirm the status for the relevant closing.
The court held that FinCEN lacked statutory authority under the Bank Secrecy Act to impose the rule. The nationwide vacatur was entered on March 19, 2026.
No; exemptive relief deferred compliance from December 1, 2025, to March 1, 2026. The compliance date should not be confused with the original effective date.
No. It targeted certain non-financed residential-property transfers to legal entities or trusts, with scope depending on the property and transaction structure.
No. Filing responsibilities were assigned to specified closing and settlement professionals, potentially including title companies, settlement agents, and closing attorneys.
Yes, information may still be requested under independent compliance or underwriting procedures. Such a request is distinct from an obligation to file a federal Real Estate Report.
No blanket classification should be assumed. Counsel should analyze the specific slip, lease, membership, or easement and the rights conveyed.
That depends on the contracts, not the residential rule’s filing status. Counsel should check whether deposits, fees, and service commitments remain payable if the residence closing is delayed or terminated.
Prepare an ownership chart and payment calendar covering the residence, yacht, marina rights, insurance, and operating contracts. Have counsel confirm the litigation status and the closing team explain outstanding information requirements.