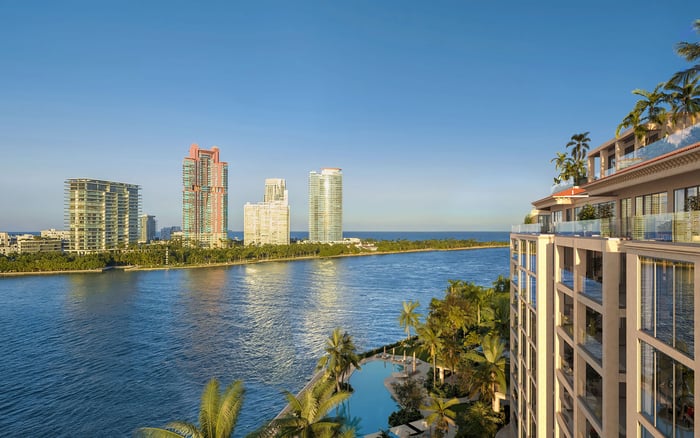
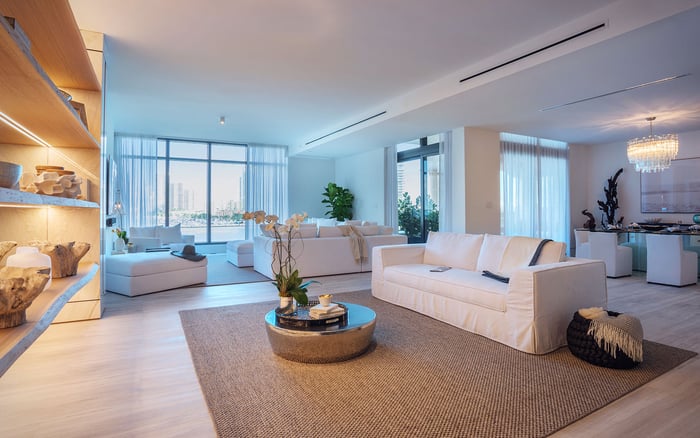
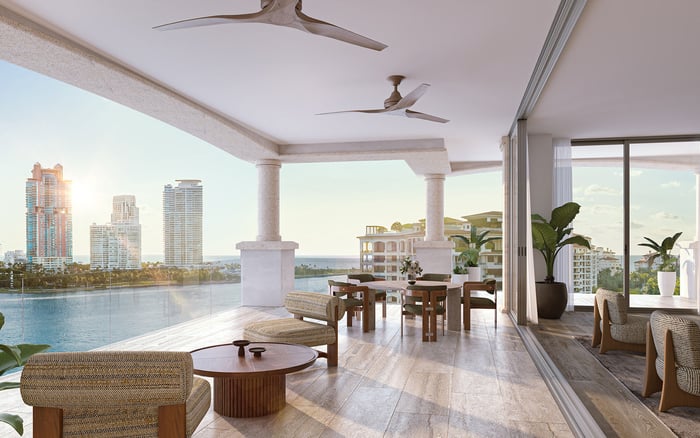
For Fisher Island seasonal owners, lending a residence to family or guests calls for a precise review of occupancy definitions, absence provisions and the home's stated use. Written insurance confirmation and separate community approvals should precede the handover.
For a Fisher Island owner arranging travel by private aviation, lending a residence to family can feel like a simple extension of hospitality. The keys change hands, the furnishings remain, and the owner expects to return. Yet this familiar arrangement warrants an insurance review before the guest arrives-not after a loss.
The central question is whether the proposed stay fits the residence's insured use. Seasonal classification alone does not confirm that every guest arrangement is acceptable. Nor should an owner assume that a relative's presence resolves a vacancy restriction or satisfies an owner-occupancy requirement.
At Palazzo del Sol Fisher Island, as with any residence under consideration, the prudent approach is to examine the individual policy rather than infer coverage from the address. Private-aviation seasonality provides a planning context, not a substitute for the contract's occupancy language. It establishes neither a special insurance rule nor a universal coverage calendar.
A furnished residence used each season can often be insured on a standard homeowners form when its occupancy is correctly classified as seasonal or secondary. Accuracy is essential: a home used intermittently should not be described as the owner's primary residence if that is not its actual use.
Furnishings do not remove the need to disclose extended absences. An insurer still needs a clear account of how the residence is used throughout the year, including periods when nobody is staying there.
For an owner assessing Palazzo della Luna Fisher Island, this review belongs alongside the broader ownership plan. Before purchase or renewal, describe the expected months of owner use and the anticipated gaps between visits. If family stays are part of that plan, disclose them explicitly rather than treating them as incidental.
The goal is a policy description that remains accurate after the owner departs. A beautifully maintained interior and an intention to return are relevant, but neither replaces an accurate occupancy classification.
In general terms, a furnished home with nobody currently staying there, but with an intention to return, is described as unoccupied rather than vacant. Vacancy generally involves the absence of both occupants and the contents needed for normal residential use. The policy's own definitions ultimately govern.
That distinction matters because restrictions are not necessarily the same for the two conditions. Owners should avoid using the terms interchangeably when speaking with an adviser, property manager or household staff.
A 60-day vacancy threshold appears in commonly used forms, but it is not a guaranteed allowance under a particular Fisher Island policy. Duration thresholds vary, and endorsements may affect how a provision applies. Ask the adviser to identify the exact definition, the relevant number of consecutive days and the losses subject to restriction.
Vacancy provisions may affect vandalism, malicious mischief and sometimes glass breakage, rather than automatically terminating all coverage. A broad reassurance that the home is “still insured” is therefore less useful than a precise explanation of what remains covered during the proposed absence.
Before offering the residence, give the insurance adviser a written description of the arrangement. Include who will stay, the expected duration, whether the owner will also be present and whether the guests will have exclusive possession. State whether any compensation is involved, and describe any staff or caretaker occupancy.
These details should be assessed against the actual policy. A family relationship does not, on its own, establish that the stay meets every occupancy condition. A short visit should not be assumed to reset a vacancy clock, nor should an unpaid stay be treated as automatic confirmation of coverage.
For a residence at The Links Estates at Fisher Island, the same disclosure discipline applies without implying anything about that project's particular insurance requirements. The question concerns the owner's proposed use and the policy that insures it.
Request a written response addressing that use. Ideally, it identifies the relevant provisions and any endorsement or change needed before the stay begins. If dates, compensation or possession arrangements change, return to the adviser rather than relying on an earlier answer for a different scenario.
Renting a second home can change the insurance needed. When describing the arrangement, distinguish personal seasonal use and unpaid hospitality from paid rental activity. If compensation is contemplated, disclose it before assuming that existing homeowners coverage remains suitable.
Insurance confirmation does not constitute permission under condominium guest, leasing, access or amenity rules. Those are separate questions requiring separate review. An arrangement may fit the policy's stated use without having received the necessary community approval.
For buyers considering The Residences at Six Fisher Island, guest-use planning should therefore involve both the insurance adviser and the applicable community documents. Do not assume an island-wide occupancy rule or infer a particular building's guest permissions from another residence's practices.
Keep the insurance response and any required community confirmation together. This creates a clearer handover record without suggesting that either document replaces the other.
The interval between owner and guest visits deserves as much attention as the stay itself. Review any policy requirements for inspections, security, maintenance or other protective measures before leaving the home unattended.
Ask whether the planned arrangements meet those requirements and what documentation should be retained. Describe staff visits or caretaker presence accurately rather than treating them as a presumed solution to an occupancy condition. The adviser should assess their relevance under the contract.
A residence emptied of contents or undergoing major renovation may need different insurance treatment from a furnished seasonal home. If the property no longer functions as a normal residence, revisit its classification before relying on the existing arrangement.
Where a lender requires coverage, maintaining it is a separate priority. Lender-placed insurance is purchased to protect the lender's interests when required homeowner coverage is not maintained. It should not be mistaken for confirmation that the owner's intended protection is in place.
The most useful departure checklist is specific: confirm the insured use, identify the applicable absence provisions, describe the guest arrangement, secure a written response and review community permissions separately. Then ensure that the actual stay follows the arrangement assessed.
For seasonal ownership, discretion and precision work together. Hospitality can remain effortless for the guest while the owner handles the contractual details in advance.
Explore Fisher Island residences and thoughtful seasonal-ownership considerations with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationA furnished home with an intention to return is generally described as unoccupied rather than vacant. The policy's specific definitions govern.
No. A 60-day threshold appears in commonly used forms, but the applicable duration and restrictions must be checked in the individual policy.
No automatic reset should be assumed. Ask the insurance adviser to assess the proposed visit against the actual policy provisions.
A furnished home used seasonally can often use a standard homeowners form when correctly classified as seasonal or secondary. Coverage should reflect its actual use.
Describe owner-use months, expected absences, guest-stay duration, exclusive possession, compensation and any staff or caretaker occupancy. Request a written response addressing that arrangement.
No. Owners should obtain written confirmation that the proposed guest occupancy fits the policy's stated use.
Yes. Restrictions can affect vandalism, malicious mischief and sometimes glass breakage rather than automatically ending all coverage.
No. Guest, leasing, access and amenity permissions require separate review under the applicable community rules.
Paid rental activity can change the insurance needed. Disclose compensation and distinguish it from personal seasonal use or unpaid hospitality.
Private-aviation seasonality should be treated as travel-planning context, not as a special insurance allowance. The residence's actual use and policy terms remain the focus.