For a Singapore family establishing a Miami residence, the first year benefits from more than a considered property selection. Tax-residence planning, documented approvals, accepted signing authority and disciplined vendor oversight can make the transition more controlled.
Relocating from Singapore to Miami is both a residential decision and an exercise in delegation. The residence may be the visible achievement; the quieter work is establishing who can approve a commitment, execute a document, release funds and oversee the home when the principals are elsewhere.
A search spanning Brickell, Coconut Grove, Downtown Miami, Miami Beach, Surfside or Sunny Isles Beach benefits from a consistent acquisition mandate. Define the intended use, budget and asset type before comparing individual residences. Appoint a buyer’s agent, real estate attorney and international tax advisor, with a named family-office lead to coordinate decisions.
The objective is not to reproduce every Singapore procedure in Florida. It is to make each consequential decision traceable without requiring the principal to manage every detail.
Address tax residence first, asset location and holding structures second, and physical-time planning third. This sequence allows the family to assess ownership choices against its expected cross-border position rather than treating the purchase as an isolated transaction.
Time spent in Miami can affect U.S. tax status through substantial-presence considerations, even when Singapore banking and investment entities remain in place. Have the family’s advisors evaluate its circumstances and establish a process for tracking travel days. A home purchase is no substitute for an individualized residency analysis.
U.S. citizenship or residency is not generally a prerequisite for a foreign national to purchase Florida real estate. That broad principle does not establish eligibility in every case, nor does ownership settle immigration or tax-residence questions. Counsel should confirm the proposed buyer’s position before the family commits to an ownership structure.
For a family considering 2200 Brickell, the first internal document should be a decision brief, not simply a property presentation. It should identify the proposed buyer, approved budget, funding approach, intended use and matters requiring further approval.
A recommended approval matrix should distinguish permission to negotiate from authority to approve the purchase, sign documents and release funds. Those permissions need not belong to the same person. Set delegated limits for routine decisions and identify which changes must return to the principal or designated committee.
Treat a price revision, financing change or proposed departure from the approved mandate as an explicit decision, not an informal extension of an earlier approval. Preserve the final approval alongside the version of the transaction it authorizes.
These are recommended operating controls, not universal legal requirements. Their value is practical: the Miami team can proceed without guessing what a message from Singapore permits.
For planning purposes, a standard cash residential purchase may close in approximately 21-30 days. A financed foreign-national purchase may take approximately 30-60 days because of underwriting, appraisal and document verification. Association approval can add two to six weeks or more, depending on the association and application.
These are estimates, not promises, and the periods need not always be added together. Ask the transaction team to map overlapping workstreams and identify the actual constraints. Do not apply these ranges automatically to every contract or development purchase.
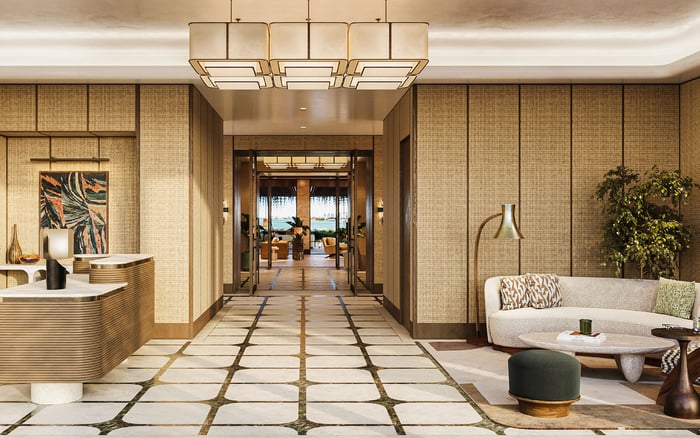
If Park Grove Coconut Grove enters the shortlist, request details of the relevant association process early, before the family finalizes its travel plans. Record the person responsible for the application, outstanding documents and expected decision point in the same calendar as funding and signing milestones.
A cash offer removes the financing workstream, but not the need for ready liquidity, documented approvals or complete diligence.
Foreign buyers frequently close remotely through arrangements such as a power of attorney or remote notarization. Availability does not make every arrangement suitable for every transaction.
If a principal will remain in Singapore, have counsel and the closing team confirm the intended signer, scope of authority and execution method early. A power of attorney may involve notarization and potentially apostille or consular-certification requirements. The exact formalities require transaction-specific confirmation.
Keep internal approval separate from accepted closing authority. An employee authorized to coordinate the purchase for the family office should not be assumed to have authority to execute the closing documents.
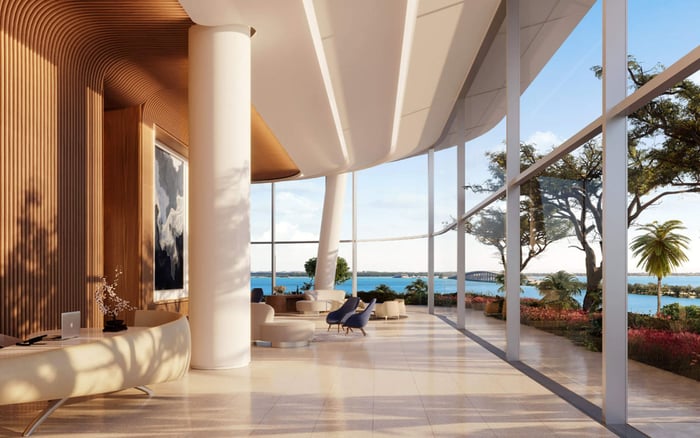
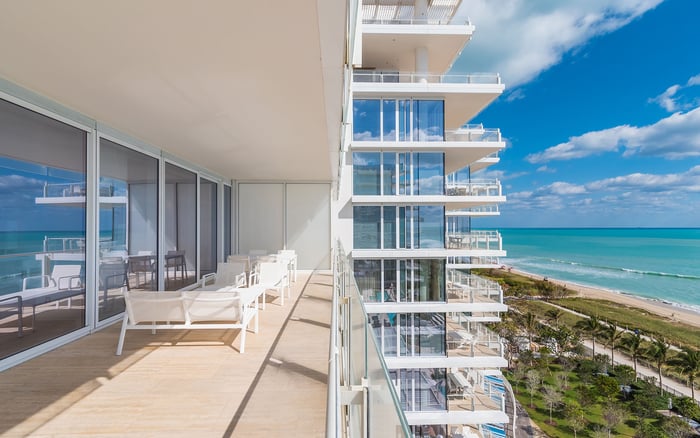
The same distinction matters when reviewing The Perigon Miami Beach: property selection and signature readiness are separate tasks. Retain the accepted authority documents and the transaction team’s confirmation in the closing file.
Establish one controlled acquisition archive rather than leaving records scattered across inboxes and messaging threads. A recommended structure separates approvals, ownership and authority documents, funding evidence, diligence, executed closing documents and ongoing operations.
Source-of-funds evidence can include asset-sale records, distributions and transfers supporting the purchase funds. Preserve the relevant records together so the funding history is clear without having to reconstruct it later.
For condominium diligence, request the current inspection summary, reserve study, budget and known special-assessment history early. Whether considering Aston Martin Residences Downtown Miami or another residence, have advisors assess the applicable records rather than relying on the presentation alone.
Title diligence remains a separate control. Title searches help identify liens, encumbrances and ownership problems; title insurance addresses covered claims, including certain undiscovered issues. Neither replaces building or financial diligence.
Adopt written rules for document integrity, access, retention and destruction, including electronic backups, archiving and reliability checks. Have counsel determine appropriate retention periods for the records and entities involved. No single family-office retention period is established here.
Once ownership begins, classify vendors by operational importance rather than treating every supplier alike. Distinguish strategic partners from commodity providers and assign an internal relationship owner to each material engagement.
Maintain a centralized contract register recording service scope, cost, renewal dates and the person authorized to approve changes. Set renewal alerts at least 120 days in advance and establish service-level schedules for tier-one and tier-two suppliers. These are recommended governance practices, not prescribed legal deadlines.
During the first year, record service issues as they occur. At the annual review, the COO or equivalent should assess benchmarked cost, service quality, responsiveness, compliance and relationship health. Conclude with a decision: renew unchanged, renegotiate or undertake a competitive selection process.
By the first anniversary, the residence should have more than a completed closing file. It should have clear authority, an accessible decision history and service relationships that remain accountable when the family is away.
For a considered residential search aligned with your family’s Miami plans, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationEvaluate tax residence first, then asset location and holding structures, followed by physical-time planning. The analysis should reflect the family’s individual circumstances.
U.S. residency or citizenship is not generally a prerequisite for ownership. Counsel should still confirm the proposed buyer’s eligibility and circumstances.
Yes, substantial-presence considerations can matter even when Singapore banking and investment entities remain in place. Advisors should assess the family’s travel pattern and applicable rules.
It should separate authority to negotiate, approve the purchase, sign documents and release funds. Delegated limits and escalation points are recommended operating controls.
Planning estimates are approximately 21–30 days for a standard cash purchase and 30–60 days for a financed purchase. Association approval can add two to six weeks or more, with some workstreams overlapping.
Remote closings are common through arrangements such as a power of attorney or remote notarization. Counsel and the closing team should confirm the accepted method and any certification requirements in advance.
Relevant records can include asset sales, distributions and transfers supporting the purchase money. Keep them together with the transaction’s approvals and closing documents.
Request the current inspection summary, reserve study, budget and known special-assessment history. Title searches and title insurance serve separate purposes and do not replace this diligence.
No universal family-office retention period is established here. Counsel should determine suitable periods, supported by written rules for integrity, access, backups, archiving and destruction.
Use a centralized contract register with renewal alerts at least 120 days ahead. An annual scorecard should assess cost, quality, responsiveness, compliance and relationship health, leading to renewal, renegotiation or competitive selection.