A Denver-to-Surfside move calls for more than a new address. Coordinating deed vesting, Florida homestead eligibility, estate documents and insurance before closing can help align the residence with the family’s long-term intentions.
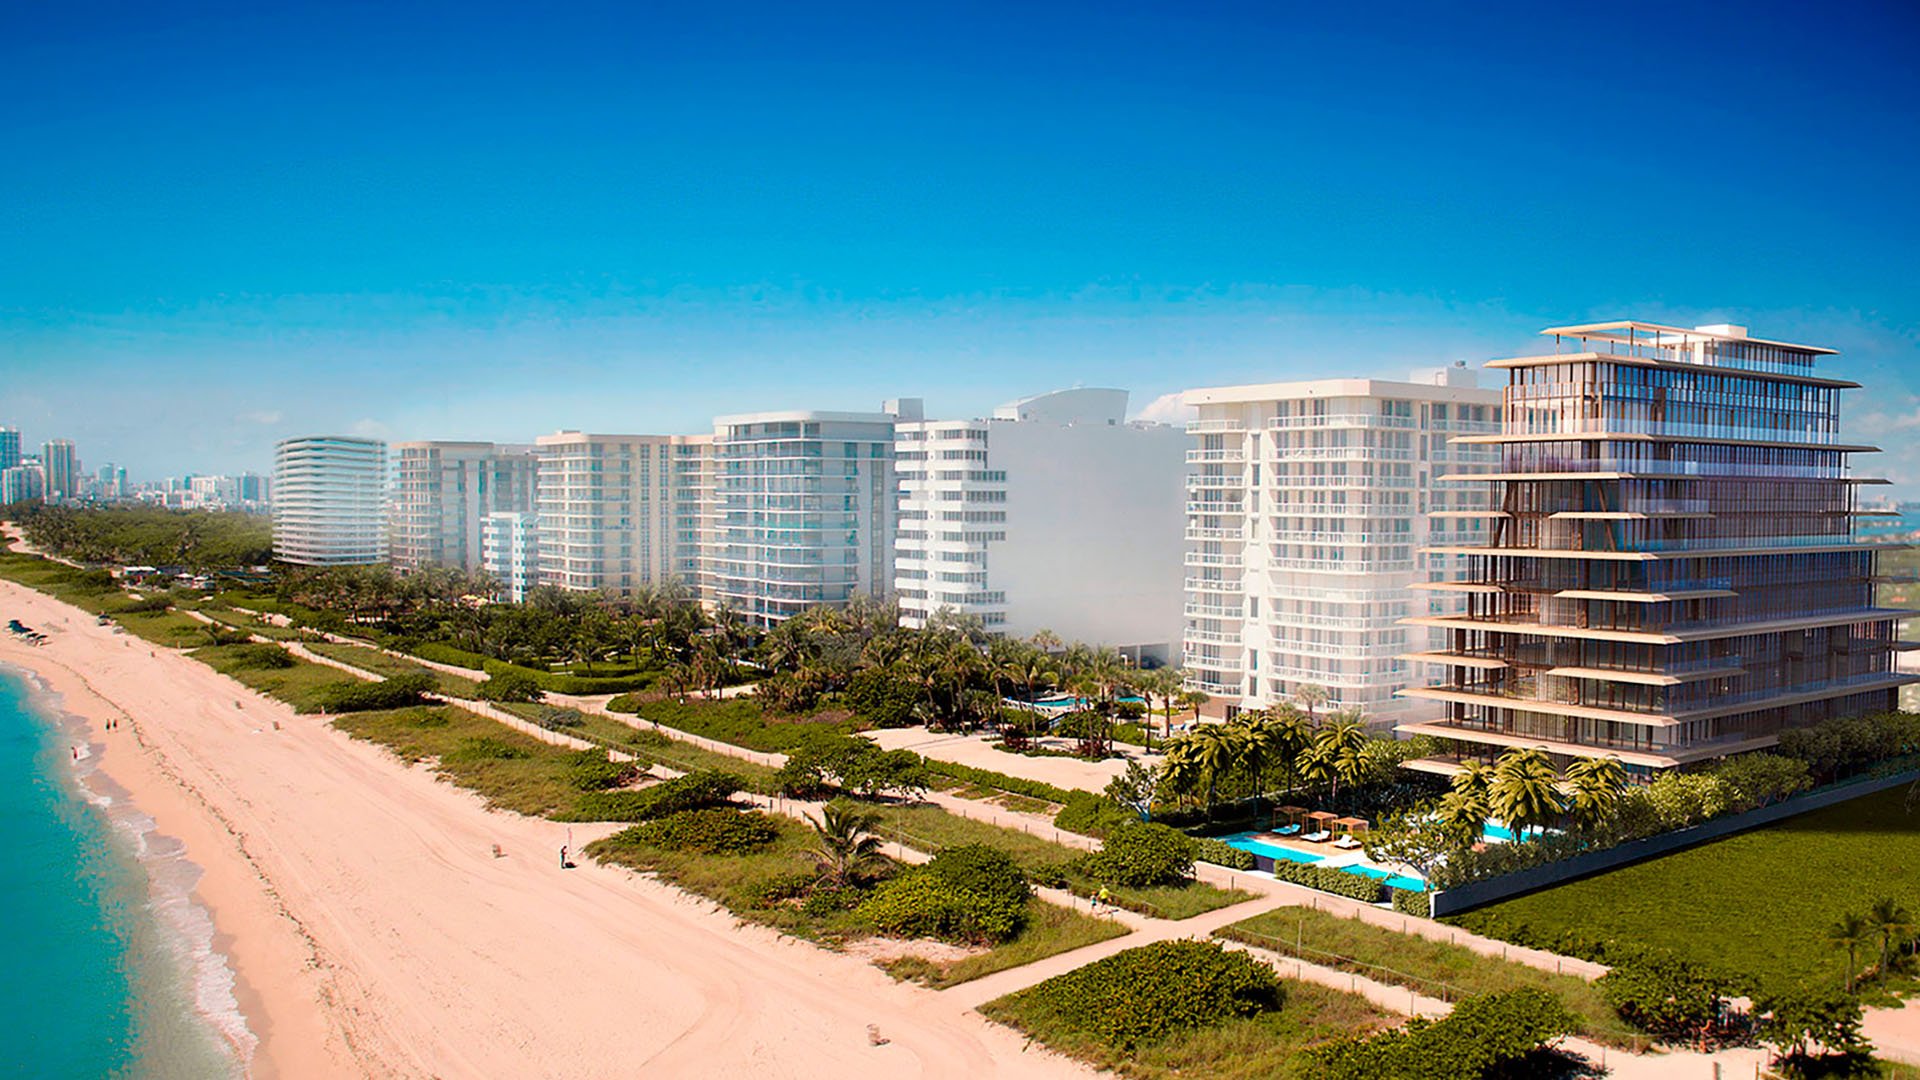
Relocating from Denver to Surfside is an opportunity to reconsider not only where a family lives, but how its home fits into a broader estate plan. Some of the most consequential decisions can receive less attention than the residence itself: whose names appear on the deed, whether a trust should hold title, who can sign and what happens when ownership passes to the next generation.
For a buyer considering Arte Surfside, legal and financial review should proceed alongside the property search. The objective is not a universally superior ownership structure, but one that counsel has tested against the household’s circumstances, intended use and succession wishes before closing.
Treat the first year as a coordinated transition rather than a series of unrelated filings. A deed amendment, homestead application or insurance decision may warrant review by more than one adviser.
Deed vesting identifies how ownership is held. Before approving closing instructions, ask Florida real-estate and estate counsel to review the proposed title together. Provide existing trust documents, relevant family information and a clear statement of whether the residence is intended as a primary or occasional home.
Start with practical questions. Who should own the property? Who should have authority to act if an owner cannot? Does the proposed deed support the intended inheritance arrangement? If a trust is contemplated, ask counsel to reconcile its provisions with the proposed conveyance rather than treating the trust’s name as a complete answer.
Post-closing changes are not merely administrative. Adding or removing an owner, transferring property into a trust or creating a life estate can require a new homestead application. Not every change produces the same tax result, but even a seemingly simple deed revision should receive legal and tax review before execution.
The sale of a Denver residence does not itself generate a Florida Save Our Homes portability benefit. Portability transfers an accumulated assessment benefit between qualifying Florida homesteads, not between a Colorado home and a Florida purchase.
That distinction matters when budgeting for a residence at Fendi Château Residences Surfside. Do not build an ownership budget around a presumed benefit simply because the prior residence appreciated substantially.
The transferable benefit represents the accumulated difference between a qualifying Florida property’s market value and assessed value. The maximum transferable assessment benefit is $500,000-not a $500,000 tax credit, cash payment or automatic reduction in the tax bill.
A relocating buyer who also has a qualifying prior Florida homestead may require a different analysis. Eligibility depends on the prior and new Florida homesteads and the applicable statutory period; transfer is not automatic. General filing guidance calls for submitting portability with the new homestead application by March 1. Confirm the applicable Surfside procedures, eligibility and deadlines locally rather than assuming guidance from another county resolves the filing.
A relocation often involves remote signatures and documents prepared years earlier. Ask counsel to review any existing power of attorney for the proposed Florida transaction before relying on it. Do not assume that a document used successfully in Colorado settles every issue presented by a Florida homestead purchase, mortgage or later conveyance.
Florida homestead conveyance and mortgage rules require attention to spousal joinder. Statutory authority to act through a power of attorney does not simply eliminate that requirement.
Before closing, have the legal team identify the necessary signatories and confirm how any representative will act. This is a coordination exercise, not a reason to assume an existing document is invalid. Possessing a signed document is not the same as confirming that it supports the transaction being planned.
A will or trust should not be treated as granting unrestricted control over the inheritance of Florida homestead property. When a homestead is not validly devised, statutory rules can determine the rights of a surviving spouse and descendants.
When the applicable rule governs and the deceased owner leaves a spouse and descendants, the spouse generally receives a life estate, with the descendants receiving the vested remainder. Instead of that life estate, the surviving spouse may elect an undivided one-half interest as a tenant in common, with the other half vesting in the deceased owner’s descendants. These are conditional statutory outcomes, not universal results for every married homeowner.
For a blended family considering Ocean House Surfside, the planning conversation should be explicit: who is intended to occupy the home, who should ultimately inherit and whether the proposed deed and estate documents support those wishes under Florida law. Address those questions before relying on a document’s general distribution language.
Waterfront ownership warrants an insurance review before financing and closing arrangements are settled. Investigate the property’s flood designation using local flood-zone maps, then ask the lender and insurance adviser to explain the requirements applicable to the purchase.
Flood insurance is required for federally backed mortgages secured by property in a Special Flood Hazard Area. Do not assume that a cash purchase or a different financing arrangement answers the separate question of what protection is appropriate.
For a residence under consideration at The Delmore Surfside, request a property-specific review rather than carrying over assumptions from Denver. Ask for written explanations of proposed coverage, deductibles, exclusions and any association-related insurance arrangements. These are matters for review-not conclusions that a particular policy contains a gap or that a particular building carries a stated cost.
Before closing, bring the proposed deed, trust and succession documents, signing arrangements, flood designation and insurance proposal into one coordinated review. Ask each adviser to identify decisions that depend on another adviser’s work.
After closing, confirm which homestead filings apply and retain the recorded deed with the relevant estate and insurance documents. Revisit that file before any ownership change rather than assuming the original filing remains sufficient.
Before the first storm season, establish a household readiness plan. Review the available hurricane and flood-preparation guidance and hurricane-kit checklist, and keep Surfside’s resident storm hotline, 305-993-1070, accessible. Keep essential documents and contact information within reach of the people expected to act.
The aim is alignment, not a promised tax saving, creditor-protection result or probate outcome. A well-coordinated first year helps ensure that the home selected for daily life also reflects the family’s ownership and succession intentions.
For a discreet conversation about your Surfside search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Florida portability transfers an accumulated assessment benefit between qualifying Florida homesteads; a Denver residence does not generate that benefit.
No. It is the maximum transferable assessment benefit, not a cash payment or a $500,000 credit against taxes.
Potentially, if both the prior and new Florida homesteads qualify within the applicable statutory period. Eligibility and the required application should be confirmed locally.
General filing guidance calls for submitting portability with the new homestead application by March 1. Confirm the procedures and deadlines applicable to the Surfside property.
Yes. A trust transfer, ownership change or creation of a life estate can require a new homestead application, so review the proposed change before signing.
No. Authority to act through a power of attorney does not simply remove Florida homestead spousal joinder requirements for conveyances and mortgages.
No. Florida homestead succession rules can determine a surviving spouse’s and descendants’ rights when the property is not validly devised.
When the rule applies, the spouse generally receives a life estate and descendants receive the vested remainder. The spouse may instead elect an undivided one-half tenancy-in-common interest, with the other half vesting in the deceased owner’s descendants.
Flood insurance is required for federally backed mortgages secured by property in a Special Flood Hazard Area. Investigate the property’s flood designation before settling financing and insurance arrangements.
Review local hurricane and flood-readiness guidance and the hurricane-kit checklist, and establish a household plan. Keep the resident storm hotline, 305-993-1070, accessible.