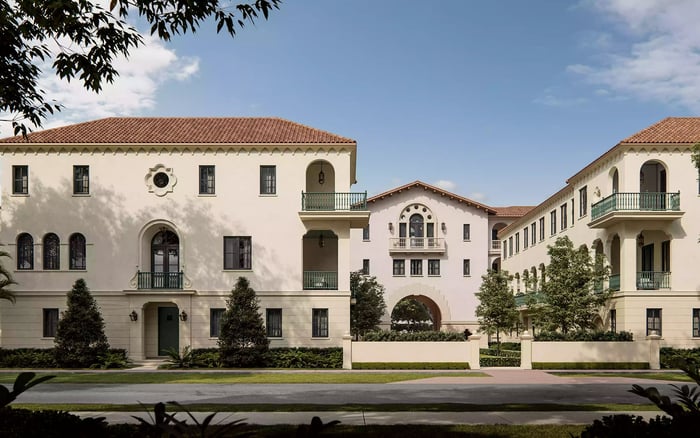
A private-client framework for a Dallas-to-Coral Gables move, separating federal tax status, ownership structure, future resale withholding, and Florida homestead planning.
A move from Dallas to Coral Gables brings decisions about daily life, the choice of residence, and the home’s place within a family’s broader affairs. A less visible decision is how to document the purchase today so a future sale can proceed with fewer uncertainties.
For a household considering Ponce Park Coral Gables, the property search and tax review should advance together. FIRPTA is not a tax classification created by moving between states. Its withholding rules generally concern a foreign person’s disposition of a U.S. real-property interest, making the seller’s status at resale central.
The practical objective is straightforward: establish who will own the residence, how that owner is classified for federal tax purposes, and what documentation a future buyer’s closing team will require.
Living in Dallas before the move does not, by itself, establish whether an owner is a foreign person for FIRPTA purposes. Neither does a Coral Gables address. Federal tax residency and ownership classification require separate analysis.
Foreign persons can include nonresident alien individuals, foreign corporations, foreign partnerships, foreign trusts, and foreign estates. U.S. resident aliens generally are not foreign persons for this purpose. Address the distinction explicitly rather than inferring status from where a family currently lives.
Ask U.S. tax counsel to prepare an ownership-and-status memorandum before acquisition and update it before resale. For jointly owned property, review each owner separately: the amount realized may need to be allocated between foreign and nonforeign sellers.
The buyer generally bears the withholding obligation. The seller’s status is therefore a closing issue for both parties, not simply a private matter between the seller and a tax adviser.
Before choosing direct ownership, a disregarded LLC, partnership, corporation, or trust, commission a comparison tailored to the proposed owners. Include any foreign entity under consideration. The question is not which structure sounds most private, but how each serves the family’s distinct legal and tax objectives.
An LLC does not automatically eliminate FIRPTA. For a disregarded entity, the owner’s status generally controls the foreign-person analysis. Foreign corporations can face special rules and should not be treated as a simple withholding workaround.
When evaluating Cora Merrick Park, settle the proposed title structure during the acquisition review. Do not assume it can be changed later without further advice. Any proposed retitling warrants a fresh review by counsel.
Keep federal tax residency, Florida property-tax homestead, creditor protection, and estate planning as separate workstreams. A structure selected for one objective should not be assumed to satisfy all four.
The standard FIRPTA withholding rate is generally 15% of the amount realized. It is not 15% of the seller’s gain, nor necessarily 15% of the cash the seller receives after closing expenses and debt repayment.
Amount realized includes cash, the fair-market value of other property transferred, and liabilities assumed by the buyer or remaining attached to the property. Counsel and the CPA should calculate that figure separately from taxable gain and expected net proceeds.
The buyer-residence rules require equal precision:
At $300,000 or less, a qualifying buyer-residence transaction can be exempt from withholding, subject to applicable use and procedural requirements.
Above $300,000 and up to $1 million, qualifying buyer-residence transactions generally receive a 10% withholding rate.
Above $1 million, the buyer’s intended residential use does not provide those residence-based withholding reductions.
These are buyer-use rules, not exemptions earned because the seller occupied the home. Withholding is a collection mechanism, not necessarily the final tax liability; the seller can claim it against actual U.S. income tax.
A withholding certificate may reduce or eliminate withholding, including when standard withholding would exceed the seller’s maximum tax liability. Form 8288-B is used for qualifying requests, including certain exemption, nonrecognition, and maximum-tax-liability claims.
A certificate strategy depends on supporting records. Preserve acquisition documents, adjusted-basis records, improvement costs, and selling-expense documentation in a file the CPA can use to prepare the relevant calculation.
Taxpayer-identification numbers are required for certificate requests. A foreign individual who is not eligible for a Social Security number may need an ITIN. Resolve identification requirements early, rather than leaving them to the final closing review.
Submitting an application does not itself eliminate the obligation to withhold. Before listing, ask the advisers to distinguish among the expected tax liability, the default withholding amount, and any proposed certificate relief. Each serves a different purpose in planning available sale proceeds.
For a buyer considering The Village at Coral Gables as a permanent residence, the homestead review should accompany the title discussion, not replace the federal tax analysis.
Florida property-tax homestead eligibility depends on qualifying ownership and permanent-residence conditions. Applications and supporting documentation belong with the property appraiser in the county where the property is located.
Preserve relevant relocation records. The application requests residency evidence such as driver-license, voter-registration, and prior-residence information. Ask counsel to evaluate whether the proposed ownership structure meets the applicable eligibility conditions.
A homestead application is not a substitute for determining FIRPTA status. Likewise, conclusions about property-tax homestead should not be carried over automatically to creditor protection or estate planning.
Before a future sale, bring U.S. tax counsel, the CPA, the real-estate attorney, and the closing team into a coordinated review. The pre-sale memorandum should identify each owner’s status, entity classification, anticipated gain, withholding rate, certificate strategy, taxpayer-identification numbers, and filing responsibilities.
The transferee generally reports withholding on Form 8288, with a separate Form 8288-A for each foreign transferor subject to withholding. Filing and payment are generally due within 20 days after transfer.
A qualifying certificate application submitted by the transfer date can defer remittance until 20 days after the IRS issues a certificate or denial. Confirm the applicable handling with the closing team; an application is not permission to dispense with withholding.
An IRS certificate eliminating withholding generally removes the Form 8288 filing requirement; one merely reducing withholding does not. The seller should retain the IRS-stamped Form 8288-A, which generally supports claiming the withholding credit on the U.S. income-tax return.
The strongest relocation plan leaves a clear record from purchase through resale. This checklist is general information, not individualized legal or tax advice.
For a discreet conversation about your Coral Gables residential search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. The analysis concerns federal tax residency and ownership classification, not simply a move between states.
The buyer generally bears the withholding obligation. That makes documenting the seller’s status important to both sides of the closing.
No. It is generally 15% of the amount realized, which includes cash, other property transferred at fair-market value, and specified liabilities.
No. The residence-based thresholds depend on qualifying buyer use and applicable requirements, not the seller’s occupancy.
No. Above $1 million in amount realized, the buyer’s intended residential use does not qualify the transaction for the residence-based withholding reductions.
Not automatically. For a disregarded entity, the owner’s status generally controls the foreign-person analysis.
Yes, a certificate may reduce or eliminate withholding in qualifying cases. Submitting an application alone does not remove the obligation to withhold.
Keep acquisition, adjusted-basis, improvement, and selling-expense records to support the tax calculation. Confirm taxpayer-identification requirements early as well.
They are generally due within 20 days after transfer. A qualifying certificate application submitted by the transfer date can defer remittance until 20 days after the IRS issues a certificate or denial.
No. Homestead eligibility involves qualifying ownership and permanent-residence conditions, while FIRPTA requires a separate federal tax-status and ownership-classification analysis.