Before reserving a Downtown Miami condominium, align the reserve schedule, insurance renewal and capital-project pipeline. The essential questions concern timing, funding and which obligations could become yours.
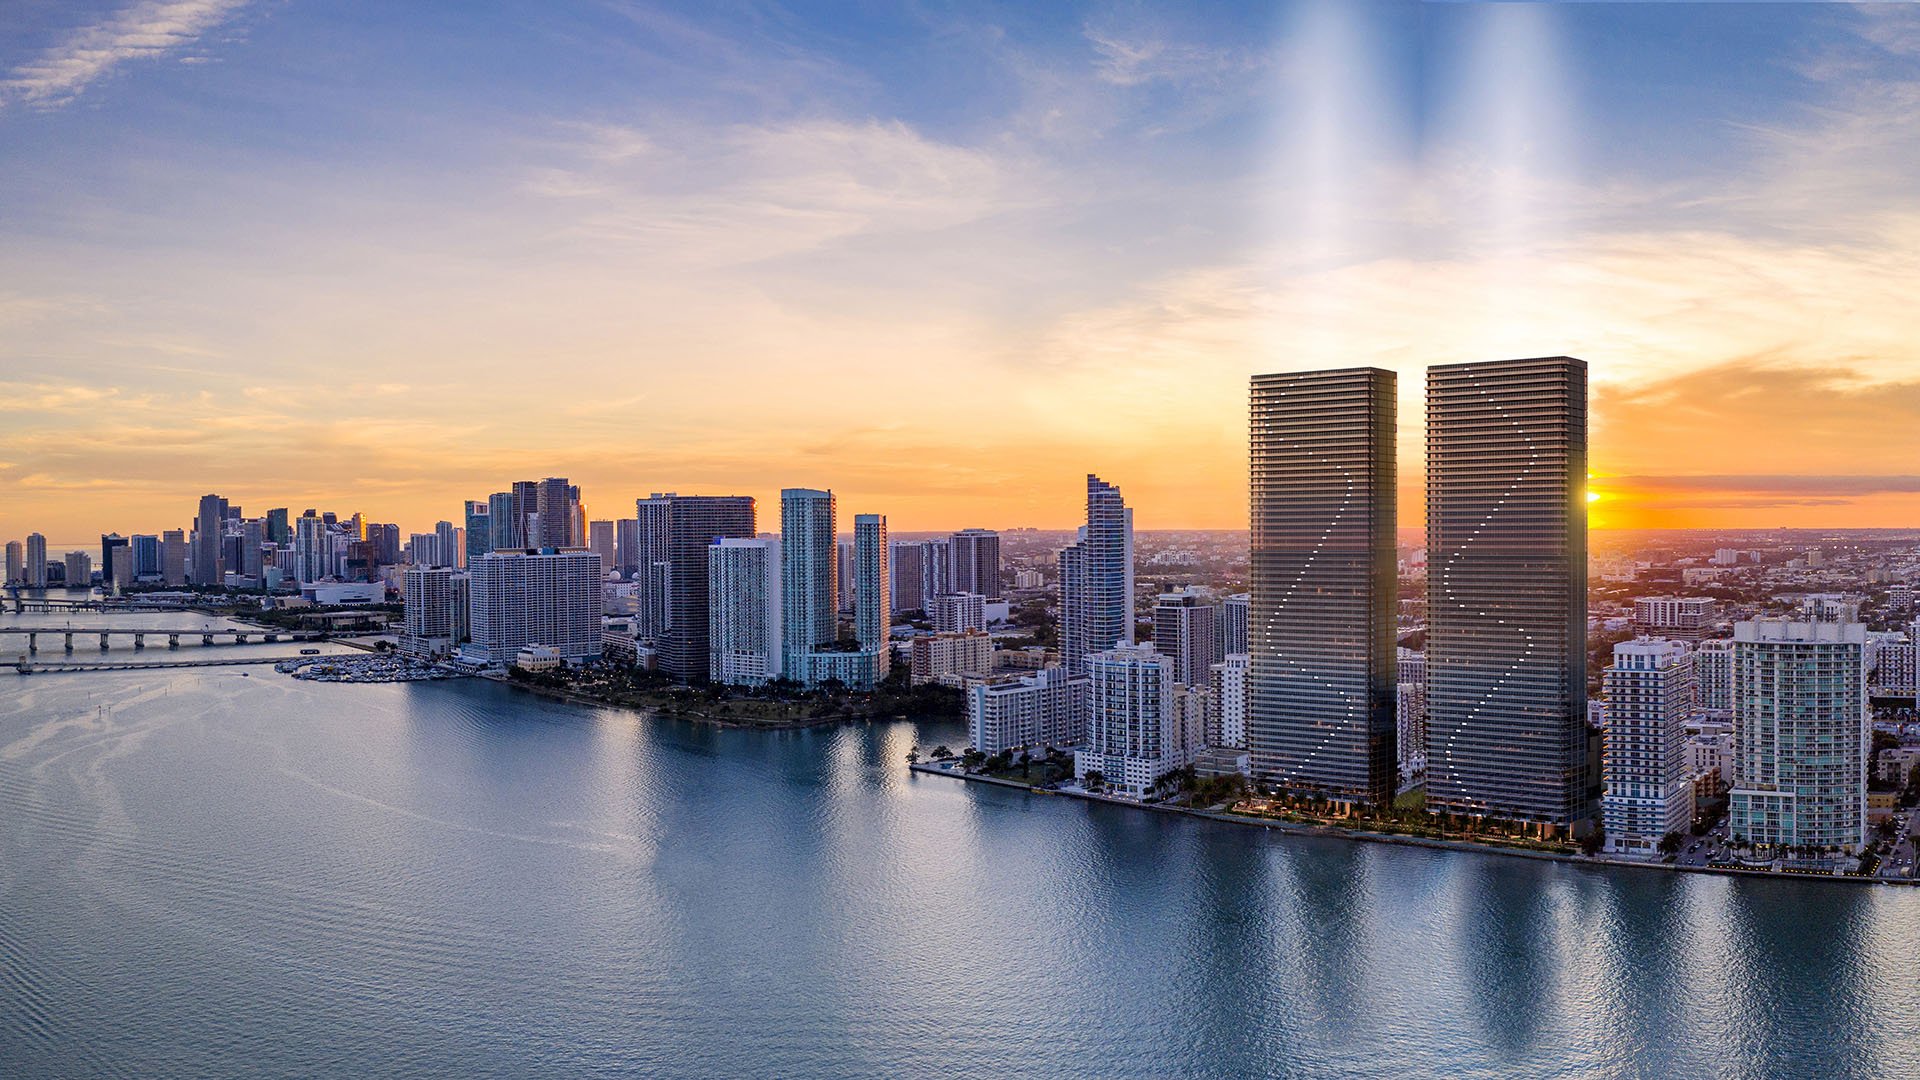
In Downtown Miami, a residence’s appeal may be immediate. Understanding its future carrying costs takes a closer reading. Before reserving, compare three timelines: the association’s reserve contributions, its insurance renewal and its pending capital projects. The central question is whether funding will be available when obligations arrive.
For a buyer considering Aston Martin Residences Downtown Miami, that discipline belongs alongside the evaluation of layout, outlook and service. A project’s identity is not evidence of reserve adequacy, insurance coverage or assessment exposure. Those conclusions require building-specific documents.
Begin by asking what the proposed reservation commits you to, which documents are available and which figures remain estimates. Have a Florida condominium attorney review the agreement before you commit funds. Treat the questions below as a due-diligence framework, not a statement of automatic cancellation or refund rights.
Florida requires a Structural Integrity Reserve Study, or SIRS, at least every 10 years for residential condominium buildings with three or more habitable stories. It combines a visual inspection of specified components with a financial study of future repair and replacement needs.
Existing owner-controlled associations subject to the initial requirement generally faced a December 31, 2025 deadline. Associations required to complete a milestone inspection by December 31, 2026 may complete their SIRS simultaneously, but no later than that date. Ask which timetable applies and request documentation of the association’s status. Do not assume an extension covers the building.
The milestone inspection serves a different purpose: evaluating structural condition. Covered buildings generally require an initial inspection by December 31 of the year they reach 30 years old, followed by inspections every 10 years. Local enforcement agencies may require the first inspection at 25 years based on local circumstances, including proximity to salt water.
Request the certificate-of-occupancy date and confirm the applicable local schedule. A marketing completion year is not the statutory anchor. Obtain the complete milestone report and any Phase II report rather than accepting an assurance that a building “passed.” Phase II is an additional inspection stage generally required when substantial structural deterioration is identified, not a category of repairs.
The question is not simply how much money sits in reserves. Ask what each component is expected to cost, how much useful life remains and when the funding schedule anticipates the expenditure.
SIRS components include roofs, structural systems, fireproofing, plumbing, electrical systems, waterproofing and windows, subject to applicable statutory requirements. Each carries a distinct obligation and schedule. An aggregate reserve balance cannot, by itself, establish whether near-term work is adequately planned.
Use the same document-led approach when evaluating One Thousand Museum Downtown Miami. Ask the association to connect the study’s assumptions to its current budget and proposed contributions. Do not infer financial strength or weakness from the address.
For each material component, ask:
What replacement cost and remaining useful life does the study assume?
What annual contribution does the funding schedule anticipate?
Has a recent bid or inspection changed the expected cost or timing?
If expenditure moves forward, what funding source is proposed?
Completing a SIRS does not necessarily mean every covered component’s full replacement cost must already be held in cash. The funding schedule and required contributions matter alongside the balance.
Ask for current declarations, renewal quotes, deductibles, exclusions and open-claim details. Establish whether the next policy is bound or still being negotiated, and whether the budget reflects the current premium, a quotation or an estimate.
These are buyer due-diligence requests, not a statement that every item must be provided under a particular insurance mandate. Their practical value is to distinguish an established cost from an unresolved assumption.
Have an insurance adviser explain the proposed terms, especially deductibles and exclusions. Ask management how any difference between the budgeted premium and the eventual renewal would be addressed. Separately, seek clarity on any open claims connected to planned work and whether the project’s funding assumes insurance proceeds.
Do not treat an anticipated claim payment as an established funding source. Ask what happens if the amount or timing differs from the association’s expectation. That question connects the insurance discussion directly to the capital calendar.
A reserve study estimates future needs. A pending project raises more immediate questions about scope, procurement and payment. Match each significant projected expenditure against current bids, permits, construction schedules and proposed funding.
Ask management to distinguish approved work from work that is proposed, discussed or deferred. For any potential assessment, request the contemplated per-unit amount, payment schedule and approval status. “No assessment approved” does not answer whether one has been discussed.
If association borrowing is proposed or already supports a project, request the loan terms, maturity and repayment arrangements. Ask how repayments appear in the budget and whether other contributions or assessments are contemplated alongside them.
A useful comparison sheet places the study’s expenditure date beside the contractor’s schedule and the funding date. Where those dates do not align, ask for a written explanation. The objective is to identify unresolved obligations before deciding what price and commitment are appropriate.
For a resale purchase, ask for the existing association’s applicable studies, inspection findings, budget, insurance documents and capital decisions. For a pre-construction reservation, first establish which documents describe existing conditions and which present projected operations or future costs.
If Waldorf Astoria Residences Downtown Miami is on your shortlist, apply that distinction to the particular transaction and documents offered. Do not assume every purchase opportunity has the same operating history or document set. Where figures are projections, ask who prepared them, what they assume and when they will be updated.
In either setting, counsel should address document-review rights, refundability and responsibility for assessments approved before or after closing. Ask counsel to explain how the agreement handles approval dates, installment dates and the closing date. Do not rely on a verbal assurance about who pays.
A disciplined purchase decision should leave you able to explain three things: the expected reserve contributions, the status of the next insurance renewal and how pending capital work would be funded. Keep unresolved items visible in your decision rather than allowing a single monthly carrying-cost figure to obscure them.
The strongest reassurance is a coherent explanation supported by current documents. When a cost, date or responsibility remains unsettled, ask your advisers whether to seek clarification or contractual protection before proceeding.
For a discreet conversation about your Downtown Miami property search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationCompare the reserve funding schedule, the next insurance renewal and pending capital projects. Ask how their payment dates align and which costs remain estimates.
A SIRS combines a visual inspection of specified building components with a financial study of future repair and replacement needs. Florida requires it at least every 10 years for residential condominium buildings with three or more habitable stories.
No. A milestone inspection evaluates structural condition, while a SIRS addresses funding for future major repairs and replacements.
Existing owner-controlled associations subject to the initial requirement generally faced December 31, 2025. Associations required to complete a milestone inspection by December 31, 2026 may complete both simultaneously, no later than that date.
Covered buildings generally require it by December 31 of the year they reach 30 years old. Local enforcement agencies may require it at 25 years based on local circumstances, so confirm the building’s applicable schedule.
Phase II is an additional inspection stage generally required when the initial inspection identifies substantial structural deterioration. It is not a category of repairs.
Not necessarily. Review the component-level estimates, funding schedule and required contributions rather than judging the association solely by its reserve balance.
Request declarations, renewal quotes, deductibles, exclusions and open-claim details. Ask whether the next policy is bound and whether the budget uses a confirmed premium or an estimate.
Ask which assessments are approved, proposed, discussed or deferred, including the contemplated per-unit amounts and payment schedules. For association borrowing, request the loan terms, maturity and repayment arrangements.
Have a Florida condominium attorney review the reservation or purchase agreement. Ask counsel to address document-review rights, refundability and responsibility for assessments approved before or after closing.