A buyer-focused framework for approaching LILLI Miami Edgewater, from family-office signing authority and staged deposits to source-of-funds documentation and independently verified wire instructions.
A waterfront residence may be a personal acquisition, but a family-office purchase warrants institutional discipline. At Lilli Miami Edgewater, the first questions are who can commit the buyer, where the money will originate, and how each transfer will be authenticated.
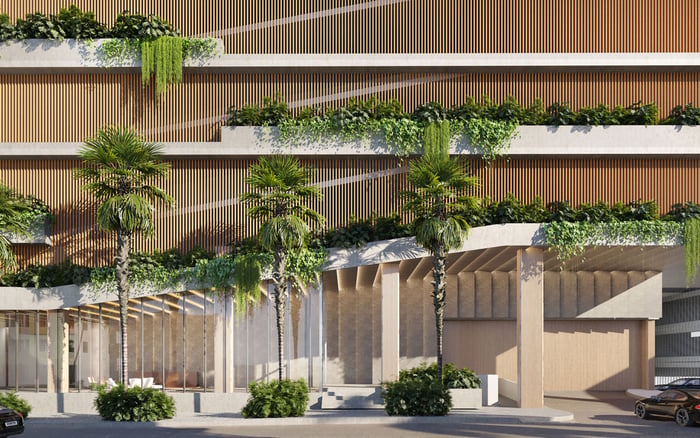
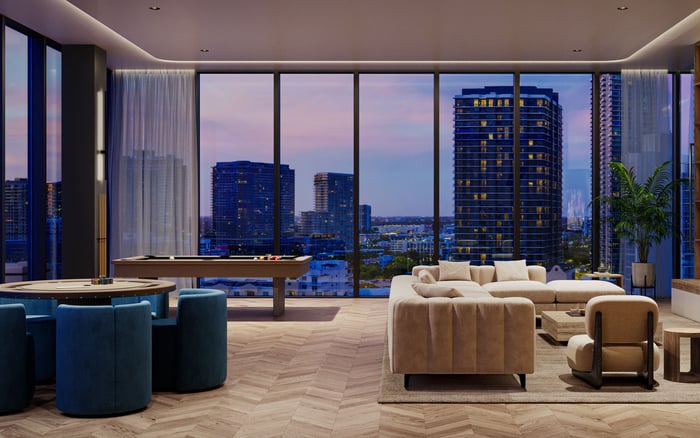
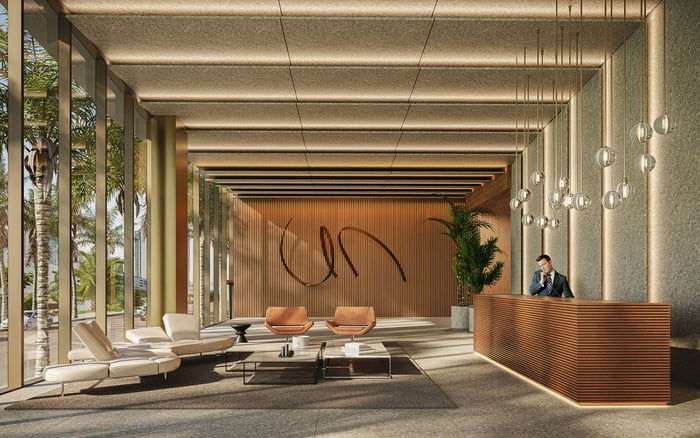
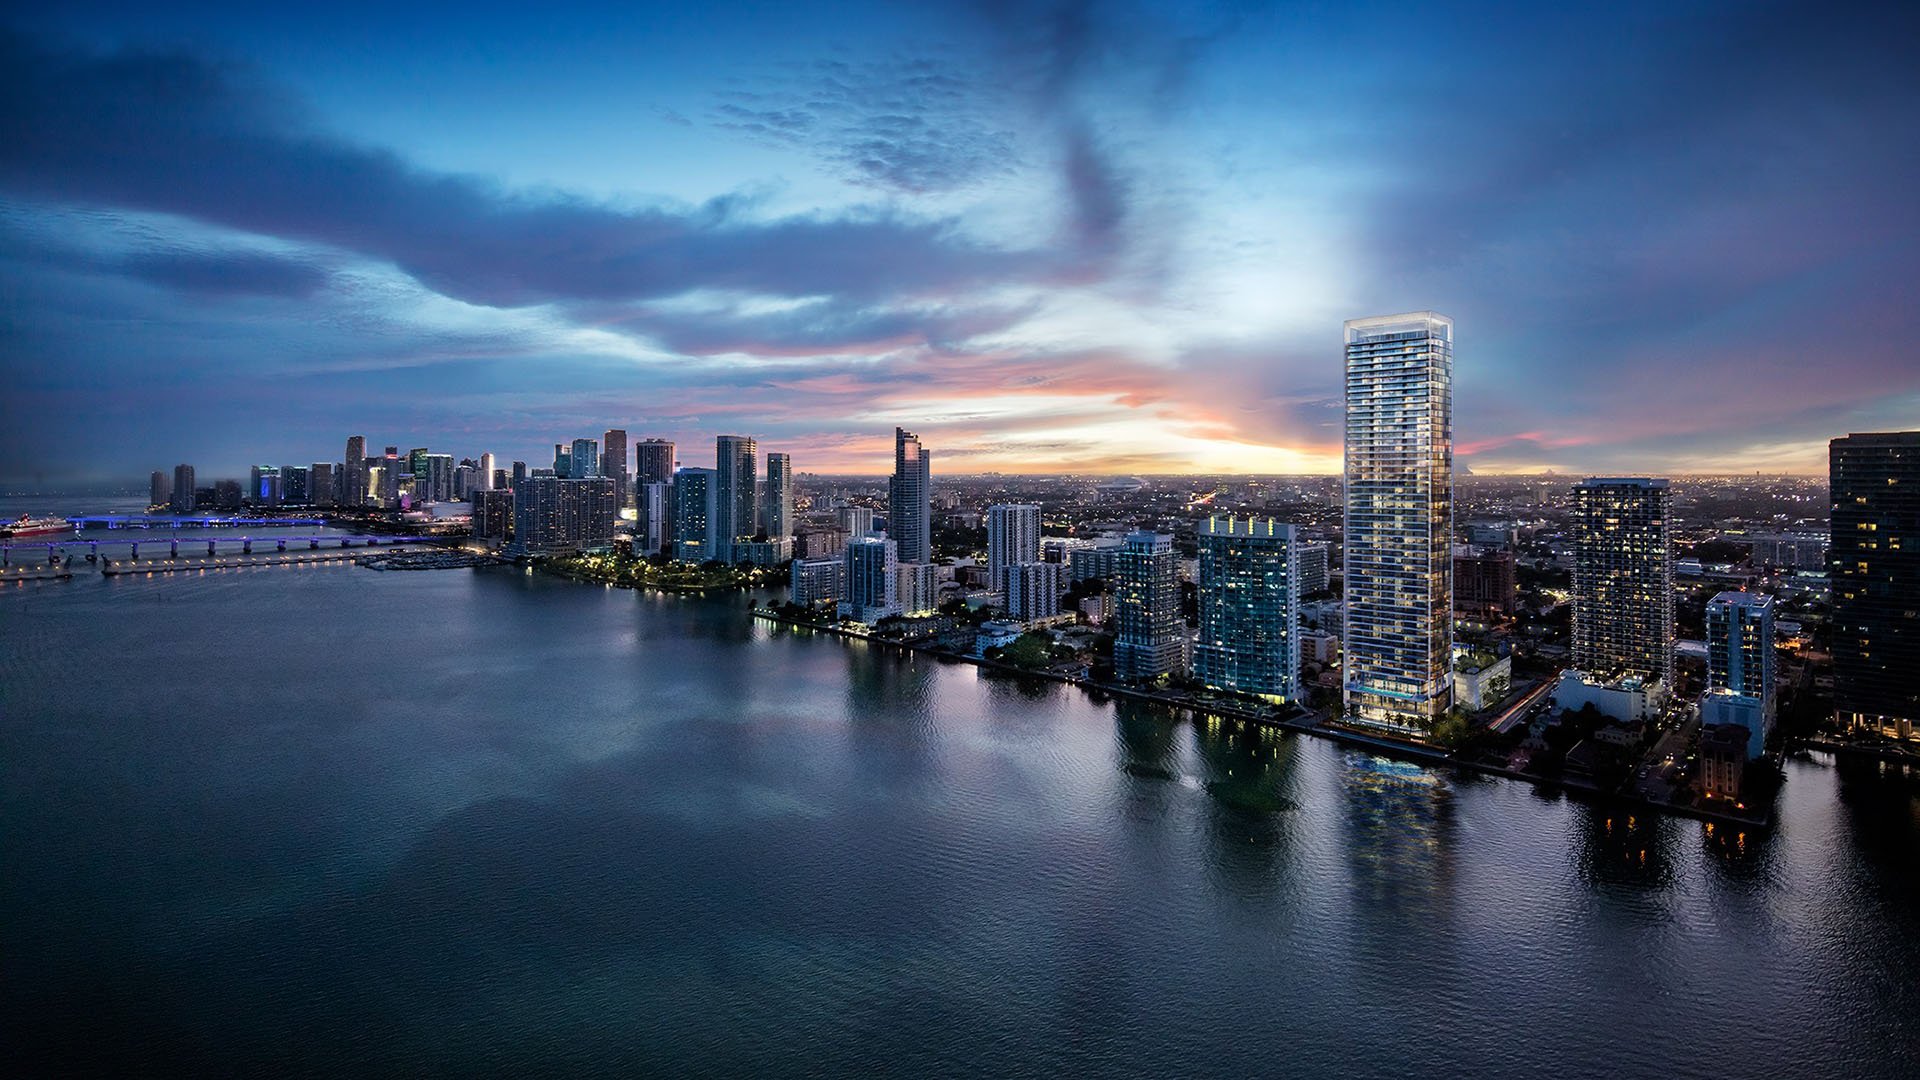
Planned at 717 NE 27th Street directly on Biscayne Bay, LILLI is a proposed 53-story condominium with 117 residences. The developer is OKO Group, with Adrian Smith + Gordon Gill Architecture designing the tower. Its pre-construction status makes contractual timing and capital planning central to the decision.
Treat the controls below as a proposed buyer framework, not confirmed LILLI procedures. Request written answers from the relevant transaction parties before signing or funding.
Start by distinguishing the intended owner from the people directing the acquisition. Will the purchaser be an individual, trust, or special-purpose entity? Who has authority to execute the agreement, approve amendments, and authorize payments? Those roles should be explicit, not inferred from a family-office title.
Ask counsel which governing documents establish authority and whether trustee, manager, or investment-committee consent is needed. Then confirm whether that consent covers the entire purchase obligation or only the first deposit. Approval that leaves later installments unresolved is not a complete funding plan.
Consider documenting a simple approval matrix: purchaser, authorized signer, payment preparer, payment approver, and backup decision-maker. Can the required people act while traveling? Who handles a changed milestone notice? Resolve internal approval delays before they collide with contractual deadlines.
The published deposit schedule outlines four installments: 10% upon signing, another 10% 90 days after signing, 10% at groundbreaking, and 10% nine months after groundbreaking. Together, these represent 40% of the purchase price before closing, with 60% remaining at closing.
Use that sequence for preliminary planning only. The current purchase agreement must establish the actual amounts, triggers, notice requirements, and remedies. Ask how groundbreaking is defined, what documentation confirms it, and when payment becomes due after notice.
For each installment, identify the intended funding account, approval lead time, and available liquidity. Ask the family office to distinguish cash already available from proceeds dependent on an asset sale, distribution, or financing event. A calendar is useful only if the money can reach the approved destination on time.
The closing balance may be eligible for mortgage financing, subject to underwriting. Do not treat that possibility as committed credit or assume financing difficulty excuses performance. Have counsel identify any financing conditions, and ask the lender when it can meaningfully assess the proposed loan.
Request the escrow agent’s written documentation checklist early. Ask which entity records, ownership information, authorized-signer evidence, liquidity documents, and funds-origin records are required for the proposed purchaser. Confirm who reviews them and how acceptance will be communicated.
Keep liquidity evidence and funds-origin evidence distinct. Ask what demonstrates both the ability to pay and the origin of the specific money being transferred. Let the recipient’s checklist determine the appropriate supporting records rather than presuming a universal requirement.
Related-entity funding warrants a separate written question: will escrow accept a wire from a family-office account when an SPV is the contractual buyer? If so, what documents must connect the sender, purchaser, and underlying funding arrangement? Resolve acceptance before initiating the transfer.
Ask how sensitive records should be delivered, who may access them, and whether updates will be needed before subsequent installments. A controlled file should simplify review without unnecessarily circulating private family information.
The names “OKO Group / 720 NE Street PropCo LLC” do not establish the precise contracting party or the scope of any guarantee. Ask counsel to confirm the seller’s exact legal name and whether any other entity guarantees an obligation.
Separately, obtain written confirmation of the escrow agent, beneficiary account name, and intended payment destination. Ask counsel to review the agreement’s deposit-holding and permitted-release provisions, refund conditions, and buyer remedies. Do not equate a recognized development name with a particular escrow protection.
Entity authority, contractual protection, and payment authentication answer different questions. Verifying one does not eliminate the need to verify the others.
Before the first payment, ask the transaction team to agree on a written verification procedure. A prudent proposed protocol includes these controls:
Obtain instructions through an agreed secure channel and restrict their internal distribution.
Call an independently verified number to authenticate the beneficiary and banking details. Do not rely on a number supplied only in the message being checked.
Separate preparation from approval so two authorized people review the payment before release.
Pause any transfer involving changed instructions until those instructions have been independently re-verified.
Repeat authentication for each installment; the first successful wire is not permanent assurance. Ask who will confirm receipt and how the office should escalate a discrepancy. Preserve the verification record with the payment authorization.
An urgent email should not override the agreed controls. Build verification time into the funding calendar so security is not improvised at the deadline.
Advertised entry pricing is approximately $1.65 million, not a unit-specific contract quote. Obtain a current proposal for the selected residence and distinguish the purchase price from other amounts the buyer may owe.
Completion expectations also require care: advertised dates include both 2029 and 2030. Neither should replace the agreement’s delivery provisions. Ask counsel to identify extension rights, outside dates, notice obligations, and available delay remedies.
If the family is also considering Aria Reserve Miami, compare actual transaction documents rather than assuming a shared Edgewater location means shared payment terms or timing protections.
Before final authorization, request the proposed association budget, reserve assumptions, insurance estimates, assignment provisions, and leasing restrictions. These belong in the ownership decision alongside the residence itself. Ask which figures remain estimates and what could change before closing.
For a family also evaluating Villa Miami, use the same diligence questions while keeping each project’s answers separate. The objective is comparable scrutiny, not presumed equivalence.
The strongest purchase file connects authority, liquidity, documentation, and payment security. Before the first wire, the family office should be able to identify who approved the obligation, which account will fund it, and how the destination was independently authenticated.
Explore South Florida residences and Buyer's Guides with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationLILLI is planned at 717 NE 27th Street, Miami, directly on Biscayne Bay. The proposed condominium comprises 117 residences across 53 stories.
OKO Group is identified as the developer, and Adrian Smith + Gordon Gill Architecture is designing the tower. The purchase agreement should establish the exact legal seller and any guarantees.
Advertised entry pricing is approximately $1.65 million. This is not a unit-specific contract quote, so request a current proposal for the selected residence.
A published guide describes 10% at signing, 10% after 90 days, 10% at groundbreaking, and 10% nine months after groundbreaking. That totals 40% before closing, but the current purchase agreement must confirm the obligations.
The guide describes the remaining 60% as payable at closing and potentially mortgage-financeable, subject to underwriting. Buyers should not assume financing is committed or that financing difficulty excuses performance.
Confirm who may sign, whether trustee or investment-committee consent is needed, and who may authorize each payment. Ask whether approval covers the full obligation rather than just the initial deposit.
Request escrow’s written checklist for entity records, ownership information, signer authority, liquidity evidence, and funds-origin documentation. These are diligence questions, not confirmed LILLI-specific requirements.
Ask escrow to confirm acceptance in writing before transferring money. Request the documentation needed to connect the sending account, contractual purchaser, and funding arrangement.
Use a callback to an independently verified number and require separate payment preparation and approval. Pause and independently re-verify any changed instructions before releasing funds.
Advertised completion expectations include both 2029 and 2030. Review the purchase agreement’s delivery provisions, extension rights, outside dates, and delay remedies instead of relying on a marketing date.