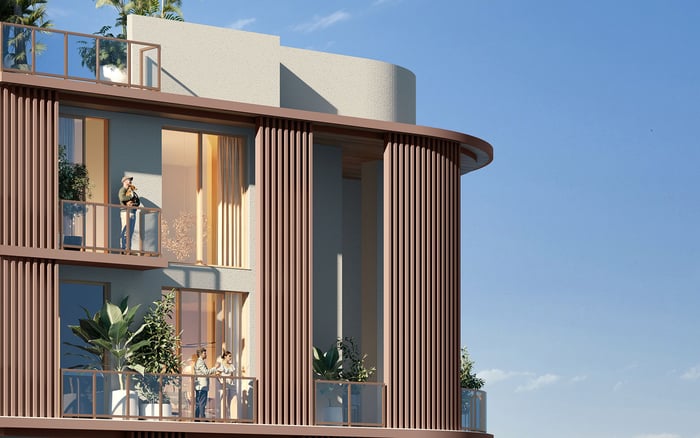
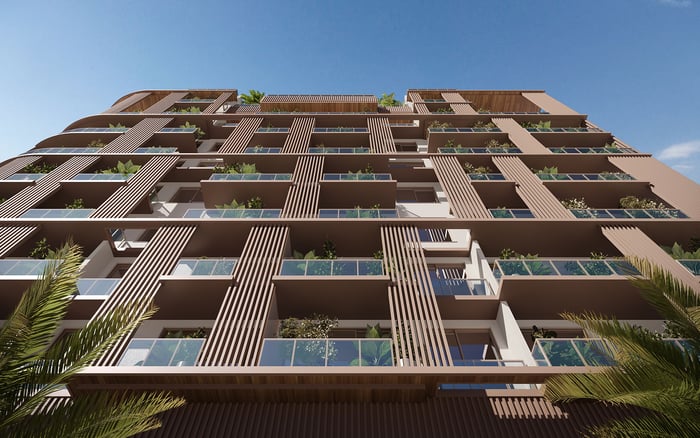
A considered purchase at The Lincoln Coconut Grove calls for separate reviews of flood-claim records, equipment elevations, emergency procedures, and insurance terms. Publicly undisclosed details remain questions to resolve, not evidence of a defect or a claim-free history.
At The Lincoln Coconut Grove, purchase planning should extend beyond the residence itself. Located at 2650 Lincoln Avenue, Miami, Florida 33133, the project is marketed as a boutique condominium with 48 residences across eight floors. Its developers are LORE Development and Element Development, and it is described as under construction.
That status shapes the diligence process. Buyers are evaluating a building in development, not an operating condominium with an established performance record. Flood-claim history, protection of essential equipment, and continuity procedures deserve separate reviews. None can be inferred from the building’s scale or the promise of convenient parking.
The central distinction is simple: an unanswered question is not an adverse finding. Publicly undisclosed records do not establish an unsafe design, an uninsured exposure, or a claim-free history. The objective is to replace assumptions with documents that a buyer’s legal, insurance, and technical advisers can evaluate.
A building-specific flood-claim history for The Lincoln has not been established in the available information. Neither a property-and-casualty loss run nor a construction-risk claims summary is publicly disclosed. Neither point supports a conclusion that the project has never experienced a loss.
Start by requesting available loss runs and a construction-period claims summary. Ask which insured entity, property, policy period, and development phase each record covers. Separate construction claims from condominium operating claims rather than combining them into a single reassurance about the address.
An under-construction project may not yet have the operating record a buyer would examine at an established condominium. Identify which records exist now, which remain pending, and who will provide updates before closing. Request written documentation of the scope of any claims statement.
Pair that review with the parcel flood determination and available elevation documentation. Claims records concern past events; elevation and design documents address a different question about the property. Neither substitutes for the other. A buyer considering Arbor Coconut Grove alongside The Lincoln can apply the same distinction without assuming the two properties share a flood profile.
The Lincoln’s parking features include assigned parking, garage parking, and valet parking. Those features establish parking arrangements-not the locations or flood protection of electrical rooms, pumps, elevator controls, or other essential systems. Garage parking, in particular, does not prove that critical equipment sits at garage level.
The first technical request should be an equipment-location and elevation schedule. Ask for major systems to be identified on drawings, with their elevations related to the applicable flood-design criteria. Such a schedule is not publicly disclosed in the available project information. Equipment protection therefore remains unresolved, rather than demonstrably adequate or inadequate.
Next, request civil-drainage plans and an explanation of flood separation. Have a qualified adviser review how the garage, equipment rooms, drainage routes, and access points relate to one another. The question is not simply whether water could enter a parking area, but which systems could be affected under the conditions being evaluated.
Pump redundancy and emergency-power scope also belong in that review. Ask which components receive backup power, how they are separated from potential water exposure, and what happens if one pump or power source is unavailable. These are requests for project-specific evidence, not statements that The Lincoln has or lacks a particular safeguard.
An equipment plan and a continuity plan answer different questions. The first describes the intended physical arrangement. The second should explain who acts, when action begins, and how residents are kept informed. A completed business-continuity or emergency-response plan is not publicly disclosed for The Lincoln.
Request written procedures for garage closure and vehicle relocation. Clarify who authorizes closure, how notice is delivered, and what instructions apply to assigned spaces and valet arrangements. A parking service does not, by itself, establish an emergency relocation protocol.
Power isolation and elevator shutdown warrant equally specific treatment. Ask who makes those decisions, which personnel or contractors carry them out, and what review is required before service resumes. The same document should address restoration vendors and resident communications, with responsibilities clearly assigned.
For a buyer also evaluating Opus Coconut Grove, the useful comparison is the completeness of each property’s documentation. A consistent set of requests is more informative than an attractive presentation treated as evidence of operating readiness.
The available information does not include master-policy declarations or an insurance-claims summary sufficient to establish The Lincoln’s flood coverage, exclusions, or deductibles. Characterizing the project as financially protected against flooding would therefore be premature.
Obtain the proposed coverage documents and ask an insurance adviser to identify what is covered, what is excluded, and which deductibles apply. Review loss-assessment provisions alongside the buyer’s intended individual coverage. The aim is to understand the proposed allocation of costs-not merely to confirm that a policy exists.
Keep insurance questions distinct from engineering questions. Evidence of protected equipment would not, by itself, establish coverage terms. Likewise, a proposed insurance arrangement would not establish equipment elevations or a reliable restoration procedure. Each part of the purchase file should stand on its own evidence.
For an owner who expects to be away, operational instructions should be usable without an on-site visit. Ask how an absent resident receives closure notices, provides vehicle instructions, and stays informed about access or service restoration. These are practical continuity questions, not assurances that a particular service is already available.
The same document-led approach can inform a comparison with Four Seasons Residences Coconut Grove. Apply the same questions to each property without presuming equivalent equipment protection, insurance terms, or emergency procedures.
Before committing, organize the file into four parts: claims records, flood and equipment documentation, continuity procedures, and insurance terms. Record unresolved items, the party responsible for answering them, and the next review point with counsel. The goal is not to eliminate every uncertainty, but to distinguish documented answers from those that remain prospective.
At The Lincoln, disciplined purchase planning means maintaining a clear distinction between what is known and what still requires confirmation. That clarity allows the residence’s appeal and the practical obligations of ownership to be considered together.
For a considered approach to luxury ownership in Coconut Grove, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe project address is 2650 Lincoln Avenue, Miami, Florida 33133.
The development is marketed as a boutique condominium with 48 residences across eight floors.
The project is described as under construction, rather than an operating condominium with an established performance record.
The developers are LORE Development and Element Development.
A building-specific flood-claim history has not been established in the available information. That does not prove that no claims exist.
Request available loss runs and a construction-risk claims summary, with construction-period claims separated from condominium operating claims. Confirm the property, insured entity, and periods each record covers.
No. The listed parking arrangements do not establish the location or flood protection of electrical rooms, pumps, elevator controls, or other critical equipment.
Request equipment locations and elevations, parcel flood and elevation documentation, civil-drainage plans, flood separation details, pump redundancy, and emergency-power scope.
A completed plan is not publicly disclosed in the available information. Request written procedures covering garage closure, vehicle relocation, power isolation, elevator shutdown, restoration vendors, and resident communications.
The available information does not establish flood coverage, exclusions, or deductibles through master-policy declarations. Obtain proposed coverage documents and review loss-assessment provisions with an insurance adviser.