A disciplined purchase-planning framework for St. Regis Sunny Isles, separating development financing from litigation review, insurance obligations, and individual mortgage eligibility.
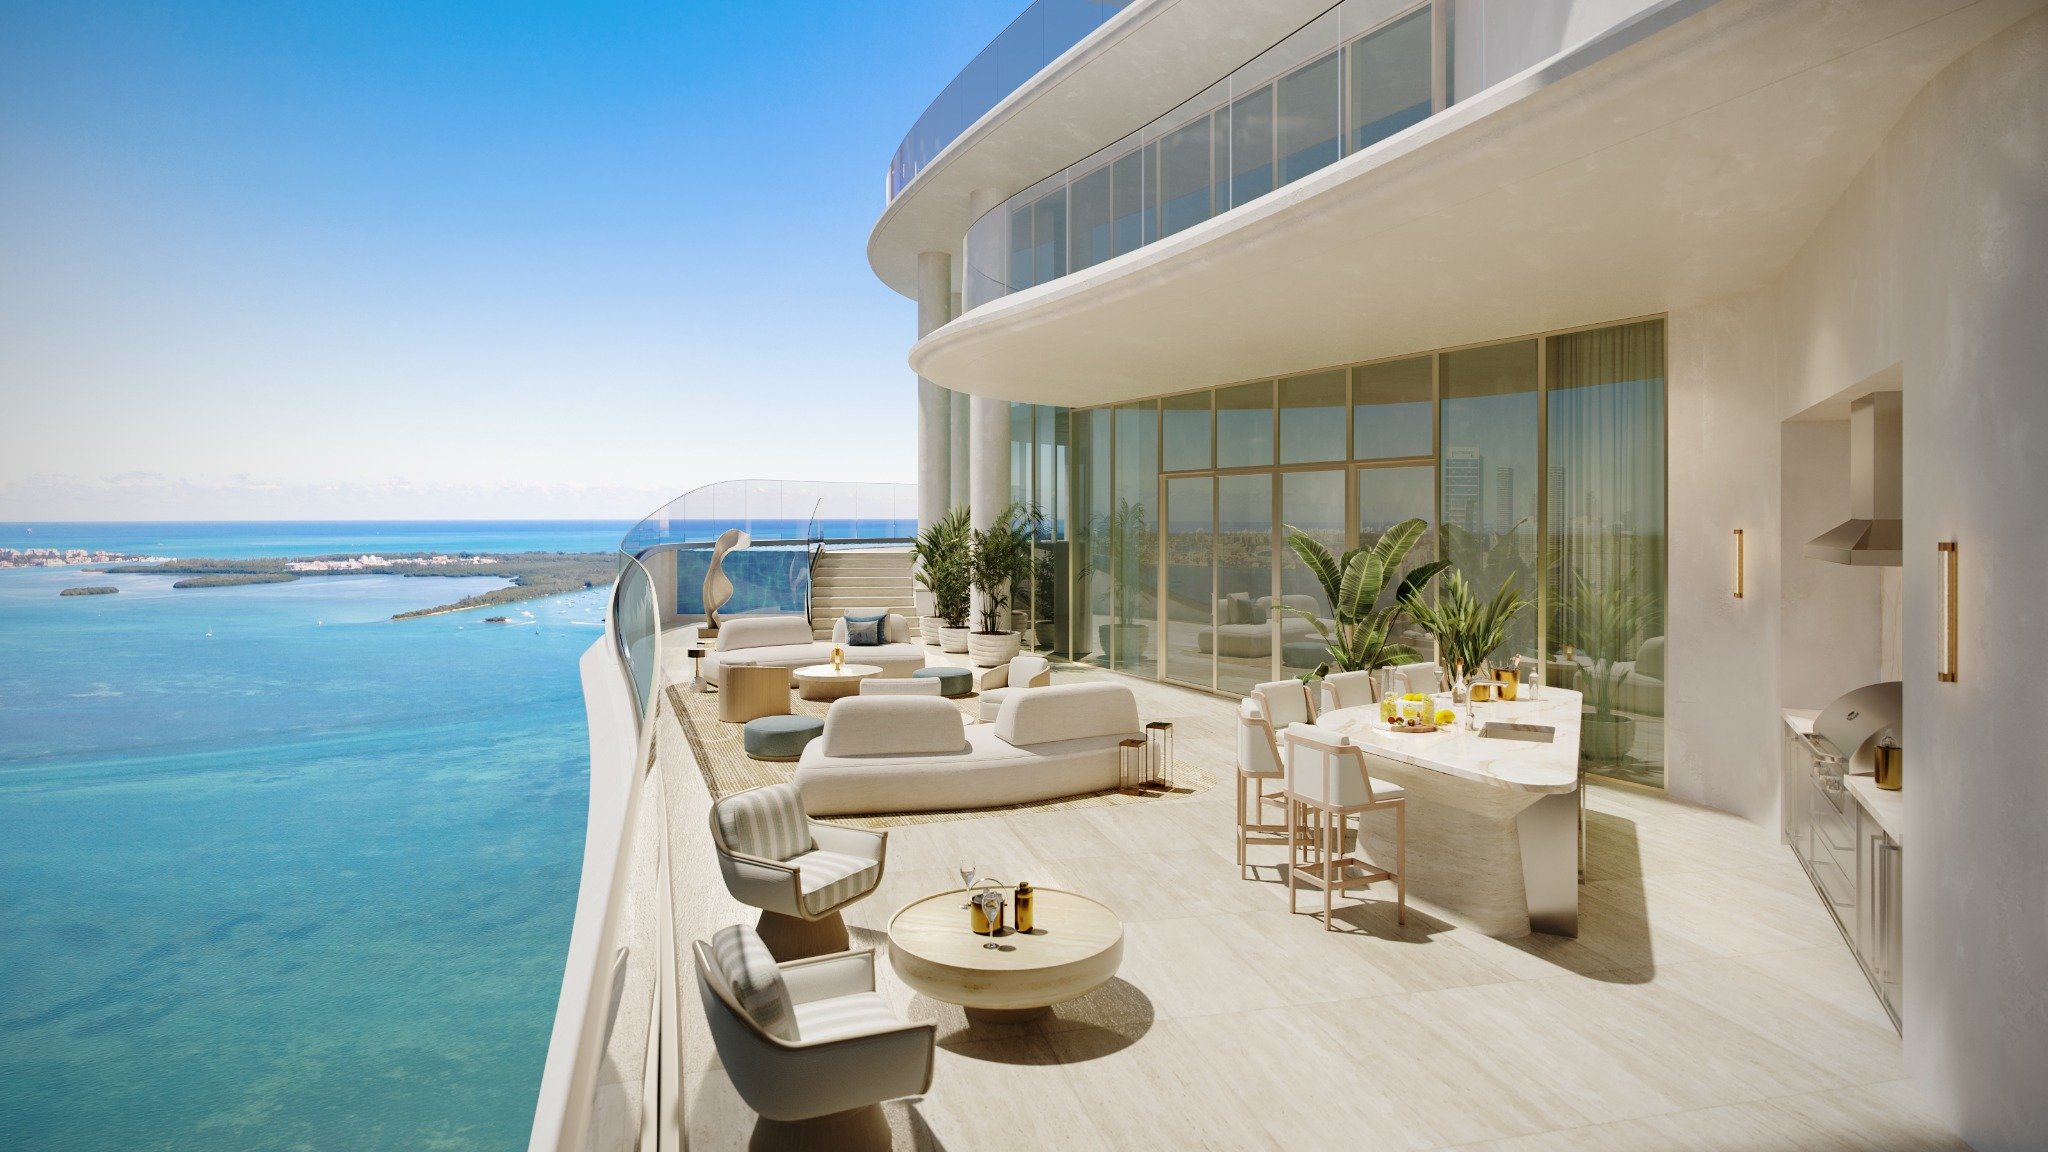
At St. Regis® Residences Sunny Isles, purchase planning should separate three questions: how the development is financed, which obligations may ultimately reach the owner, and what the buyer's own lender will accept. An oceanfront address and a hospitality brand do not replace that analysis.
This is a purchase-planning framework, not an allegation of project-specific litigation, insurance difficulties, or adverse mortgage decisions. Buyers should not infer those conditions from construction borrowing or the need to request disclosures. Nor does lender participation in development financing establish affordable future insurance, adequate association reserves, or protection from special assessments.
For a substantial acquisition, the objective is to turn unresolved questions into written answers before contractual review periods expire. That is a more useful measure of readiness than the prominence of the project or its financing partners.
Fortune International Group and Château Group are developing the oceanfront project at 18801 Collins Avenue, Sunny Isles Beach, Florida. The April 2026 plans called for two 62-story towers and approximately 320 residences: 170 in the South Tower and 150 in the North Tower.
South Tower sales began in 2022, and the tower was nearly sold out in April 2026. At that time, construction completion was projected for 2028. Neither statement should be treated as a current inventory guarantee or a binding delivery commitment.
Site-plan changes were approved in January 2025 to reflect changed market demand, reduced density, and design and program revisions. Buyers should request the current plans and amendments applicable to their residence rather than rely exclusively on early marketing materials. Ask counsel to reconcile the selected unit, tower, shared facilities, and contractual specifications with the latest documents.
Bank OZK's financing began with a $119 million loan in 2020. An additional $100 million in April 2024 brought the balance to $219 million; by December 2025, expanded financing stood at approximately $418.3 million.
In April 2026, City National Bank of Florida provided a $113.75 million facility associated with the North Tower. Its purpose warrants precise wording: descriptions have included both a land loan and construction financing. It is North Tower development financing, not an owners' association funding facility.
The two facilities together represented approximately $532.1 million in project financing. That figure is neither an association reserve balance nor a commitment to finance individual purchases.
The developers were also finalizing a Guaranteed Maximum Price construction contract in 2024; finalizing did not establish execution. Request current confirmation rather than treating a historical negotiation as a completed contractual safeguard.
A useful litigation inquiry goes beyond asking whether a building has any lawsuits. Request current offering documents, amendments, and litigation disclosures, then have counsel identify the parties, subject matter, and any potential connection to delivery or ownership obligations.
Distinguish developer and contractor disputes from association matters. If a proceeding is disclosed, ask counsel to assess whether it concerns construction performance, payment, title, governance, or another issue-and whether the purchase documents address its consequences. These are review categories, not assertions that such disputes exist at this project.
Apply the same discipline when comparing Bentley Residences Sunny Isles. Evaluate how specific and up to date each property's documents are, without assuming that either project has the same legal circumstances.
Insurance review should begin with documents: available coverage forms, limits, deductibles, exclusions, claims history, and renewal quotes. Ask which documents describe construction-stage coverage and which address the intended ownership period. If future terms are not yet available, identify what remains unsettled and when to request updated information.
The central budgeting question is responsibility. Obtain written clarification of who pays premiums before and after turnover, how shared coverage is expected to be allocated, and which insurance expenses the purchaser must address separately. Have an insurance adviser interpret the terms rather than relying on a headline premium alone.
If renewal negotiations are underway, request the available quotes and proposed changes. Do not assume a negotiation exists or that an indicative quote is bound coverage. Compare price alongside deductibles, exclusions, and cost allocations. A seemingly favorable premium does not, by itself, establish the full extent of ownership exposure.
A development lender and a purchaser's mortgage lender make different decisions. The presence of Bank OZK or City National in the project's capital structure does not establish approval for an individual borrower, a particular unit, or the buyer's intended loan product.
Before contractual due-diligence deadlines, ask the mortgage lender to review project eligibility directly. Provide the requested documents and seek written clarification of outstanding conditions, including questions concerning disclosures, insurance, budgets, or construction status. Ask what must be refreshed closer to closing.
For purchasers also considering The Ritz-Carlton Residences® Sunny Isles, the useful comparison is not whether both names carry prestige. It is whether the chosen lender has reviewed the relevant property and identified its requirements. A request for additional documentation is not a rejection, and a preliminary review is not final approval.
Organize the review around the purchase agreement, not an assumed universal timeline. Have counsel identify deposit obligations, review deadlines, amendment provisions, delivery language, and any financing-related protections or limitations in the actual contract.
Assign responsibility for each unresolved item: counsel for legal disclosures, an insurance adviser for coverage interpretation, and the mortgage lender for project eligibility. Maintain a dated record of requests and responses. Before each contractual milestone, distinguish confirmed terms from projections and unanswered questions.
A purchaser considering Jade Signature Sunny Isles Beach alongside St. Regis should apply the same document-first discipline without assuming identical development stages or ownership arrangements. Focus the comparison on what is available for review and what remains contingent, not an unsupported judgment about relative risk.
A well-prepared decision rests on current documents, understood insurance responsibilities, lender feedback appropriate to the intended financing, and a realistic reading of delivery language. Development funding provides relevant context, but it cannot answer all four questions.
Proceed when the unresolved items are understood and acceptable within the contract, not merely because the address is compelling. For discreet guidance on your South Florida residence search, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe oceanfront project is at 18801 Collins Avenue, Sunny Isles Beach, Florida.
Fortune International Group and Château Group are developing The St. Regis Residences, Sunny Isles Beach.
The plans described in April 2026 called for approximately 320 residences across two 62-story towers, with 170 in the South Tower and 150 in the North Tower.
No. The 2028 completion timing was a projection described in April 2026, not a guaranteed delivery date.
No. The litigation discussion is a due-diligence framework, not an assertion of a specific condominium-association lawsuit.
Request current offering documents, amendments, and litigation disclosures. Have counsel distinguish developer and contractor disputes from association matters and assess any implications for the purchase.
Request available coverage documents, deductibles, exclusions, claims history, and renewal quotes. Obtain written clarification of premium responsibility before and after turnover.
No. Development financing does not establish individual mortgage approval; buyers should confirm project eligibility directly with their own lender before contractual review deadlines.
The $113.75 million North Tower facility has been described as both a land loan and construction financing. It is development financing, not owners' association funding.
The approximately $532.1 million in combined project financing does not establish protection from special assessments, future reserve adequacy, or insurance affordability.