A discreet buyer’s framework for separating Surf Club transaction history from the approvals, funding documentation and payment controls a family office should establish for its own acquisition.
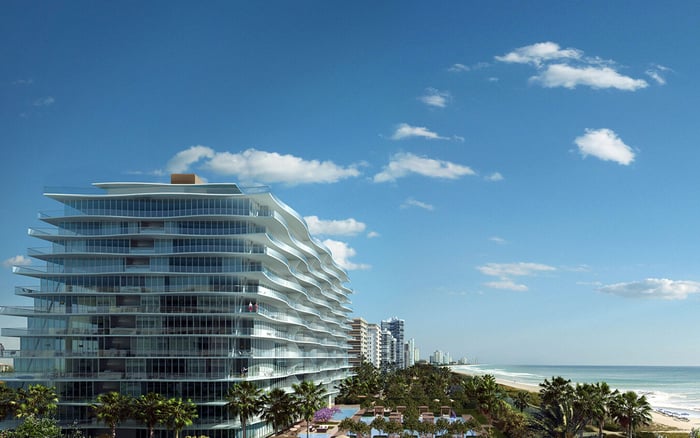
At The Surf Club Four Seasons Surfside, the acquisition decision deserves the same precision as the residence itself. The Four Seasons Hotel and Residences at The Surf Club is at 9001 Collins Avenue, Surfside. For a family office considering a purchase, the address is only the beginning: the approval file should identify the exact unit, seller, purchasing entity and transaction documents.
The original Surf Club residences, Seaway at The Surf Club and Seaway North should be treated as distinct projects. Seaway had recorded $320.7 million in closed sales by July 22, 2025. Separately, Fort Partners secured a $107.6 million construction loan for Seaway North in January 2025. Neither figure establishes the financing position or closing requirements of a particular original Surf Club residence.
The framework below is a recommended buyer-side approach, not a description of the development’s private procedures. Purchase approval, funding readiness and wire authorization should remain separate decisions.
The original Surf Club’s transaction history illustrates the scale of capital involved. A penthouse traded for $29 million in July 2022, with a $20 million JPMorgan Chase mortgage. In July 2024, the 3,992-square-foot Unit N-321 sold for $18.5 million; the buyer’s LLC obtained a $9.25 million Bankwell Bank mortgage.
A $44 million oceanfront penthouse sale followed in November 2024, with PDE 1186 LLC as seller and Ontario-based G5C Capital Corporation as buyer. These transactions establish prices, named counterparties and, where disclosed, financing. They do not establish the purchasers’ internal approvals, private funding records or payment-verification practices.
At Seaway, one buyer acquired four units for $50.9 million in 2024, and purchasers included LLCs and trusts. Entity ownership alone does not identify a family office. Nor does the presence of an institutional lender substitute for the purchaser’s own controls. Nothing in these transaction facts establishes fraud or a failure of controls.
Before signing or funding, consider preparing a transaction-specific approval memorandum. It should distinguish authority to acquire the residence from authority to borrow, pledge assets, sign amendments and release money. Enthusiasm for the investment should not stand in for each subsequent authorization.
A practical memorandum could identify:
The purchasing entity, exact residence and approved acquisition budget.
The authorized contract signatory and the basis for that authority.
The proposed borrowing amount and any separately approved guarantees.
The people permitted to prepare, verify and release payments.
The changes that require renewed approval, including a different purchaser or funding account.
Ask counsel to confirm which entity or trust documents establish signing authority for this purchase. Do not assume that a family member, investment principal or account signatory holds every relevant power.
For a shortlist that also includes Arte Surfside, use the same approval structure but maintain a separate file for each prospective acquisition. Comparative evaluation should not blur transaction-specific authority or carry one residence’s approval into another purchase.
The funding file should explain how the proposed purchaser will supply its contribution and how any financing will reach closing. Begin with a simple schedule identifying each proposed funding source, account holder, amount and expected transfer sequence. Reconcile that schedule with the contract and the latest closing figures.
Depending on the structure, supporting materials might include account statements, documentation of asset-sale proceeds, financing commitments or records explaining a distribution or intercompany transfer. These are suggested file components, not a universal Surf Club or lender checklist. Before transmitting sensitive documents, ask the receiving institution and transaction counsel what they require.
If the funding account belongs to someone other than the purchaser, document the relationship and the proposed legal basis for the contribution. Confirm that the intended payment route is acceptable; do not assume a related entity’s transfer will be treated as interchangeable.
For a cross-border structure, obtain advice specific to the entities, jurisdictions and accounts involved. A Canadian corporate buyer in a historical transaction does not establish automatic FATCA or CRS obligations for another purchaser. Nor does transaction size alone establish a particular enhanced-review requirement.
Do not infer escrow arrangements, callback procedures, secure-portal availability or cyber-insurance coverage from the Surf Club name. Ask the actual closing participants to confirm their arrangements for the specific transaction. Establish the verification process before the first deposit, not merely before the final balance.
A buyer-side protocol should begin with independently verified contact details for the receiving party. Confirm instructions through a trusted channel, using a telephone number established independently of the message carrying the instructions. Do not rely on a reply to the same email or a new number supplied within it.
Consider separating payment preparation from approval. One person can enter the instructions; another can independently check the beneficiary, bank details, amount and authorization against the verified record. Agree with the sending bank on the available approval controls and document who may release the transfer.
Treat any change in beneficiary or payment instructions as a reason to pause and repeat verification. Retain the verification record and transfer confirmation, then confirm receipt through the established channel. If diversion is suspected, contact the sending bank immediately and involve counsel. These measures are proposed safeguards, not guarantees or statements about existing project practice.
A buyer comparing the Surf Club with Fendi Château Residences Surfside can apply the same governance questions without assuming identical documentation, counterparties or payment procedures. The discipline transfers; another building’s answers do not.
Keep lifestyle evaluation distinct from legal and financial review. For the selected residence, ask counsel to identify the applicable ownership, title and condominium documents, along with any consents or conditions that must be satisfied. Assign each unresolved item a responsible person and a deadline rather than relying on a general assurance that the transaction is progressing.
Historical developer financing belongs in a separate context section. It is not evidence that a current seller has clear title, that a buyer’s loan is ready to fund or that a receiving account has been authenticated.
Before releasing the closing balance, bring together the approval memorandum, funding schedule, final figures and verified payment instructions. Reconcile the legal purchaser’s name across the relevant documents and resolve unexplained differences before authorizing payment.
The final review should answer three questions: Is this the acquisition that was approved? Is the money coming from the accepted sources? Has the destination been independently verified? Any unresolved answer warrants an explicit hold or further review, not an assumption based on the property’s prestige.
For a discreet perspective on your Surfside acquisition, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationIt is at 9001 Collins Avenue, Surfside. A purchase file should also identify the exact residence and legal counterparties.
Treat them as distinct projects and maintain transaction-specific documentation. The $320.7 million closed-sales figure concerns Seaway, not Seaway North.
Consider identifying the purchaser, residence, budget, borrowing authority, signatories and payment approvers. Specify which changes require renewed approval.
No. Entity and trust ownership does not, by itself, establish that a purchaser is a family office.
It should connect the proposed purchaser to each funding source and describe the intended transfer path. Confirm the required supporting documents with counsel and the receiving institution.
Do not assume that route will be accepted. Document the relationship and proposed basis for the contribution, and confirm acceptability with the transaction participants.
No. Disclosed financing establishes a financing fact, not the effectiveness of private approvals or payment controls.
No. They are proposed buyer-side safeguards; the actual escrow arrangements and verification procedures should be confirmed for the specific transaction.
Pause and independently reverify the instructions through an established trusted channel. Do not rely solely on the message announcing the change.
The transaction examples do not establish automatic FATCA or CRS obligations or enhanced scrutiny based solely on size. Obtain advice specific to the purchaser’s structure and jurisdictions.