A buyer-side framework for evaluating 2200 Brickell, aligning family-office authority, documenting the funding path, and independently verifying every wire without confusing internal controls with developer requirements.
A residence can be a personal acquisition and still warrant institutional discipline. For a family office considering 2200 Brickell, the essential questions extend beyond architecture: who can approve the purchase, how the money reaches closing, and how payment instructions are authenticated.
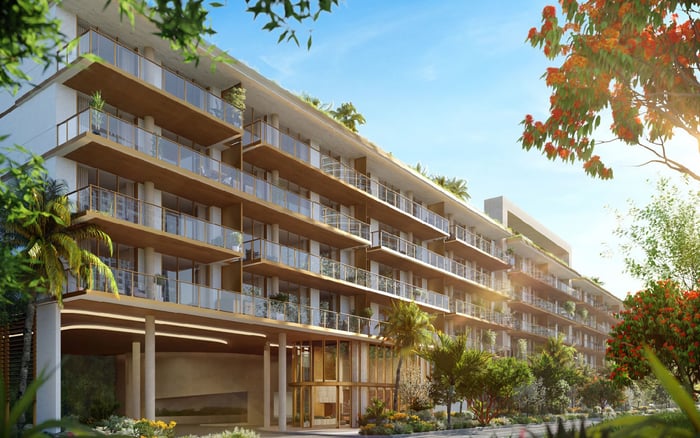
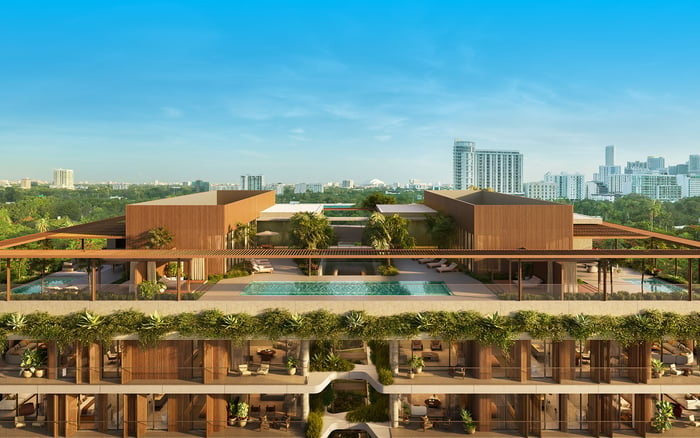
The development is a five-story luxury condominium with 105 residences in Miami’s Brickell neighborhood, by Aria Development Group, Largo Investments, and Place Projects. Revuelta Architecture International is responsible for the architecture, with ODA New York on the design team. Those details establish the project’s identity; they do not clear a transaction to proceed.
Treat the framework below as buyer-side recommendations, not representations of the developer’s procedures or obligations imposed on every purchaser. The objective is a coordinated acquisition file that keeps commercial approval, legal authority, funding documentation, and payment release distinct.
Start with the specific purchase, not the broader development narrative. Ask counsel to reconcile the purchaser’s legal name, residence description, current contract, amendments, deposit obligations, and parties authorized to receive funds. Keep promotional material separate from documents that establish contractual rights.
Construction had commenced by March 25, 2024, approximately six months after the developers secured a $77 million construction loan from Bank OZK. Completion was then scheduled for 2026. Those historical milestones do not establish current construction progress, occupancy authorization, lien clearance, or readiness to convey a particular residence.
Before an approval meeting, request current documentation addressing those matters as applicable to the transaction’s stage. Ask counsel to identify unresolved conditions and the evidence needed to resolve each one. Financing history is background context, not a substitute for unit-level title review or confirmation of the contractual deposit recipient.
For family-office purposes, separate the decision to acquire from the authority to sign and the authority to transfer money. One person may perform more than one role, but the file should state that arrangement explicitly.
A practical internal approval memorandum could identify the purchasing entity or trust, approved commitment, deposit timetable, authorized signatories, and conditions to be satisfied before each payment. Counsel should determine which governing documents, resolutions, consents, or delegations support those actions. These are suggested controls, not a statement of 2200 Brickell’s submission requirements.
If the family is also considering Una Residences Brickell, retain separate transaction files even when the same committee evaluates both opportunities. A shared investment mandate should not blur the identity of the seller, recipient, residence, or approved commitment.
Assign responsibility for each open question. Every unresolved issue should have a decision-maker and a clear condition for release, rather than disappear into an email thread.
A useful funding file explains both where the acquisition money originates and how it will reach the verified recipient. Begin with a plain-language funding narrative, then ask counsel and the relevant financial institutions what supporting evidence they require.
Depending on the arrangement, a recommended internal file might include evidence of available funds, documentation supporting a distribution or asset sale, and records connecting intermediate transfers to the purchaser. These examples are not a prescribed checklist. The appropriate documents depend on the ownership structure, funding route, and requirements confirmed for the acquisition.
Where the account holder and purchaser differ, address the difference before a payment deadline. Ask whether the proposed remitter is acceptable and what authorization or explanation is needed. Do not assume that an economically connected family member, trust, or company can fund the purchase without further review.
Handle identity and financial records through a verified, access-controlled channel. Confirm who needs each document and why, rather than circulating an entire family balance sheet to every transaction participant.
Beneficial ownership and source of funds answer different questions. One identifies the individuals behind an acquisition structure; the other explains the origin and movement of the purchase money. Organize them as related but separate parts of the file.
Ask counsel to determine which beneficial-ownership definitions and information requirements, if any, apply to the purchasing entity or trust. Do not treat an internal ownership file as proof that a regulatory disclosure is required or complete.
Before requesting sensitive information, counsel should confirm current enforceability, effective dates, exemptions, and applicability of any reporting framework to the particular transfer. Ask counsel to identify any responsible reporting party and distinguish regulatory disclosures from separate contractual or institutional requests.
Payment security deserves its own approval process. An approved acquisition and a complete funding file do not authenticate a bank account. Before releasing a deposit or closing balance, verify instructions through an independent telephone call. Email confirmation alone is insufficient.
Obtain the title company’s telephone number independently from its website, not from the payment message. Confirm the intended recipient and account details with an authorized contact. A request to send funds to a company whose name differs from the title company’s warrants further scrutiny, not an improvised explanation.
Treat any change in wiring instructions as a reason to pause and repeat verification. Ask the sending bank whether it can confirm the receiving account’s name and number before transmission; do not assume that it can independently authenticate the recipient. As an additional internal control, consider requiring one person to prepare the payment and another to approve its release after reviewing the verification record.
Immediately after sending, call the title company to confirm receipt. Retain the bank confirmation and receipt acknowledgment together. Sending funds and confirming that the intended party received them are separate steps.
The same buyer-side discipline can guide a comparison with The Residences at 1428 Brickell without implying that either development uses identical contracts, escrow arrangements, or verification procedures. Standardize the family office’s questions, not assumptions about each project’s answers.
Before each release of money, reconcile three items: what has been approved, what the governing documents require at that stage, and where the verified payment is going. Preserve the approval, relevant contract provisions, funding support, verification notes, and receipt confirmation in one controlled transaction record.
For a considered perspective on Brickell acquisitions and South Florida luxury real estate, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversation2200 Brickell is being developed by Aria Development Group, Largo Investments, and Place Projects in Miami’s Brickell neighborhood.
2200 Brickell is a five-story condominium with 105 residences. Revuelta Architecture International is responsible for architecture, with ODA New York on the design team.
No. The 2026 schedule was a historical projection and does not establish current delivery, occupancy authorization, or unit-level title readiness.
No. They are buyer-side recommendations; the actual contractual, documentation, escrow, and payment requirements should be confirmed for the specific acquisition.
A suggested memorandum identifies the purchaser, approved commitment, deposit timetable, authorized signatories, and payment conditions. Counsel should confirm the documents supporting signing authority.
It should explain the origin of the purchase money and its intended payment path. Supporting documents should reflect the actual funding arrangement and confirmed transaction requirements.
No. Beneficial ownership identifies the individuals behind the acquisition structure, while source-of-funds documentation explains the origin and movement of the purchase money.
Counsel should confirm the applicable definitions, current enforceability, effective dates, and exemptions for the specific transfer. Regulatory disclosures should be distinguished from contractual or institutional requests.
Use an independent telephone call rather than email alone, obtaining the title company’s number independently from its website. Ask the sending bank whether it can confirm the receiving account’s name and number without assuming that it can authenticate the recipient.
Pause payment and independently reverify the instructions before release. After sending any wire, call the title company immediately to confirm receipt.