For Key Biscayne buyers, discreet ownership begins with disciplined transaction management. Separate banking from advisory roles, verify payment instructions, document authority, and align service costs with a carefully scoped retention policy.
For a family acquiring a Key Biscayne residence, privacy should mean more than a quiet negotiation. It should mean controlled access to financial information, clearly delegated authority, and a transaction file that remains useful after closing. The objective is not to make ownership invisible, but to give each participant the information needed for an assigned role without unnecessary circulation.
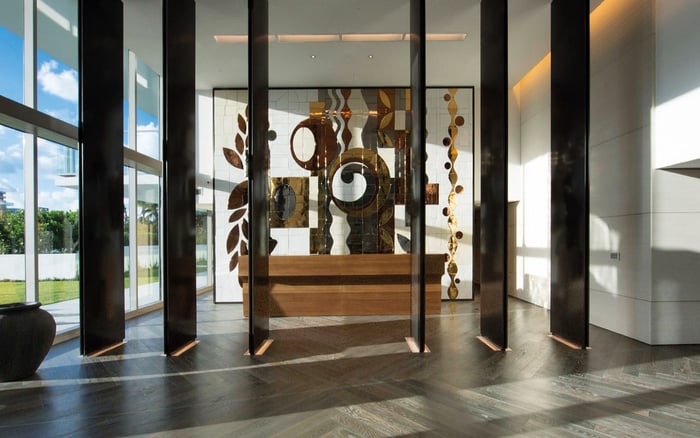
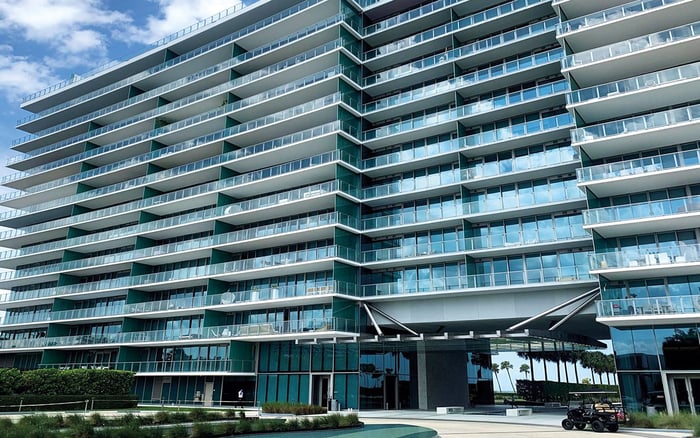
A prospective purchase at Oceana Key Biscayne offers a useful setting for that discipline. Before a deposit moves, the family office should establish who owns the originating account, who may authorize payment, who receives the funds, and who preserves the evidence. These are recommended controls, not representations about the project's procedures.
The best service arrangement makes responsibility explicit before urgency arrives. That principle connects privacy, convenience, and cost more effectively than a provider's address or breadth of offerings alone.
Banking and family-office businesses have a local presence along Crandon Boulevard in Key Biscayne. Geographic convenience can support a family's preferred service experience, but it does not establish which institution may hold deposits, execute transfers, or serve as escrow holder.
Build the engagement around distinct roles: the bank maintaining the account, the adviser coordinating financial decisions, the administrator preparing records, and the party contractually designated to receive the purchase deposit. Do not treat a multi-family office or advisory firm as a deposit-taking bank or escrow holder without specific confirmation.
Administrative support can encompass bookkeeping, bill payment, cash management, fixed-asset management, and payroll. None of those capabilities, on its own, establishes wire authority or a dual-approval service. Ask each proposed provider to identify its deliverables, exclusions, escalation contact, and obligations when a staff member is unavailable. The practical question for the buyer is who remains accountable when a transaction crosses institutional boundaries.
A purchase deposit and the bank account funding it are distinct parts of the transaction. The family office should build a deposit schedule from the executed agreement, with counsel confirming the amount, deadline, designated recipient, and relevant release or return provisions. An informal payment calendar should not replace the contract language.
For each transfer, assemble a concise approval packet: the contractual basis for payment, the purchasing entity, the originating account, the intended beneficiary, the amount, and the verified instructions. If the account ownership and purchasing-entity names differ, obtain appropriate legal and banking guidance before proceeding.
If the family's search also includes Park Grove Coconut Grove, maintain a separate transaction file for the Coconut Grove opportunity. A consistent approval template is useful across properties; reusing recipient details is not. Each transaction should have independently confirmed payment information, even when the same advisers remain involved.
Consider a policy that separates preparation, approval, and release wherever staffing and bank systems permit. One person prepares the payment packet; another checks it against the agreement and verified instructions; an authorized signer releases the transfer. Dual approval is a proposed governance choice, not a universal legal requirement or a confirmed feature of every provider.
Verify initial wire instructions through an independently established contact channel. Any change to the beneficiary, account number, or payment destination should trigger a pause and renewed verification. A message within an existing email conversation should not, by itself, satisfy the office's approval standard.
Document signing authority, transaction limits, substitutes, and the process for resolving conflicting directions. Confirm the originating bank's current requirements for the relevant account and transfer channel, including identity checks, available funds, cutoffs, and processing expectations. Do not assume consumer branch procedures govern business or trust accounts.
After release, preserve the bank confirmation and obtain confirmation of receipt from the intended recipient. Record approval, submission, and receipt as distinct events in the transaction log rather than marking all three simply as paid.
Florida Statutes §662.146 protects the books and records of family trust companies, licensed family trust companies, and foreign licensed family trust companies, subject to specified exceptions. It is not a blanket confidentiality rule for every family office, adviser, administrator, or vendor.
Access remains possible for the Office of Financial Regulation or its authorized representatives, for persons authorized to act for the company, and through specified court or subpoena processes. Separately, §662.147 requires covered family trust companies to maintain complete shareholder or member records and ownership interests at the required office. Confidentiality does not eliminate recordkeeping.
For a purchase file, translate discretion into an access policy. Identify who needs identity documents, who needs payment evidence, and who needs only a status update. Ask providers how permissions are managed and withdrawn. These are due-diligence questions, not assurances that a particular institution or property offers specific security features.
Request written pricing that separates recurring administration from transaction-specific work. Ask about account minimums, wire charges, custody charges, family-office retainers, and any applicable onboarding, exception-handling, or document-export costs. Do not assume every category applies; require the proposal to specify what is included and excluded.
For a parallel evaluation of Una Residences Brickell, use the same service brief for the Brickell transaction rather than assuming the Key Biscayne arrangement transfers unchanged. Identify which additional approvals or administrative tasks the proposed engagement would cover.
Compare response commitments, backup coverage, reconciliation responsibilities, and record delivery alongside price. A broader engagement may be useful, but breadth should not obscure duplicated work or gaps in accountability. Base the decision on the family's actual operating needs, and confirm current contractual terms before funds move.
Retention periods differ by custodian and record type. Florida's Office of Financial Regulation must preserve specified examination, investigation, application, registration, renewal, and closing records for at least ten years. That is not a ten-year rule for every family-office purchase file.
Lawyers and law firms handling client or third-party funds or property must retain required trust-accounting records for six years after the final conclusion of each representation. For trust documents delivered solely through qualifying electronic posting, recipients must be able to access and print or download them until the earlier of four years after deemed receipt or termination of electronic-account access. Neither rule guarantees indefinite client portal availability.
Adopt a counsel-reviewed internal schedule by record category, preserving agreements, authority documents, verified instructions, approvals, confirmations, and reconciliations. A seven-to-ten-year administrative schedule may be considered as a policy choice, not a universal mandate; some records may warrant longer preservation. Export essential files before access ends, assign a custodian, and suspend routine deletion when counsel identifies a preservation obligation.
Explore South Florida residences with a considered ownership strategy at MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Section 662.146 applies to the specified categories of family trust companies, not automatically to every family office, adviser, or vendor.
No. Specified regulatory access, authorized access, and court or subpoena processes remain possible.
No. Advisory or administrative services do not establish deposit-taking or escrow authority; confirm the designated recipient and its role separately.
As a recommended control, include the contractual payment basis, purchasing entity, originating account, beneficiary, amount, and independently verified instructions.
The controls described here do not establish a universal dual-approval mandate. Treat it as a proposed policy and confirm what the relevant bank and engagement support.
Pause payment and verify the change through an independently established contact channel. Preserve the verification and renewed approval in the transaction file.
No. Confirm current deadlines and procedures with the originating bank for the particular account and transfer channel.
Ask about applicable account minimums, wire and custody charges, retainers, and administrative or document-export costs. Require clear descriptions of included and excluded work.
No. The ten-year provision discussed here concerns specified records held by the Office of Financial Regulation, not every family-office transaction file.
For qualifying electronic posting, the access period ends at the earlier of four years after deemed receipt or termination of electronic-account access. Preserve needed documents under a separately reviewed internal retention policy.