A precise preclosing framework for a Florida condominium purchase, covering estoppel accuracy, assessment exposure, separate violation and permit checks, and the written allocation of obligations before closing.
For an executive purchasing a Florida primary residence, closing certainty is part of the property's value. A home selected around professional commitments and family routines should come with a clear understanding of what remains payable, unresolved, or subject to further review. The central preclosing question is not simply whether the seller is current. It is whether the documents support the obligations the buyer is prepared to accept.
An association estoppel is central to that review, but it is not a comprehensive warranty of physical condition or municipal compliance. Treat association finances, association rule enforcement, and government permit records as separate inquiries to reconcile before closing.
This framework focuses on condominiums. Florida condominiums, cooperatives, and homeowners' associations operate under different statutory frameworks. A buyer of an HOA-governed single-family residence should not assume that the condominium requirements below govern that purchase.
Florida condominium associations generally must issue an estoppel certificate within 10 business days after receiving a written or electronic request from an owner, mortgagee, or their designee. Build that interval into the closing calendar rather than treating the certificate as a last-minute administrative item.
A certificate delivered electronically or by hand generally has a 30-day effective period from issuance. Regular-mail delivery generally carries a 35-day period. Ask the closing team to record the issuance date, delivery method, and effective period alongside the anticipated closing date.
For a buyer considering Una Residences Brickell, the discipline is the same as for any condominium purchase in Brickell: align the document calendar with the transaction calendar, not the desired move-in date.
If closing shifts, have counsel determine whether the existing certificate remains suitable for reliance or another certificate is needed. Do not assume that a document ordered early will remain effective indefinitely.
Request the current association account ledger and compare it with the estoppel, seller disclosures, assessment notices, and relevant correspondence. The objective is not to substitute the ledger for the certificate, but to identify discrepancies early enough to resolve them in writing.
The certificate should disclose regular assessments and amounts currently owed, not merely confirm that monthly dues have been paid. Late fees and other outstanding charges warrant separate attention. A zero regular-assessment balance is only one part of the financial review.
Direct the closing team to answer four practical questions:
What is the regular assessment, and does the certificate match the account records?
Which amounts are currently unpaid, including charges outside regular dues?
Which special assessments or other amounts are scheduled to become due during the certificate's effective period?
Do the closing figures distinguish estoppel preparation fees from association transfer fees?
Those fee categories are distinct and should be reviewed separately. Request a written explanation of any mismatch rather than accepting a verbal assurance that it will be handled at settlement.
Separate approved but unpaid assessments from proposals that have not been adopted. Then ask whether either category concerns major repairs or reserve funding. Neither question is answered by confirming that the seller has paid the latest regular installment.
Review notices for amounts, payment schedules, and the status of the underlying decision. Do not treat a proposed assessment as an adopted obligation or assume that an assessment payable later is irrelevant to the purchase. The estoppel's effective period is no substitute for reviewing the broader financial information available to the buyer.
The appeal of Faena House Miami Beach may place it on a Miami Beach shortlist, but the financial inquiry should remain specific to the unit and transaction. A project's identity does not establish the seller's account status or the allocation of an assessment.
Have counsel document which accepted obligations the seller will satisfy and which the buyer will assume. The contract and closing statement should express the same agreement.
The condominium estoppel must address open association rule violations noticed to the current owner. That disclosure is separate from the assessment balance. Paid dues do not establish that the residence is violation-free.
Request the violation correspondence, details of the corrective work, and written confirmation of resolution where the seller says an issue has been cured. Distinguish the seller's statement that work is complete from the association's confirmation that the noticed matter is closed.
Disclosure of noticed violations is not assurance that no undiscovered or unreported violation exists. Keep the physical inspection and document review distinct from the estoppel review.
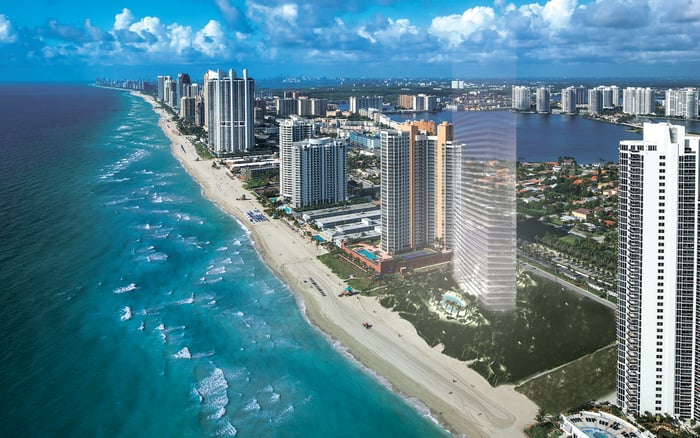
For a residence under consideration at Jade Signature Sunny Isles Beach, or elsewhere in Sunny Isles Beach, apply the same standard of evidence. These project references identify possible search contexts, not findings about any property's accounts, violations, or permits.
Association approval and government compliance are separate inquiries. An association estoppel does not replace a review of building permits or code-enforcement records, and association violation disclosures do not establish municipal compliance.
For Miami-Dade County's open-permit search process, assemble the property address and folio number. Confirm the authority with jurisdiction over the property before requesting records; do not assume one search answers every applicable records question.
The review should cover building-permit history, open permits, and expired permits. Evidence that a permit was issued does not establish whether the permitted work reached its required final status.
Request permit numbers, work descriptions, inspection records, and final status. Check municipal code-enforcement records separately. If an unresolved item appears, ask the relevant authority what remains outstanding and have the appropriate advisers evaluate the path to resolution. Retain the documentary evidence in the closing file rather than relying on the seller's recollection of completed work.
A later ledger entry and the buyer's legal reliance on an estoppel are distinct issues. Do not assume that a newly posted charge automatically defeats statutory estoppel protections. Counsel should distinguish the certificate's effective period, any correction, and the purchaser's legal reliance before determining how to treat a disputed amount.
For unresolved financial, violation, or permit matters, evaluate seller remediation, escrow, credits, delayed closing, and termination under the contract, and negotiate where appropriate. These are not automatic buyer rights. Nor is a credit evidence that a permit or violation has been closed.
Before authorizing closing, request a concise written reconciliation identifying each discrepancy, its supporting documents, the agreed resolution, and the party accepting any remaining obligation. This is the executive standard worth applying: fewer assumptions, clear responsibility, and documents that support the decision. Transaction-specific legal questions belong with Florida counsel.
For a discreet South Florida property search informed by disciplined preclosing questions, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationGenerally, within 10 business days after receiving a written or electronic request from an owner, mortgagee, or their designee.
Electronic or hand delivery generally gives the certificate a 30-day effective period from issuance. Regular-mail delivery generally carries a 35-day period.
No. Association rule violations are a separate disclosure, and a zero balance does not establish municipal compliance or the absence of undiscovered violations.
Compare it with the current account ledger, seller disclosures, assessment notices, and violation correspondence. Resolve discrepancies in writing before closing.
Check amounts scheduled to become due during the certificate's effective period, and separately investigate approved but unpaid assessments and proposals not yet adopted. Document the agreed allocation between seller and buyer.
No. They are distinct fee categories and should be reviewed separately in the closing figures.
No. Building permits and municipal code-enforcement records require separate review; an association estoppel is not a warranty of municipal compliance.
Miami-Dade County's open-permit search process requires the property address and folio number. Request permit numbers, work descriptions, inspection records, and final status from the authority with jurisdiction, including review of open and expired permits.
Do not assume it does. Counsel should evaluate the certificate's effective period, any correction, and the purchaser's legal reliance before determining treatment of a disputed charge.
No automatic right should be assumed. Remediation, escrow, credits, delayed closing, and termination must be evaluated under the contract and negotiated where appropriate.