A discreet, stage-by-stage guide to seller-financed luxury condo purchases, separating payment documentation and negotiated underwriting from conditional reporting obligations, sanctions review, and Florida recording requirements.
A seller-financed luxury condominium purchase involves two negotiations: acquiring the residence and agreeing on the credit that supports the acquisition. The documentation should distinguish those decisions without allowing either to obscure the other. For the buyer, the objective is a closing file that explains who is purchasing, who is paying, and what the seller is financing-while keeping sensitive information within an agreed circle.
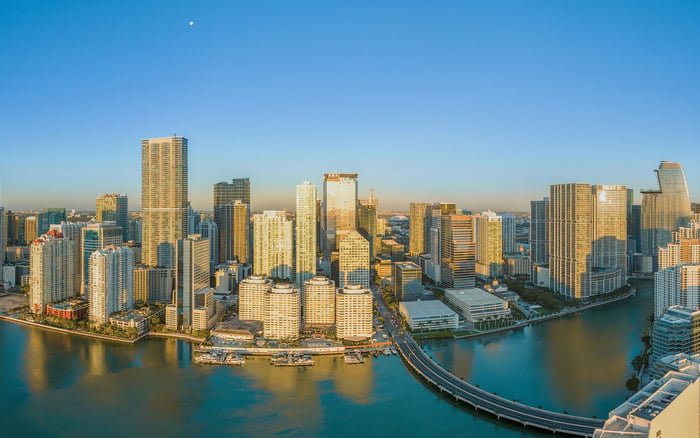
For a purchaser considering Brickell addresses such as Una Residences Brickell, that discipline belongs alongside the property decision. Project references here provide residential context, not representations that seller financing is available.
The sequence below is a practical organizing approach, not a mandatory timetable. Reporting, seller underwriting, sanctions review, and recording each require a separate determination.
A March 19, 2026 federal court order vacated the federal Residential Real Estate Rule. While that order remains effective, reporting persons need not make the rule’s filings and face no liability for not doing so. An appeal is pending, so recheck the rule’s status before closing rather than treating it as permanently settled.
Under the rule’s framework, seller carryback financing can still constitute a “non-financed” transfer. The relevant financing test requires credit secured by the transferred property and extended by a financial institution subject to both anti-money-laundering program and suspicious-activity-reporting requirements. A mortgage securing the seller’s note does not, by itself, satisfy that test.
The framework addresses certain residential transfers to legal entities or trusts, subject to exemptions. Condominiums can qualify. At the offer stage, ask counsel to distinguish the buyer’s proposed ownership structure from the transaction’s financing classification.
Before circulating financial documents, consider agreeing on what the seller needs to evaluate the proposed credit, who will review it, and when that review should conclude. These are suggested transaction arrangements, not universal requirements established by the payment-reporting framework.
Keep three purposes distinct: documenting closing payments, assessing the buyer’s creditworthiness, and evaluating sanctions concerns. A request justified by one purpose should not automatically grant unrestricted access to every participant.
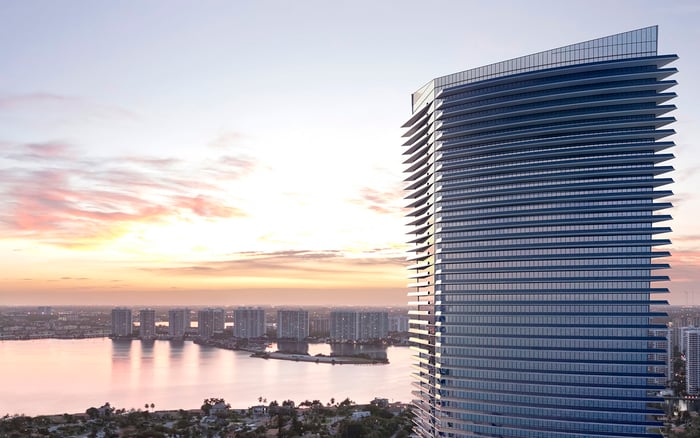
For a Miami Beach buyer evaluating The Perigon Miami Beach, the practical question is not whether discretion matters, but how the contract team will implement it. Consider assigning responsibility for requesting documents, resolving discrepancies, and communicating completion without recirculating the underlying financial file.
A useful source-of-funds file explains the proposed payment path rather than merely accumulating paperwork. As an organizational measure, prepare a payment schedule that distinguishes the deposit, subsequent contributions, closing funds, and seller-financed portion. Reconcile it with the agreed consideration.
If federal reporting obligations become operative and the transfer is covered, the framework can require total consideration, whether non-bank credit was involved, and individual payment amounts and methods. Payments from financial-institution accounts can require institution and account-number information. Escrow or trust-account disbursements receive special treatment, so counsel should determine the applicable fields rather than assume every payment receives identical treatment.
A payor different from the purchasing entity or trust can also require identification under that framework. Flag that distinction early. These payment fields do not themselves establish a universal obligation to provide tax returns, a comprehensive source-of-wealth dossier, or a bank-reference letter.
If a seller requests a bank reference, first clarify the question it is meant to answer. Relationship confirmation, information about available funds, and the seller’s assessment of future repayment are different inquiries. Do not assume a single letter resolves them all.
The parties can discuss an acceptable form and a counsel-approved approach to confirming authenticity, with appropriate buyer authorization. This is a suggested underwriting arrangement, not a prescribed verification procedure. No universal bank-reference requirement or verification standard is established here.
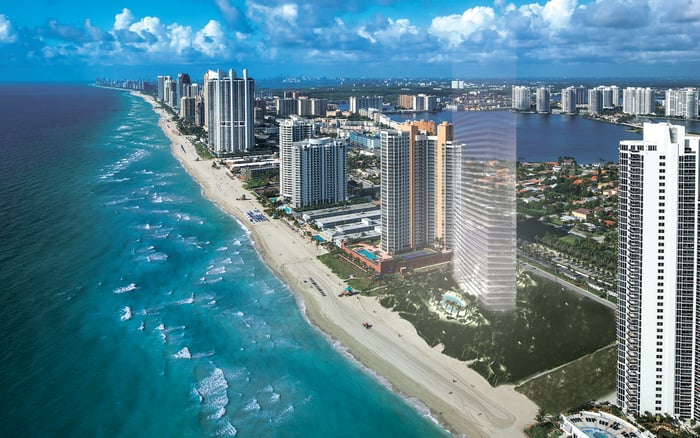
For a Sunny Isles Beach purchaser considering Jade Signature Sunny Isles Beach, the same distinction applies: identify a seller’s negotiated credit request as such, rather than presenting it as an automatic government filing requirement.
A prudent screening approach considers relevant transaction parties and ownership relationships rather than stopping at the purchasing entity’s name. Ask counsel to define the review’s scope and evaluate potential matches before anyone characterizes a transaction as cleared.
Ownership and control should not be treated as legally interchangeable. Their significance requires analysis under the applicable sanctions rules; a broad screening recommendation is not itself a legal conclusion.
Consider revisiting screening when ownership, contract, or completion details change, including changes affecting the seller or contracting owner. Maintain a concise record of what changed, who reviewed it, and whether any issue remains unresolved. This is a recommended workflow, not a claim that a single screening exercise or commercial checklist satisfies every applicable duty.
For a South Florida transaction, recording instructions warrant specific legal review. The 2023 edition of Florida Chapter 494 contains provisions requiring an original or certified copy of a mortgage or other instrument securing a note or assignment to be recorded before delivery to a noninstitutional investor in covered circumstances.
Those provisions also require mortgages and assignments to be recorded as soon as practical and no later than 30 business days after closing in the circumstances they cover. This is not a universal deadline for every seller-financed condominium purchase. Counsel should confirm current law and applicability before relying on either requirement.
As a closing-management measure, identify who handles submission, confirms recording, addresses any rejection, and coordinates document delivery. Signing is not confirmation that recording has occurred.
Privacy controls should be deliberate, not implied. Consider role-based access, a controlled document-sharing channel, and separate handling of sensitive account information. Have counsel and the closing team determine appropriate security measures, broker access, retention, and disposal arrangements. No particular encryption standard, retention period, or blanket broker-access prohibition is established here.
At completion, reconcile the final payments, retain the agreed closing and recording evidence, and distinguish unresolved items from completed tasks. Assess any reporting obligation against the rule’s operative status and the transaction’s actual circumstances rather than assuming it from an earlier checklist.
The objective is a file that supports the transaction without putting the buyer’s financial life into general circulation.
Explore South Florida’s residential landscape with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Under the rule’s framework, seller carryback financing can constitute a non-financed transfer even when a mortgage secures the seller’s note.
No. Reporting persons need not make the rule’s filings and face no liability for not filing while that order remains effective; the pending appeal makes a pre-closing status check important.
The credit must be secured by the transferred property and extended by a financial institution subject to both anti-money-laundering program and suspicious-activity-reporting requirements.
Yes. Certain non-financed residential transfers to legal entities or trusts can fall within the framework, including condominiums, subject to applicable exemptions.
If obligations become operative and the transfer is covered, information can include consideration, non-bank credit, individual payment amounts and methods, and applicable institution and account details. Escrow and trust-account disbursements receive special treatment.
The reporting framework can require identification of a payor different from the purchasing entity or trust. Flagging that distinction also helps organize the payment file.
The payment-reporting requirements do not establish a universal bank-reference obligation. A seller’s request should be treated as a separate underwriting question.
A prudent approach considers relevant parties and ownership relationships, with counsel assessing legal significance and potential matches. Ownership and control should not be assumed to have identical legal consequences.
That universal conclusion is not established here. The cited 2023 Florida provisions apply in covered circumstances, and counsel should confirm current law and applicability.
Consider role-based access, controlled document sharing, and agreed handling of sensitive account information. Counsel and the closing team should determine appropriate security, access, retention, and disposal arrangements.