A Singapore-to-Fort Lauderdale relocation calls for more than a preferred address. Property-specific insurance quotes, dollar-based deductible planning, coordinated condominium coverage, and flexible shipment arrangements should shape the purchase from the shortlist onward.
For a household moving from Singapore to Fort Lauderdale, the property decision should serve two ambitions: an exceptional place to live and a carefully managed arrival. Insurance belongs alongside architecture, privacy, and daily convenience in that assessment. A residence is not fully evaluated until its coverage terms, deductible exposure, and practical handover arrangements are understood.
In a Fort Lauderdale and Broward property search, make insurability a shortlist criterion, not a closing-week task. Obtain property-specific quotes before committing, then coordinate the chosen policy with possession, international shipping, and temporary accommodation. The objective is more than a competitive premium: it is a clear understanding of the financial exposure and arrival arrangements attached to each home.
Ask an insurance adviser to prepare a comparison for every serious candidate. Each quotation should identify the insured dwelling limit, replacement-cost assumptions, annual premium, hurricane deductible in both percentage and dollar terms, other wind deductibles, and relevant restrictions. A lower premium is not necessarily comparable if it assumes less coverage or shifts more loss to the owner.
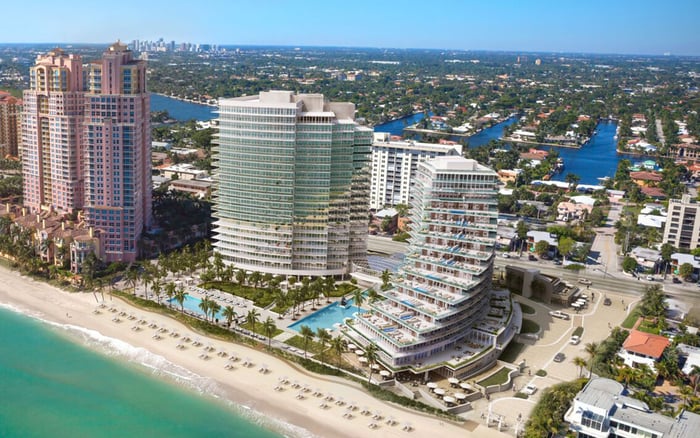
For a buyer considering Four Seasons Hotel & Private Residences Fort Lauderdale, the same discipline applies: obtain documents for the particular residence rather than treating the project name as evidence of coverage. Project references here provide search context, not representations about insurance terms or availability.
Request documentation of shutters, impact-rated openings, and roof strengthening where applicable. These improvements can reduce damage risk and may qualify for insurance savings, but any credit should appear in the actual quotation. Keep a written record of assumptions, then check the final policy against the comparison that informed the purchase.
For homeowners policies, percentage hurricane deductibles are generally calculated from Coverage A, the insured dwelling limit, rather than the purchase price. That distinction matters when evaluating a substantial acquisition: the negotiated price is not the figure to multiply automatically.
With US$3 million of dwelling coverage, a 2% hurricane deductible represents US$60,000; 5% represents US$150,000. With US$5 million to US$10 million of dwelling coverage, a 5% deductible represents US$250,000 to US$500,000. These figures illustrate deductible exposure; they are not quotations for any residence.
Florida's hurricane-deductible options include US$500, 2%, 5%, and 10%, but required offerings have exceptions based on insured value. Confirm which choices are available for the property. A US$500 deductible should not be treated as a realistic benchmark for a luxury detached home.
The deductible is the owner's portion of covered damage before the insurer pays, not an automatic bill triggered by a hurricane. Even so, translate the selected percentage into an accessible US-dollar reserve, with additional funds for temporary accommodation and emergency work. For an international relocation, arrange access to that reserve before possession rather than leaving it until after arrival.
A hurricane deductible concerns covered damage associated with a designated hurricane. It is not interchangeable with the deductible for every named tropical storm. Ask the adviser to distinguish hurricane, other windstorm, and all-other-perils terms, including how qualifying tropical-storm, tornado, or hail damage would be handled.
Florida's statutory hurricane period begins when a hurricane warning is issued for any part of the state and ends 72 hours after the last Florida hurricane watch or warning terminates. This defines a deductible period, not the point at which every insurer will resume binding coverage.
The hurricane deductible generally operates on a calendar-year basis, subject to requirements including continued coverage with the same insurer or insurer group. Once the applicable deductible is satisfied, subsequent covered hurricane losses that year are generally subject to the all-other-perils deductible. Do not assume a seller's earlier loss satisfies a new buyer's deductible, or that postponing renovations changes the calendar-year reset.
Review a condominium's association master policy, deductible-allocation provisions, unit owner's HO-6 policy, and loss-assessment coverage together. Ask who bears each category of loss and how any association deductible might fall to the owner. Check the unit policy for a separate wind deductible rather than assuming the master policy resolves every exposure.
When evaluating Auberge Beach Residences & Spa Fort Lauderdale, request the relevant association and unit-policy documents for the specific purchase. Apply the same review to a candidate at Sixth & Rio Fort Lauderdale. The useful comparison is not branding, but documented responsibility for the building, unit, contents, and potential assessments.
Do not apply detached-home deductible illustrations mechanically to a condominium purchase price. Have the adviser identify the applicable coverage limits and deductible calculations for each policy. Review personal-property limits and sublimits as carefully as building-related protection, especially before directing household contents to the residence.
Before fixing possession and international delivery dates, ask the insurer when coverage can be bound, what approaching-storm restrictions apply, and whether the effective date matches possession. Obtain confirmation for the actual transaction rather than relying on an assumed universal moratorium timetable.
For a planned relocation involving St. Regis® Residences Bahia Mar Fort Lauderdale, verify the residence's actual handover arrangements before tying Singapore shipment dates to them. A preferred address and a confirmed delivery window are separate decisions.
Prepare a written contingency plan with the shipping provider, storage operator, movers, and temporary-accommodation provider. Establish who can pause delivery, where belongings can remain, and who will confirm that the property is ready to receive them if an approaching storm changes the schedule.
Confirm precisely where marine or transit insurance ends and destination coverage begins. Do not assume homeowners insurance covers the international shipment. Even after arrival, contents protection remains subject to policy limits, deductibles, and applicable sublimits. Confirm storage coverage explicitly rather than assuming either policy extends to every holding arrangement.
Before arrival, assemble policy documents, binding confirmation, inventories, condition photographs, and insurer contact details in one accessible file. Nominate a local contact to coordinate access and documentation if the household remains in Singapore when circumstances change.
Report damage promptly. In Florida, notice deadlines for hurricane and windstorm claims are generally one year for initial notices and 18 months for supplemental notices, measured from the applicable landfall or damage date. Treat those limits as backstops, not reasons to delay.
The strongest property decision combines a desirable residence with clearly understood coverage, accessible reserves, and a move-in plan that can pause without forcing delivery into an unprepared home.
For a considered Fort Lauderdale property search aligned with your relocation priorities, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationObtain property-specific quotes for serious shortlisted residences before committing. Compare coverage assumptions and dollar deductibles alongside premiums.
For homeowners policies, percentage hurricane deductibles are generally based on Coverage A, the insured dwelling limit, rather than the purchase price.
It represents US$60,000 of deductible exposure; a 5% deductible on the same limit represents US$150,000. These calculations are illustrations, not property-specific quotes.
No. A deductible is the policyholder's portion of covered damage before the insurer pays, not a charge automatically due when a hurricane occurs.
No. Hurricane and other windstorm deductible terms must be distinguished, and the applicable treatment depends on the event and policy.
Florida's hurricane deductible generally operates on a calendar-year basis, subject to conditions including maintaining coverage with the same insurer or insurer group. Later covered hurricane losses generally use the all-other-perils deductible once the applicable hurricane deductible is satisfied.
Review the association's master policy, deductible-allocation provisions, HO-6 policy, and loss-assessment coverage together. Confirm the unit policy's wind deductible and personal-property limits.
No universal binding timetable follows from the statutory 72-hour hurricane-deductible period. Ask the insurer about transaction-specific binding restrictions and the effective date.
Do not assume it does. Confirm where marine or transit insurance ends and destination coverage begins, including any storage interval.
Arrange flexible shipment delivery, storage, movers, and temporary accommodation before arrival. Identify who can pause delivery and verify that the residence is ready to receive belongings.