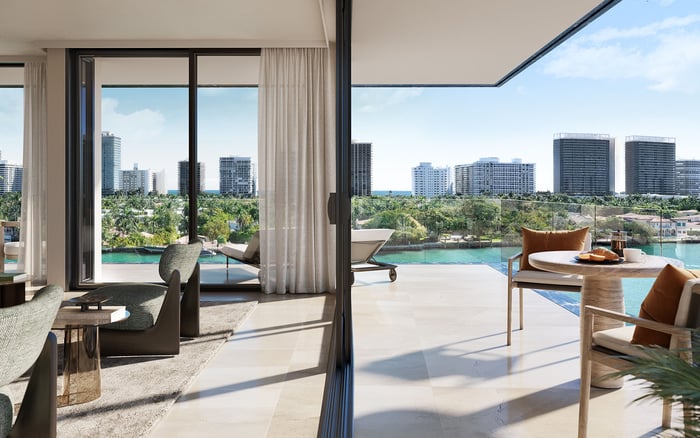
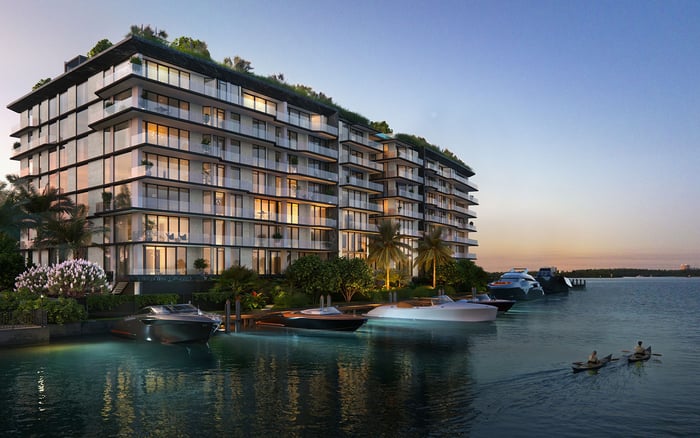
For a move from Munich to Bay Harbor Islands, a considered purchase starts with three distinct reviews: the building’s mapped flood zone, its documented elevation and the precise division of insurance responsibilities between association and owner.
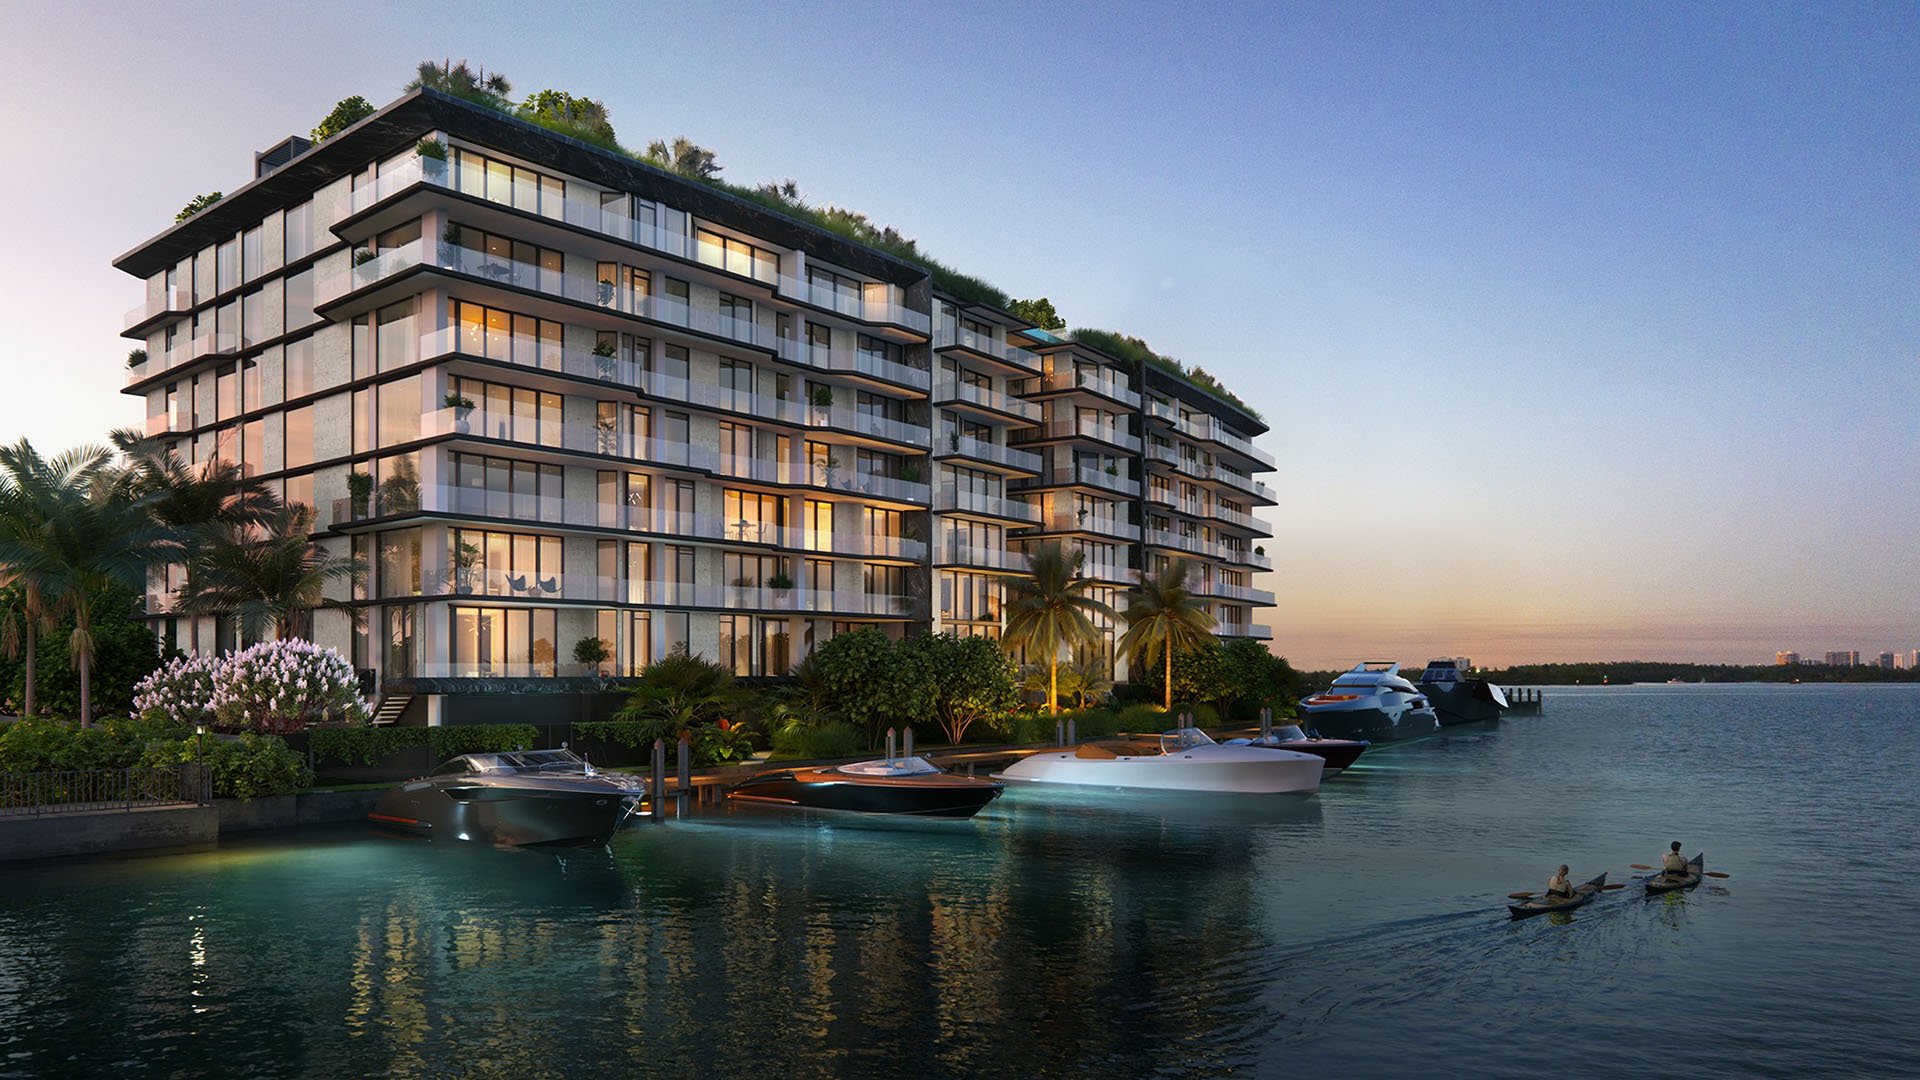
A move from Munich to Bay Harbor Islands invites decisions about space, light and the rhythm of a new home. Less visible choices deserve equal attention: the property’s mapped flood zone, its documented elevation and the limits of the condominium association’s insurance. These are separate questions. A reassuring answer to one does not resolve the others.
Whether your search stays within Bay Harbor Islands or extends to Bal Harbour, assess each building rather than relying on neighborhood assumptions. For a residence at Alana Bay Harbor Islands, as for any candidate, the relevant evidence concerns the particular property, not its marketing category.
For a relocating buyer, the practical adjustment is to understand Florida’s allocation of responsibilities without importing assumptions from a previous home. Ask your attorney, insurance adviser and property representative to organize the review around three subjects: location, elevation and coverage.
Start with an address-level search of the federal flood maps. Record the designation for each candidate building and seek clarification wherever the map or property boundaries raise questions. An island-wide description is no substitute for this step.
For property-specific flood information and help with map questions, contact the town’s Building Department. Confirm which information applies to the property and what elevation records may be available.
If Bay Harbor Towers enters the shortlist, apply the same discipline before comparing it with another residence. A project name establishes neither its flood designation nor the insurance terms available to an individual buyer.
Keep the map inquiry separate from loss history. A mapped classification does not establish whether a seller has made a flood-damage insurance claim or received federal assistance for flood damage. Those questions belong in the disclosure review.
A general terrain figure is not a building credential. An island-wide elevation estimate does not establish any particular structure’s finished-floor elevation.
Request available building elevation records, including an elevation certificate if one is available, and confirm the applicable flood-elevation requirements with the town. Ask your adviser to distinguish terrain elevation, finished-floor elevation and the regulatory elevation relevant to the structure. Comparisons are useful only when the measurements describe the same thing.
This distinction also matters when planning improvements. Ask whether substantial damage or substantial improvement could trigger elevation requirements for the particular structure. Do not infer that a condominium must be elevated from a general description of the rules.
Before committing to an ambitious interior redesign, have counsel and the appropriate technical adviser clarify whether the proposed work raises any applicable flood-elevation questions. The aim is to understand the conditions attached to ownership, not to infer an obligation from a general map or an attractive floor plan.
A seawall deserves a separate inquiry, distinct from the building’s finished-floor review. Ask the town which seawall-cap elevation requirements, if any, apply to the property before incorporating potential work into a purchase budget.
For a candidate such as La Maré Bay Harbor Islands, ask whether any relevant seawall documentation, work proposals or funding decisions apply to the property. These are requests for evidence, not assertions that work is required.
A general reference to a seawall requirement does not establish that an existing condominium must immediately rebuild a seawall or impose a special assessment. Separate the applicable rule, the documented physical condition and any actual association decision. Only then can a potential obligation be meaningfully evaluated.
Have Florida counsel confirm the flood-disclosure requirements and delivery deadlines applicable to your transaction. Ask counsel to review both state and county requirements, including any obligations associated with a Special Flood Hazard Area or Coastal High Hazard Area designation.
Review the disclosure’s answers about flood-damage insurance claims and federal assistance received for flood damage. Read them alongside the mapped zone, not as a replacement for it. Financial loss history and geographic classification address different aspects of the purchase.
For a purchase coordinated from Munich, request these materials early enough for substantive review. A disclosure delivered at a legally permitted moment is not necessarily one you want to interpret for the first time while deciding whether to sign.
“The building is insured” begins an insurance conversation; it does not conclude it. Association master property coverage and individual owner coverage address different property interests, subject to the condominium documents and actual policy terms.
Ask your advisers to identify the coverage and responsibility for drywall, interior doors, tubs, sinks and toilets, then separately review floor, wall and ceiling coverings, cabinets, countertops, electrical fixtures, appliances, water heaters and window treatments. Do not assume that coverage for the building extends to every interior component or improvement. For a carefully finished residence, this review can encompass much of its interior character.
When evaluating The Well Bay Harbor Islands, obtain the actual policy documents rather than inferring the allocation from the project’s identity. Review limits, deductibles and exclusions before determining the amount of separate unit coverage for finishes and improvements.
Ask whether master property coverage is primary for the property and loss in question. Coverage priority does not mean every cause of loss is insured. Do not assume that a homeowners policy includes flood protection; discuss separate flood coverage with your insurance adviser.
Do not automatically apply the master property policy’s component exclusions to an association flood policy. Review any association flood coverage on its own terms. The appropriate owner-side arrangement follows the documents, not a blanket prescription that every purchaser needs a fixed number of policies.
Before proceeding, assemble a concise record for each finalist: mapped zone, available elevation documentation, seller disclosures, condominium documents and actual insurance terms. Keep unresolved questions visible, especially where they affect planned improvements or the protection of valuable finishes.
The strongest choice is not the residence with the most reassuring general description. It is the one whose obligations you understand well enough to accept, insure and budget for with confidence.
For a considered approach to your South Florida property search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Check each candidate building through an address-level federal flood-map search and clarify property-specific questions with the town.
Contact the town’s Building Department to ask about property-specific flood information, map questions and available elevation records.
No. A general terrain figure is not a measurement of a particular building’s finished floor.
Request available building elevation records, including an elevation certificate if available. Confirm the applicable flood-elevation requirements with the town.
Ask counsel and a technical adviser whether the proposed work could trigger flood-elevation requirements for the particular structure. Do not assume an obligation from a general map or floor plan.
Request them early enough for substantive review before deciding whether to sign. Have Florida counsel confirm the applicable state and county requirements and delivery deadlines.
The zone identifies a mapped classification, while disclosure questions address flood-damage insurance claims and federal assistance received. Neither inquiry replaces the other.
No. Have your advisers check the condominium documents and actual policy terms for each category of finishes and improvements before arranging owner coverage.
No. Review each policy separately, and do not assume that the component exclusions in a master property policy apply identically to an association flood policy.
No. Confirm the requirement’s applicability with the town and review property-specific documentation and association decisions before inferring work or funding obligations.