For buyers relocating from Monaco, a Fort Lauderdale residence deserves three separate reviews: future resale demand, association approval requirements and total association-related closing charges. The strongest decision balances lifestyle appeal with documented financial and administrative clarity.
A move from Monaco to Fort Lauderdale invites an appealing property search. Yet the residence that feels right on arrival should also stand up to scrutiny as a future resale. Beyond architecture and service, the decision should address three distinct questions: who might buy the property next, what approvals that buyer would need, and which association charges would accompany the transfer.
These questions belong together, but they are not interchangeable. A modest application fee does not establish liquidity. An orderly approval process does not resolve underfunded reserves. And a residence with compelling personal appeal still requires a realistic assessment of its eventual buyer pool.
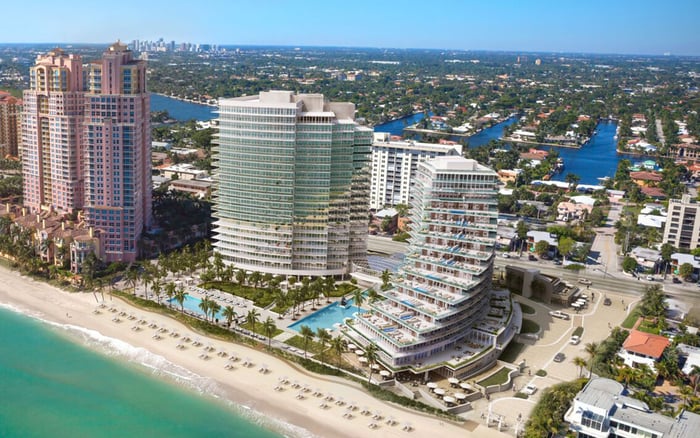
If your shortlist includes Four Seasons Hotel & Private Residences Fort Lauderdale, apply the same discipline as elsewhere: evaluate the residence, its governing framework and its financial obligations separately. A name is no substitute for transaction-specific documentation.
Treat liquidity as a question to investigate, not a feature to assume. Ask your adviser to assess comparable transactions, competing availability and the likely audience for the residence. Consider whether its layout and ownership costs would suit buyers beyond your own household. These are screening questions, not guarantees of sale speed or price.
Pair fresh property-level market analysis with an association review. Leasing and pet restrictions help determine whether a residence suits your intended use and a future purchaser's needs. Do not assume renting will offer an unrestricted alternative to selling.
When considering Auberge Beach Residences & Spa Fort Lauderdale, for example, request the relevant documents rather than inferring resale flexibility from the property's identity. Apply the same standard to every candidate.
Association approval is not a universal requirement for Florida condominium resales. The governing documents determine whether a particular property requires it. Establish that point before building a relocation or closing timetable around an assumed process.
Request written confirmation of the approval requirement, the applicable document provisions, application requirements and submission deadlines. Ask whether a master association is involved and whether it adds a separate review or charge. Where approval applies, your closing team should identify how its completion will be documented.
For an international move, make the administrative sequence explicit: which materials must be submitted, who receives them and what remains outstanding before closing. Have counsel review the applicable conditions rather than relying on a verbal account of a building's customary practice.
Apply this discipline when evaluating Sixth & Rio Fort Lauderdale. Confirm the rules relevant to the contemplated transaction; do not assume one project's procedures establish a precedent for another. Clear requirements support planning, but they do not establish stronger resale demand.
A condominium association may charge for transfer approval only when it is required to approve the transfer and the fee is authorized in its declaration, articles or bylaws. Check the authority to charge alongside the amount requested.
The statutory transfer-fee cap has a $150 base per applicant, subject to CPI adjustment every five years. Confirm the applicable adjusted limit for the transaction rather than treating $150 as a permanently fixed ceiling. For this purpose, spouses count as one applicant, as do parents with dependent children.
An itemized fee schedule is more useful than a single estimate labeled association costs. Ask the closing team to identify each charge's purpose, legal or document authority, recipient and allocation between buyer and seller. Review transfer approval, estoppel preparation and any claimed capital contribution as separate charges.
A condominium charge does not automatically escape the transfer-fee limit simply because it is called a resale capital contribution. If the characterization is unclear, have Florida counsel examine it before accepting the amount as payable. The objective is to distinguish authorized costs from charges that require further scrutiny.
Do not evaluate a homeowners' association using the condominium transfer-fee ceiling. HOA transfer fees have no equivalent statutory dollar cap; their authorization and amount depend on the community's governing documents.
Those documents may also authorize resale capital contributions or initiation fees. When comparing an HOA-governed gated community with a condominium, request a complete fee schedule rather than comparing application fees alone. Confirm any master-association involvement and ask counsel to identify the authority for each association-related charge.
This is a comparison of legal structures, not a judgment that one ownership format is inherently preferable. What matters is understanding the obligations attached to the specific property before committing.
A condominium estoppel certificate must disclose whether board approval is required for the transfer and, if so, whether it has been granted. It also identifies association amounts affecting closing, including regular assessments, amounts owed and specified additional assessments coming due.
The association must issue the certificate within 10 business days after receiving a qualifying request. That is an estoppel-delivery requirement-not a promise that buyer approval will be completed within the same period.
Estoppel fees are distinct from transfer-approval fees and have their own statutory limits, including provisions for expedited requests and delinquent accounts. Coordinate the certificate with the approval record and closing statement. No single document constitutes a complete review of the building.
Condominium resale buyers are entitled to governing documents prepared at the seller's expense, including the declaration, articles of incorporation, bylaws and rules. Required documentation also includes the latest annual financial statement and annual budget, together with applicable milestone-inspection, structural-integrity reserve-study and turnover-inspection documentation.
Review these materials for operating costs, reserve funding, building-condition issues and assessments. Request recent board minutes as an additional due-diligence step. A low transfer fee cannot answer questions about future ownership expenses.
For a candidate such as St. Regis® Residences Bahia Mar Fort Lauderdale, first establish which documents and transaction rules apply. Across the shortlist, keep your conclusions separate: the evidence of potential resale demand, the clarity of approval requirements and the full association-related financial picture. Sound finances and streamlined administration remain screening considerations, not resale guarantees.
For a discreet property conversation grounded in both lifestyle and ownership discipline, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. The property's governing documents establish whether association approval is required for a resale.
It must be required to approve the transfer, and the fee must be authorized in its declaration, articles or bylaws. The applicable statutory limit must also be checked.
No. The statute has a $150 base per applicant subject to CPI adjustment every five years, so the applicable adjusted limit should be confirmed.
Spouses count as one applicant, as do parents with dependent children. They should not be treated as separate applicants within those groupings.
No equivalent statutory dollar cap applies to HOA transfer fees. Their authorization and amount depend on the community's governing documents, which may also authorize capital contributions or initiation fees.
Calling a charge a resale capital contribution does not automatically remove it from the statutory transfer-fee limit. Have counsel examine its nature and authority.
It identifies association amounts affecting closing and states whether board approval is required and, if so, whether it has been granted. Estoppel fees are separate from transfer-approval fees.
No. It is the deadline for issuing an estoppel certificate after a qualifying request, not a buyer-approval completion deadline.
Review the latest annual financial statement, annual budget and applicable inspection and structural-integrity reserve-study documentation alongside the governing documents. Request recent board minutes as an additional due-diligence step.
No. They are screening considerations, while future demand, competing availability and building finances require separate evaluation.